PNN: 51m at 15.4% TREO from 24m - the best rare earths hit we have ever seen on the ASX
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 7,338,223 PNN Shares and 4,399,785 PNN Options at the time of publishing this article. The Company has been engaged by PNN to share our commentary on the progress of our Investment in PNN over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
Our Investment Power Minerals (ASX:PNN) just hit the best drill result we have seen from any rare earths company on the ASX.
Numbers that only one or two other rare earths deposits anywhere in the world could replicate.
PNN is capped at just $61M... a fraction of its peers.
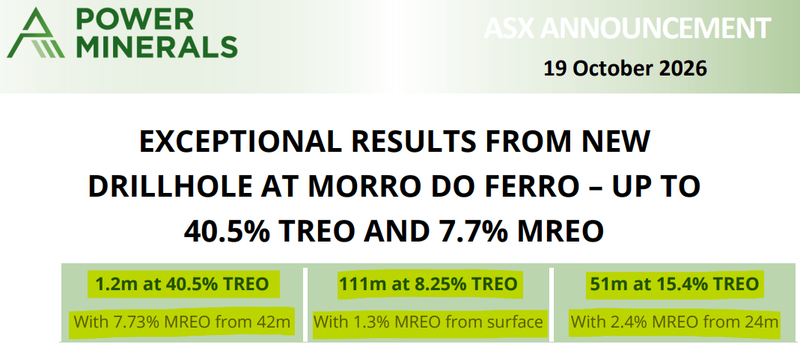
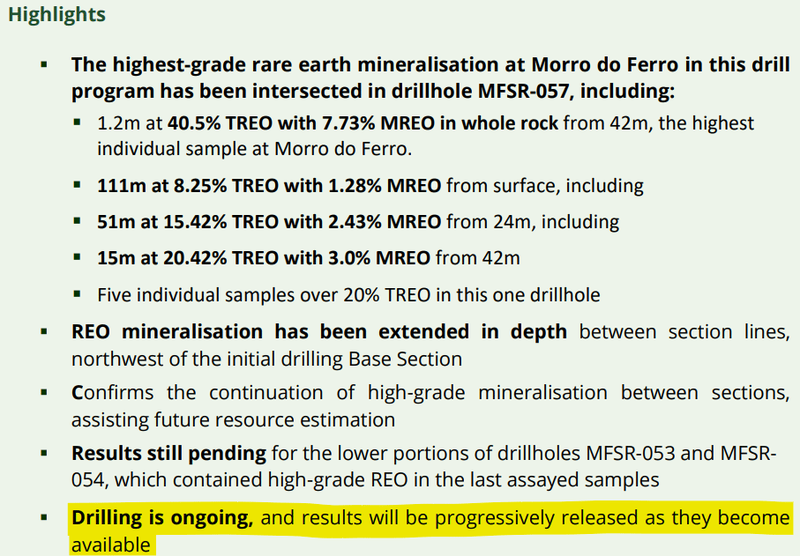
Here is the drill hit:
(source)
Yes, that is not a typo...
15m at 20.4% TREO with 3.0% MREO
51m at 15.4% TREO with 2.43% MREO
All sitting inside a 111m thick intercept averaging 8.3% TREO and 1.28% MREO from surface.
As we mentioned above, these are drill hits that only one or two other rare earths deposits anywhere in the world could replicate.
One of them is the ~US$10BN capped MP Materials' Mountain Pass mine in California - the USA's ONLY producing rare earths mine.
The other is the ~$541M capped Brazilian Rare Earths' Monte Alto deposit, and as the company name suggests, like PNN, it's also in Brazil.
PNN is capped at just $61M.
Both of those bigger companies have deposits with an ultra high grade resource at >10% TREO.
MP's Mountain Pass is ~19Mt at ~7% TREO - and it is the cornerstone asset for the US government's rare earths national champion.
Brazilian Rare Earths' deposit is much smaller, but it's a higher grade - 3.4Mt at 11.26% TREO.
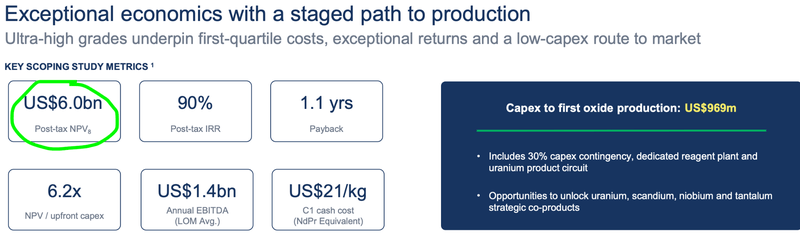
BUT that grade is high enough to deliver a scoping study with a Net Present Value (NPV) of ~US$6BN.
(source)
Which brings us to the other thing we noticed when we put PNN and Brazilian Rare Earths’ cross sections next to each other.
Brazilian Rare Earths’ high grade rare earths mineralisation sits in thin, steeply dipping pods of hard rock, under ~30-40m of cover. Its scoping study plans to drill, blast and selectively mine them on 2m benches. (source)
PNN’s high grade hits start at surface, run 100m+ down every hole, and more than 80% of the drill core is soft, weathered saprolite - the geologists cut it with a steel blade. (source)
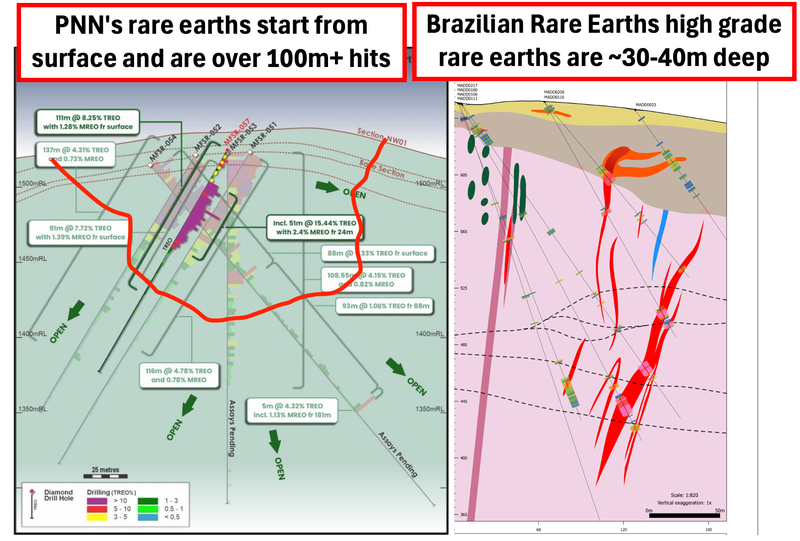
We are not mining engineers, and PNN hasn’t done any official mining or economic studies yet - but on face value, one of those looks a lot simpler and cheaper to dig than the other.
Yep, it's PNN’s.
Right now, PNN’s project has an exploration target of 9.2 - 10.7Mt at 7.8% - 9.2% TREO.
Interestingly, PNN’s grades today being this high were NOT included in its exploration target model that generated the numbers above.
The upper end of PNN’s exploration target (IF converted into a JORC resource estimate) would put it right up there with the current resource Brazilian Rare Earths has.
Brazilian Rare Earths is capped at $541M, MP Materials at $10BN and PNN at $61M.
And now, PNN has intercepts with grades materially higher than the average grade for both those deposits.
Of course, comparing a single intercept to a whole of deposit average shouldn’t be done.
The point for us is that, IF/WHEN PNN can put together its own JORC resource estimate, with grades above OR comparable to the two assets mentioned above, the market COULD then start to reasonably compare PNN’s asset to its peers.
PNN has a maiden JORC resource estimate coming this quarter or next.
So within the next 4-5 months, ASX investors will be able to start drawing direct comparisons between PNN’s asset and Brazilian Rare Earths’.
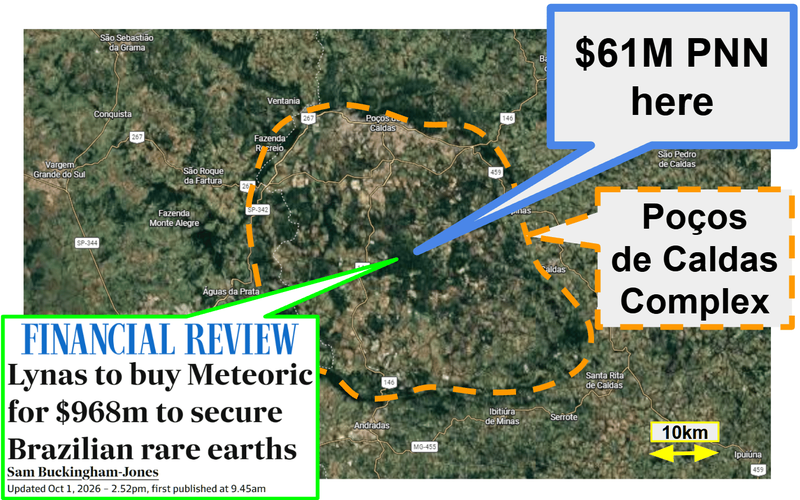
Or maybe, $11BN Lynas who put forward a $968M offer for PNN’s neighbour could see what PNN has to offer and take a liking to it...
Between now and PNN’s maiden JORC resource estimate, there are still two rigs on site drilling - so we will also have a lot more drilling results to come.
(source)
Stroll down Meteoric Lane
PNN announced the acquisition of its project in March this year. (source)
At the time we said it reminded us of when Meteoric acquired its project all those years ago.
Meteoric acquired its asset less than four years ago, in December 2022 - here’s the acquisition announcement.
At the time (like they did with PNN), the market thought it was an expensive deal for a company like Meteoric (who paid US$20M cash) which at the time was nothing more than a cashbox.
Meteoric paid US$20M cash in staged payments (source)
Less than four years later (and with some luck with macro sentiment) - Meteoric got a $968M takeover offer.
We are Invested in PNN to hopefully see something similar happen.
Of course there are no guarantees with our Investment in PNN, Meteoric did come into a rare earths bull market with a strong asset.
PNN’s deal was for total consideration of ~$22.5M - $12M in cash and $10.5M in shares, paid in stages over up to five years as the project hits milestones (plus a 2.5% royalty). (source)
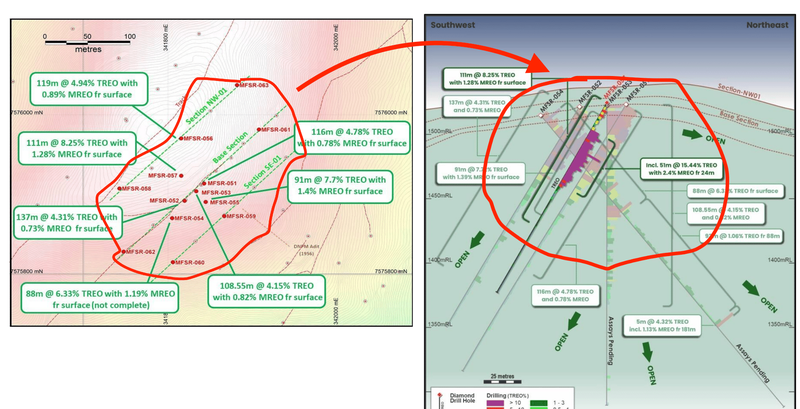
And right now PNN has defined mineralisation across a ~200-300m x 200-300m area (our very rough calculations using that scale on the map below) mineralised from surface down to 100-150m:
(source)
Here’s why we think PNN could end up “doing a Meteoric"
PNN is currently capped at $61M.
Meteoric recently received a takeover offer valuing the company at $968M.
The reasons we think PNN could end up “doing a Meteoric” over the coming years are:
- PNN's project sits on a "Manifesto de Mina" - a mining title with no expiry. Only environmental permitting is needed to get to production, and PNN owns the freehold land on top.
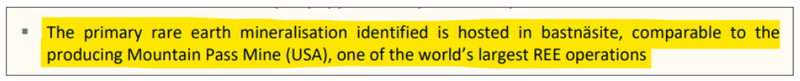
- PNN’s project is hosted in “bastnäsite” - we are not geos but according to PNN it’s the same mineral type that MP Materials is mining at its project in California.
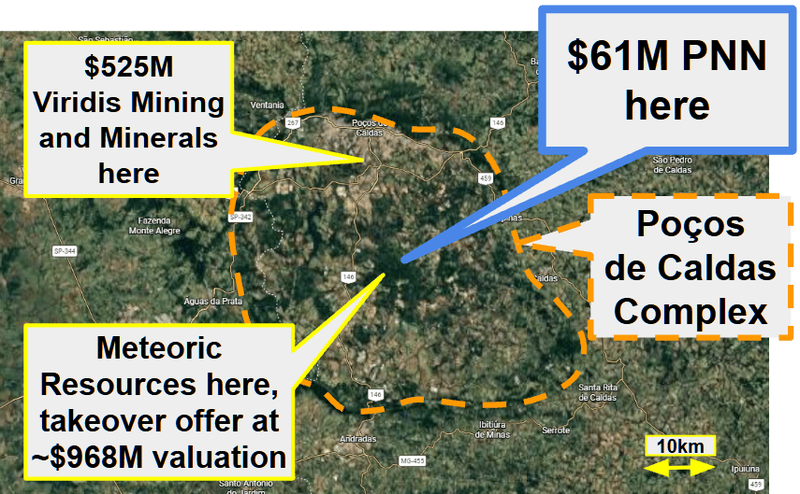
- It sits next door to Meteoric’s project - the one Lynas Rare Earths have offered ~$968M for - meaning there is corporate activity nearby.
- The project also has “Ionic Clay” potential - more on this later, but PNN has said in the past that parts of its project could ALSO host a similar mineralisation style as Meteoric’s.
- The project has very high magnet rare earth grades - The four “magnet rare earths” used in EV motors, drones, humanoid robots, fighter jets and guided missiles.
For context - and yes, it's only one drill hit, but PNN’s MREO grades from today’s intercept were ~10x Meteoric’s entire resource grades.
IF Lynas ends up completing the Meteoric deal we think it could be very good for PNN.
Lynas up until now have only ever mined hard rock carbonatite rare earth projects.
(the same type of geology PNN’s project has).
The cashed up, giant of the industry, Lynas, by entering this region, COULD always look at bolting on other projects - especially ones that they understand well.
Especially with PNN’s CEO Alistair Stephens having previously mentioned how its project could actually host the source structure for all the ionic clay deposits in the area (like Meteoric’s).
Here is what he said in an interview a few months back:
“At this stage it looks like what we’ve got is primary mineralisation and it may well be the pipe that’s actually feeding that entire Caldeira project with all the rare earths.
So you get minerals at the pipe, and as you get further and further away you get minerals and clay, and then further away again you get clay on the outskirts.”
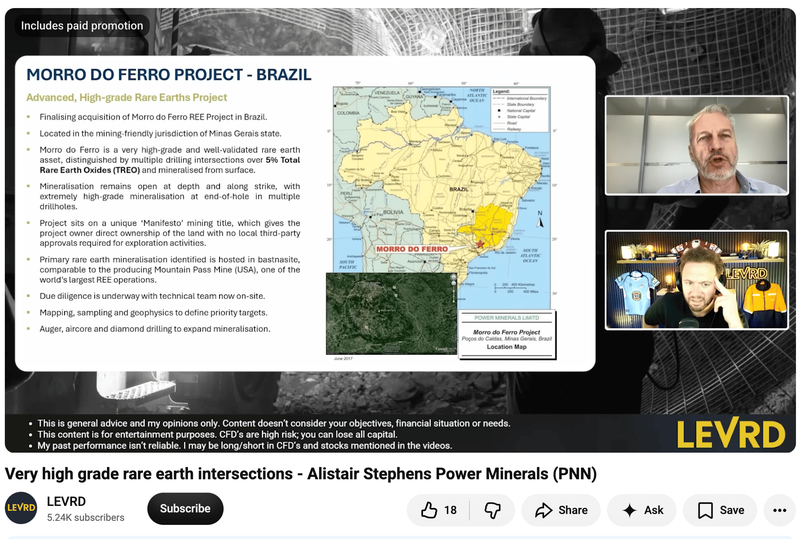
(check out the full interview here)
(we are not saying Lynas will do anything with PNN, but it’s not hard to see why PNN’s ground would be on its radar.)
And finally... we like PNN’s asset because we really like Brazil as a rare earth jurisdiction.
Why rare earths in Brazil?
The big rare earth elephant in the room is still there for Western supply chains.
China still controls ~90% of the world's rare earth magnet supply chain. (source)
For the heaviest, most valuable rare earths like dysprosium and terbium, China controls ~98-99% of refined supply. (source)
Right now dysprosium and terbium (two of PNN's four magnet metals) still need case-by-case export licences out of China. (source)
And a few months ago, China banned exports of "dual-use items" to US defence contractors including two US rare earths companies - MP Materials and USA Rare Earth. (source)
No wonder USA Rare Earths did that Serra Verde deal... (MP to act next?)
China’s export restrictions are still in play with the pause on expanded rare earth controls to have ended on the 10th of November (source), which last month was extended by two months (source).
(that's less than three months away)
Enter Brazil... as an alternative to Chinese rare earth supply for the USA.
Brazil is home to the world's second biggest rare earth reserves (behind only China). (source)
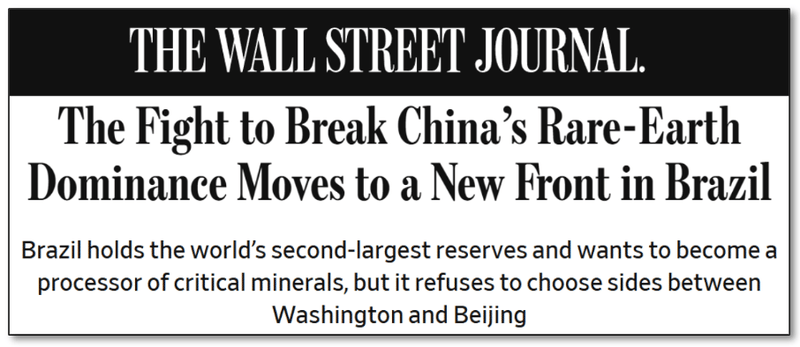
Below is an article specifically highlighting the region that PNN's project sits in as a rare earth hotspot inside Brazil, the Wall Street Journal calling it the "new front" for rare earths:
(source)
There is also corporate interest in Brazilian assets:
- The US$2.8BN USA Rare Earth's takeover of Serra Verde - the only large-scale producer outside Asia producing rare earths from ionic clays. (source)
- A US$250M letter of interest from the Export-Import Bank of the United States (EXIM) to PNN's next door neighbour Meteoric Resources for its Caldeira project. (source)
- And then two weeks ago, the takeover offer from Lynas for Meteoric's project next door to PNN. (source)
Even the EU is looking to do a Brazil minerals deal:
(source)
We think that any Western solution to a rare earth supply problem is going to have Brazil in it (at least at the upstream level).
Which is why we hold PNN... and SGQ (check that one out here).
Why we are bullish rare earths - Flying cars, humanoid robots and robot soldiers...
Rare earths are a group of 17 metals.
Four of them, the magnet rare earths: neodymium, praseodymium, dysprosium and terbium - are used to make high performance magnets used in robots, drones, fighter jets, guided missiles, smartphones and the cooling systems of AI data centres.
These have no commercial substitutes...
An F-35 contains ~400kg of rare earth materials.
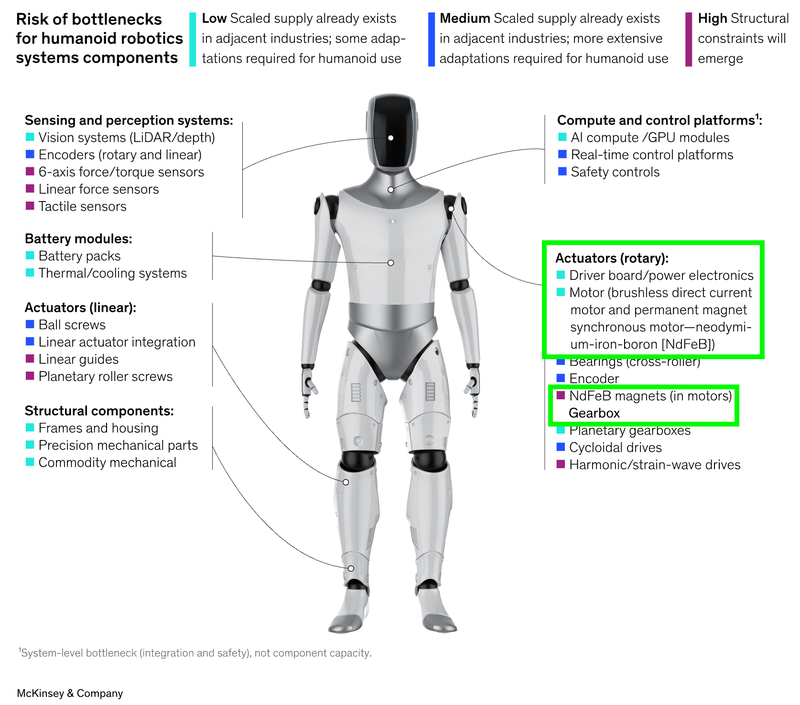
A single Electric Vehicle uses 1-2kg of rare earth magnets and a humanoid robot is expected to use more. (source)
(source)
So every robot, every drone and every data centre that gets built from here needs more rare earths.
With everything happening around the world right now we think the fragility in military supply chains is what has created a big sense of urgency in the rare earths market.
US think-tank CSIS (Center for Strategic and International Studies) has previously said:
"The availability of rare earth elements for defense production will be as decisive as soldiers on the battlefield."
(source - CSIS, Deterrence Runs on Rare Earths, July 2025)
Then, a couple of weeks ago we listened to a podcast with popular energy analyst Doomberg.
~1 hour in he makes a big call saying "that World War III is a war of attrition around rare earths."
(source - from ~1:07:10)
Both the CSIS and Doomberg are underlining the fact that modern conflicts chew through weapons inventories - missiles, interceptors, drones - faster than anyone can rebuild.
He also says "You can't go to war with your own factories." (source at ~1:07:44)
Meaning: if your adversary controls the input to your weapons factories, you're not really independent.
Taking a dig at Western dependence on the raw materials that go into the military supply chain...
We think he is right and think the current rush of capital and government support into rare earths is primarily because of the military conflicts that seem to be constantly escalating around the world.
Whatever happens from here - we think there is a 3-5 year window for assets like PNN's to capture market, corporate and government attention and get enough funding to be developed.
We are Invested in PNN to see it achieve our Big Bet as follows:
Our PNN Big Bet:
"PNN proves up a major high-grade rare earths resource in Brazil and re-rates 1,000% from our Initial Entry Price - via development, strategic investment or acquisition"
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our PNN Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
11 reasons why we are Invested in PNN
Here are the reasons we set out as part of our most recent PNN Investment Memo on the 15th of June 2026. Read that full article here.
We have added some minor updates to the reasons where necessary.
1. Rare earths as an exposure to AI and Robotics
Rare earths are a group of 17 metals, a small group of them - neodymium, praseodymium, dysprosium and terbium - are used to make the strongest permanent magnets on earth.
Those magnets are in EV motors, wind turbines, robots, drones, fighter jets, guided missiles, smartphones and the cooling systems of AI data centres.
There are no commercial substitutes.
An F-35 contains ~400kg of rare earth materials. A single EV uses 1-2kg of rare earth magnets. A humanoid robot is expected to use more.
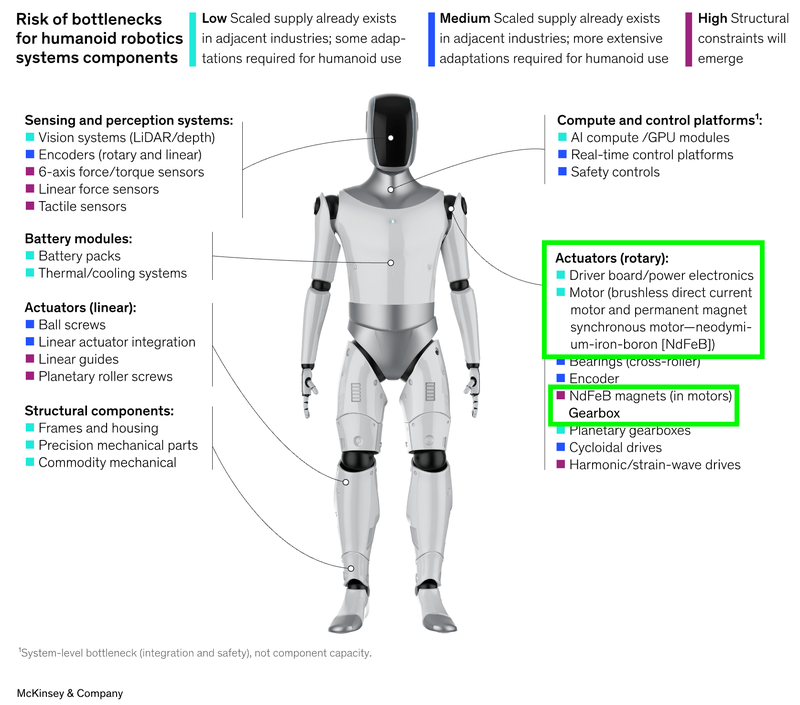
(source)
2. PNN's project is advanced stage (an existing discovery)
PNN’s project has passed the early exploration stage with ~156 holes drilled into it.
The asset has already had 50 drill holes for a total of over 4,000m of diamond core drilling AND 106 holes for a total of 846.5m of auger drilling.
The existing discovery de-risks the asset from an exploration perspective and gives PNN something to expand.
🚨UPDATE:
PNN is active on the drilling front now, and continues to release assay results.
3. PNN’s project has some of the highest rare earth grades we have seen on the ASX
Historic drilling at Morro do Ferro returned 60.85m at 8.92% TREO, 70.9m at 8.00% TREO and 100.44m at 4.99% TREO - all from surface to the end of the hole.
For context $18BN Lynas Rare Earths project (which is the highest grade on the ASX) has a resource with an average grade around ~4.1% TREO.
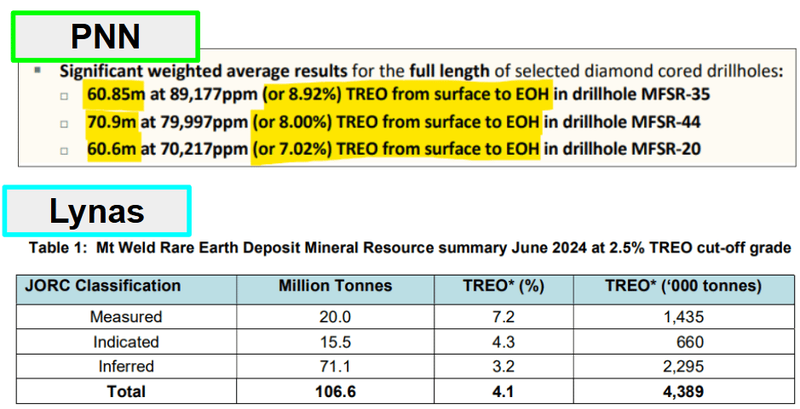
🚨UPDATE:
PNN today hit a subsection of 51m at 15.4% TREO and 2.4% MREO (source) adding to other high grade hits like 53m at 10% TREO and 1.7% MREO (source) and Lynas is now capped at $11BN.
4.The grades are rich in the rare earths that actually matter
PNN’s due diligence confirmed MREO values up to 3.53% of whole rock - and one hole averaged 1.47% MREO over its entire 60.85m length, a higher magnet rare earth grade than the total rare earth grade of many deposits globally.
The four magnet rare earths (MREO) - Nd, Pr, Dy, Tb - account for more than 80% of the market value of all rare earths.
They are the ones that go into humanoid robots, drones, jet fighters, missile guidance systems, naval propulsion, next-gen submarine sonar, AI data storage & displays.
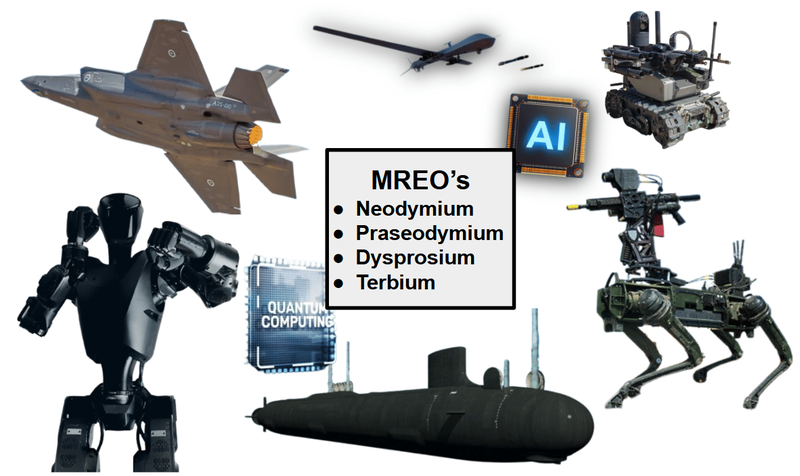
5. PNN’s project has a special type of mining title - “Manifesto de Mina"
A "Manifesto de Mina" is a legacy Brazilian mining title with no expiry date that already grants the right to mine, with only environmental permitting required to move to production. (source)
PNN also owns the freehold land above the deposit, so there are no third-party landholders to negotiate with.
We think the special type of license means IF PNN can define a large enough resource to put the project into production it can get to a decision point a lot quicker than other rare earths projects globally.
6. Geology analogous to the world’s highest grade operating rare earths mine
PNN says that its project's mineralisation is hosted in bastnäsite - the same well-understood mineral processed for decades at MP Materials' ~A$14BN Mountain Pass operation in California.
That gives the metallurgical workstream a meaningfully better starting point than most early-stage rare earths projects.
(source)
7. Next door to two ASX rare earths success stories
Morro do Ferro is in the Poços de Caldas complex alongside the ~$494M capped Meteoric Resources and the ~$463M capped Viridis Mining & Minerals.
PNN is capped at ~$44M.
We think that with some drilling, PNN can close the gap to its neighbours (assuming exploration is successful).
🚨UPDATE: Meteoric just received a $968M takeover from Lynas Rare Earths (based on Lynas’ share price at the time of the offer).
Viridis is capped at $525M, and PNN is capped at $61M:
(source)
8. We have had success Investing in Brazil before
Brazil has an established mining industry - Minas Gerais (the state where PNN’s project sits in) literally translates to "General Mines" - the state was founded on mining and has hosted it for over 300 years.
This is not a frontier jurisdiction. The workforce, the drilling contractors, the labs, the infrastructure and the regulator all exist at scale.
Some of our biggest wins have come from companies with projects in Brazil (both of them also being in Minas Gerais):
- Latin Resources - which made a lithium discovery in Brazil and went from ~3c to a high of ~45c per share - at its peak LRS returned 2332% for us. Eventually the company was taken over by Pilbara Minerals in a deal worth ~$560M.
- St George Mining (ASX: SGQ) - We Invested in SGQ at 2.5c when it first acquired its rare earths project in Brazil. At its peak SGQ was up 620% for us - now it trades at 11c per share - still 340% above our Initial Entry Price.
The past performance of LRS and SGQ is not a reliable indicator of the future performance of PNN.
🚨UPDATE:
SGQ’s share price has come down since we first wrote the above in June 2026. SGQ is now trading at 5.8c/share, 132% above our Initial Entry Price.
9. Brazil matters for US critical minerals independence
China still controls ~90% of the world's rare earth magnet supply chain.
For the heaviest, most valuable rare earths like dysprosium and terbium, China controls ~98-99% of refined supply.
The US is pouring capital into Brazil to try and solve its domestic rare earth supply chain dependency issue.
Brazil is home to the world's second biggest rare earth reserves (behind only China).
The US has so far committed more than US$565M to Brazilian critical minerals projects and just last month US listed USA Rare Earth agreed to a US$2.8BN takeover of a producing rare earths mine in Brazil. (source)
Both of PNN's Brazilian projects sit in states (Minas Gerais and Goiás) that have been in talks to sign critical minerals cooperation agreements with the US. (source)
We think more of these type deals between the US and Brazil are possible for rare earths assets.
10. The "SGQ 2.0" set-up
PNN's deal has a lot of similarities to the deal our Investment SGQ did for its asset in 2024.
SGQ paid a similar amount for its project AND the same corporate advisor behind SGQ is behind PNN.
SGQ re-rated from ~2.5c to a high of 18c and is now capped at ~$435M.
We are hoping some of the capital from people who had a winner with SGQ finds its way into PNN as it proves out its asset.
The past performance of SGQ is not a reliable indicator of the future performance of PNN.
🚨UPDATE:
SGQ’s valuation has come down since we wrote the above in June 2026. At the current 5.8c share price, SGQ’s market cap is $273M.
11. PNN’s project also has ionic clay optionality
Parts of PNN's ground trend toward its neighbours' ionic clay deposits - the style of rare earths mineralisation the ASX understands well with PNN’s two neighbours - $463M Viridis and $494M Meteoric.
IF PNN defines an ionic clay resource on top of its existing discovery then it could all of a sudden draw comparisons to its project and that of Viridis and Meteoric.
🚨UPDATE:
Meteoric just received a $968M takeover from Lynas Rare Earths (based on Lynas’ share price at the time of the offer), Viridis is capped at $525M and PNN is capped at $61M.
What's next for PNN?
🔄 Drill results & maiden JORC resource estimate
Here are the milestones we are tracking:
- ✅ Maiden exploration target
- 🔄 More drilling (currently drilling with two rigs)
- 🔄 Assay results
- 🔄 Metallurgical and mineralogy test work (underway). (source)
- 🔲 Maiden JORC resource estimate (expected in Q4-2026, Q1-2027)
🔲 Ionic clay potential tested at PNN’s project
The "free shot" at the style of deposit that made PNN's neighbours worth a combined ~$1BN.
This one is especially relevant now after the recent news with Lynas’s takeover of Meteoric.
What could go wrong?
The single biggest risk right now is without a doubt “Exploration Risk".
Today's hole is the best we have seen so far.
BUT, most of the drilling PNN’s done is in and around parts of the project that have been drilled before.
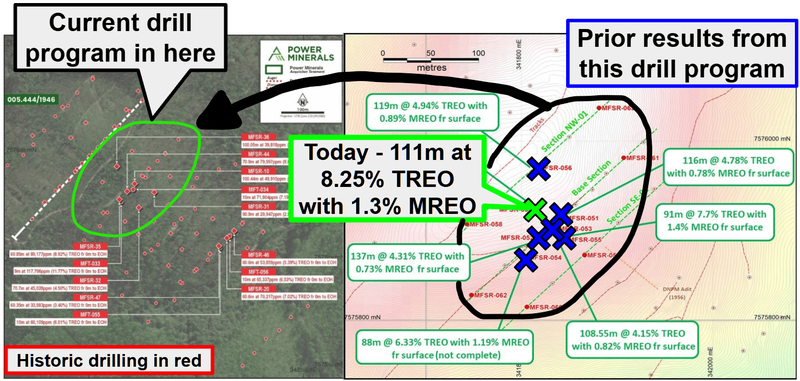
There is always a risk that as PNN starts to step out OR drill a lot deeper, the assays fail to match the expectations that hits like today’s may set.
IF results were to weaken as PNN steps out from areas where it knows there is mineralisation the market may interpret these as exploration failures.
Exploration risk
All of Morro do Ferro's headline grades were drilled by previous owners, mostly in shallow holes. The project has no JORC resource yet. IF PNN's drilling fails to confirm the historic grades, or the deposit doesn't extend, the investment thesis takes a direct hit and we would expect the share price to re-rate lower.
Source: "What could go wrong" - PNN Investment Memo 15 June 2026
Other Risks
Like any early-stage exploration company, PNN carries significant risk, here we aim to identify a few more risks.
Rare earth extraction and processing is notoriously complex, and PNN’s metallurgical test work is still in the early stages. Even with favorable bastnäsite mineralogy, there is no guarantee that commercial recovery rates can be achieved economically at scale.
The project currently relies on an exploration target and historical data rather than a defined JORC resource. If the maiden JORC estimate expected in Q4-2026/Q1-2027 fails to confirm grade continuity or falls short of tonnage expectations, the stock could re-rate lower.
PNN is running two active drill rigs alongside staged acquisition commitments of up to $12M in cash. Funding ongoing exploration and acquisition milestones will require capital, which could mean future capital raises at a discount and dilution for existing shareholders.
While holding a "Manifesto de Mina" removes the need for a standard mining concession grant, full environmental permitting is still required. Environmental licensing in Brazil can involve extensive regulatory scrutiny and unexpected timeline delays.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our PNN Investment Memo
You can read our PNN Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
Our PNN Investment Memo covers:
- What does PNN do?
- The macro theme for PNN
- Our PNN Big Bet
- What we want to see PNN achieve
- Why we are Invested in PNN
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.