PNN’s neighbour gets ~$1BN takeover offer... What now?
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 7,338,223 PNN Shares and 4,399,786 PNN Options at the time of publishing this article. The Company has been engaged by PNN to share our commentary on the progress of our Investment in PNN over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
After threatening a move into Brazil for years...
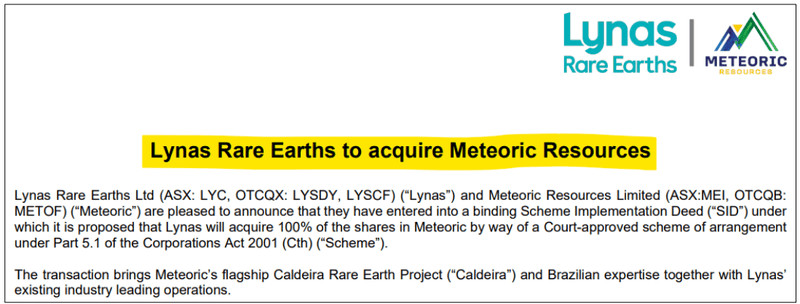
Yesterday the biggest rare earths stock in the western world, the $13BN Lynas Rare Earths, lobbed a $968M takeover offer for Brazilian rare earths developer Meteoric Resources (valuation based on Lynas’ share price at the time of the offer).
(source)
Lynas only has one operating rare earths mine, in Western Australia, and now it is going to Brazil.
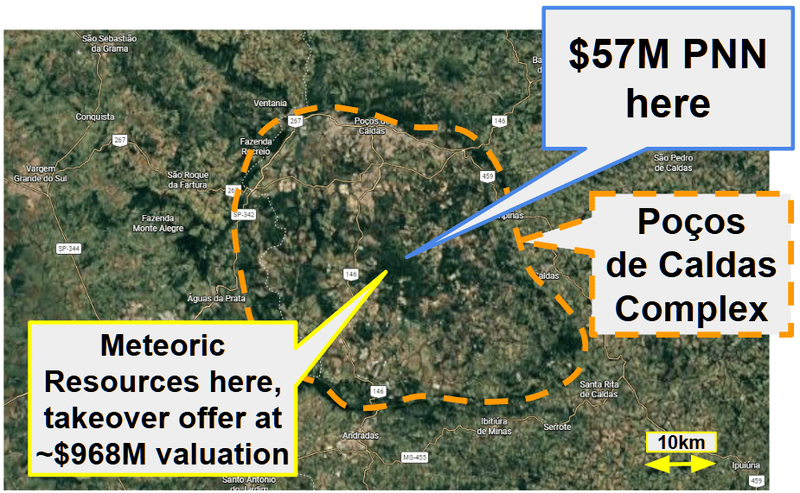
Right next door to our Investment, the $57M capped Power Minerals (ASX:PNN).
PNN and Meterioc sit next door to each other in the same “Poços de Caldas” Complex, in the state of Minas Gerais
(source)
Two rare earths companies right next door to each other, one subject to an almost billion dollar takeover offer, the other less than 1/10th the size.
Meteoric has taken a few years to reach this position.
PNN only in the last few months acquired its asset next door.
Can PNN’s valuation grow closer to Meteoric’s over time as PNN de-risks the asset?
That’s what we are Invested in PNN for.
The main technical difference between the two companies so far is the type of mineralisation on each project.
Meteoric’s is the biggest ionic clay rare earths deposit outside of China.
PNN is progressing with the exploration of the hard rock carbonatite on its ground - the same type of geology as the only two producing rare earth mines in the west.
One being $12BN MP Materials’ project in California.
And... the other - you guessed it - $13BN Lynas Rare Earths producing mine in WA.
So in bidding for Meteoric, Lynas has elected to go after an ionic clay asset, a departure from the hard rock carbonatites it knows so well in WA.
We must admit, we thought Lynas would stick to what it knows and go for an asset with similar geology to its own.
But here we are... $13BN Lynas, right next door to our Investment PNN.
And even though it is not a deal directly with PNN, we think there are three reasons why the deal (if it closes) could be big for PNN:
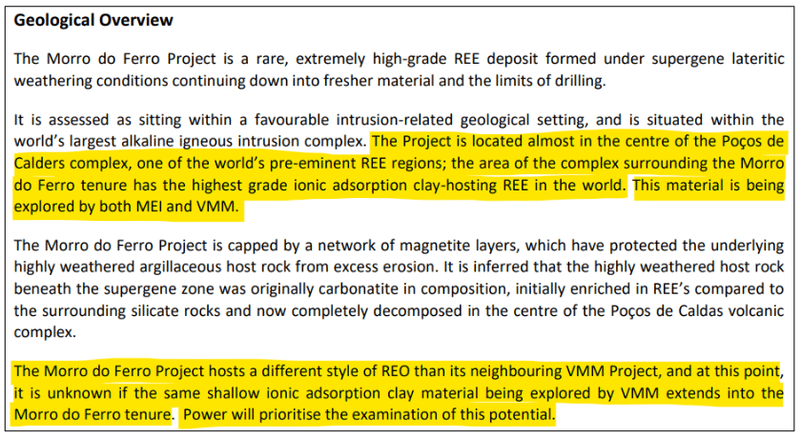
1. PNN has previously mentioned the potential for ionic clay mineralisation on its project and that it would be something it looks at after drilling out the high grade hard rock mineralisation.
(source)
2. PNN’s asset could now become an obvious hard rock carbonatite acquisition target for Lynas (post swallowing Meteoric) - Lynas has now made a commitment to the region (and might want to bolt on to whatever its plans are for the area’s geology it knows and understands).
3. And finally, because we think PNN’s already working toward what looks like it could be an interesting very high grade (albeit relatively small... for now) hard rock rare earths JORC resource estimate.
We think that when PNN defines a JORC resource estimate of its own, it could start to attract interest from investors looking to recycle some of their wins from Meteoric into another company in this part of Brazil.
(Nothing like a winner in your portfolio to think you are a genius at investing in that sector and region)
PNN also following in the footsteps of the $1BN Brazilian Rare Earths
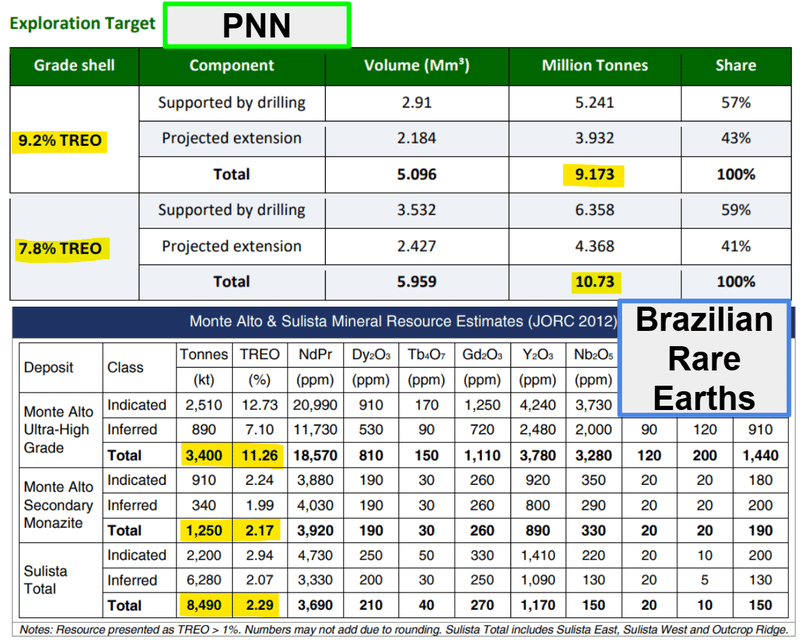
The other case for PNN is that there is already a live peer comparison on the ASX that has a JORC resource similar to PNN’s current 9.2 to 10.7Mt at 7.8% to 9.2% TREO exploration target.
The upper end of PNN’s exploration target (5Mt at 9.2% TREO) is very similar to that of ~$1BN capped Brazilian Rare Earths whose project has a 3.4Mt at 11.26% TREO resource.
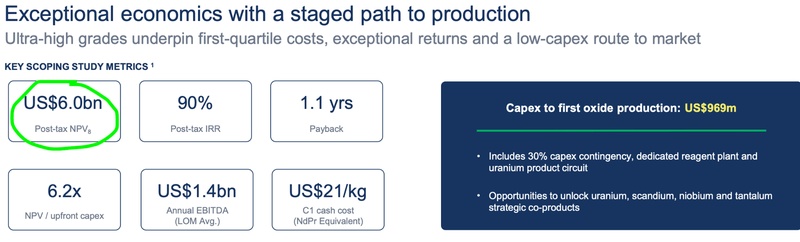
Brazilian Rare Earths project also has a Scoping Study on its project which shows a Net Present Value of ~US$6BN:
(a massive NPV is a nice way of underscoring just how important those high grades are... )
(source)
Here is how Brazilian Rare Earths resource estimate compares to PNN’s exploration target:
🎥 Watch PNN’s CEO/MD and Exploration Manager talk through the Exploration target here.
PNN is aiming to release a JORC resource estimate for its project either this quarter or next.
So within the next 6 months, ASX investors will be able to start drawing pretty direct comparisons between PNN and Brazilian Rare Earths.
AND any corporates looking for action in this part of Brazil, will have a well understood geology type with a very high grade resource in the area.
Between now and then, we have all of the newsflow from drilling to come...
PNN is drilling its project right now with two rigs
PNN is currently 18 holes into its drill campaign, drilling with two rigs.
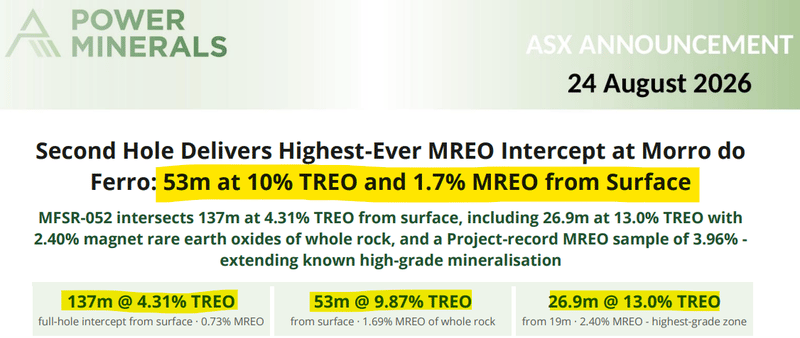
So far we have seen some pretty incredible hits - results like 53m at 10% TREO and 1.7% MREO:
(source: PNN announcement)
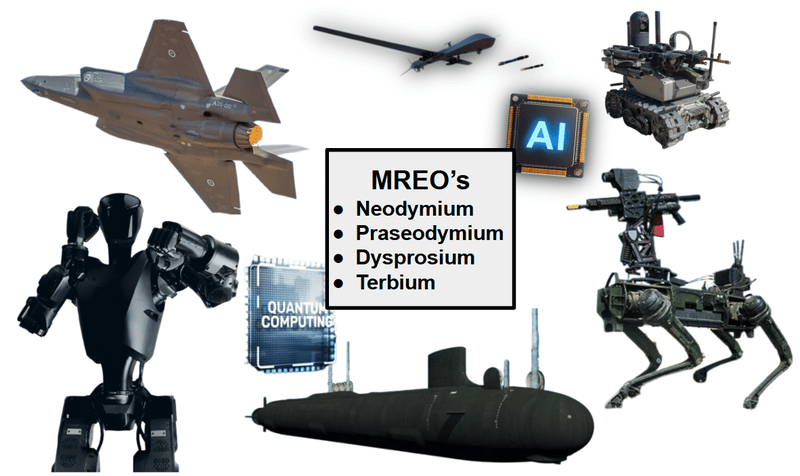
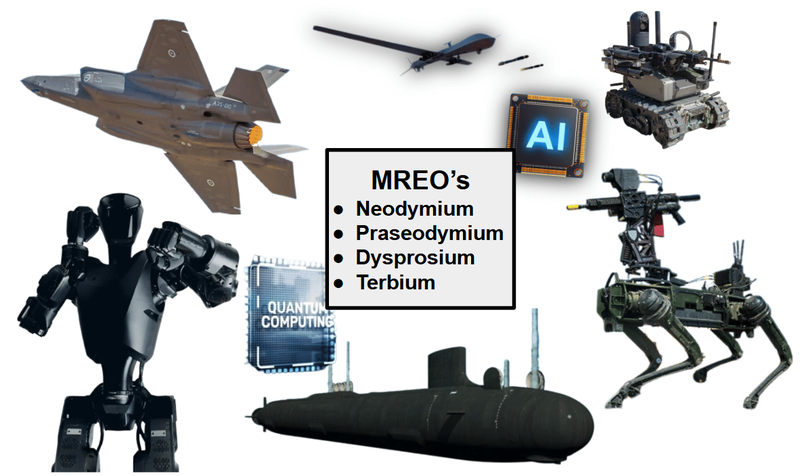
Those MREO (Magnetic Rare Earth Oxides) grades are especially interesting because they are the high value rare earths that go into robotics, EVs, military hardware and more, like in these:
Until a few weeks back, our understanding of PNN’s project was that it was really high grade starting from surface down to ~100-150m depths:
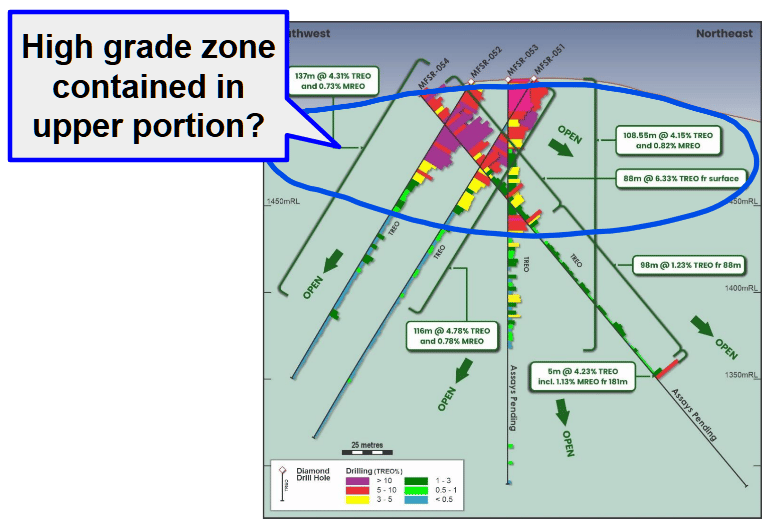
(source)
But then PNN released partial assays from its fourth hole which ended in mineralisation - 5m at 4.32% TREO with 1.13% MREO at depths of ~181m:
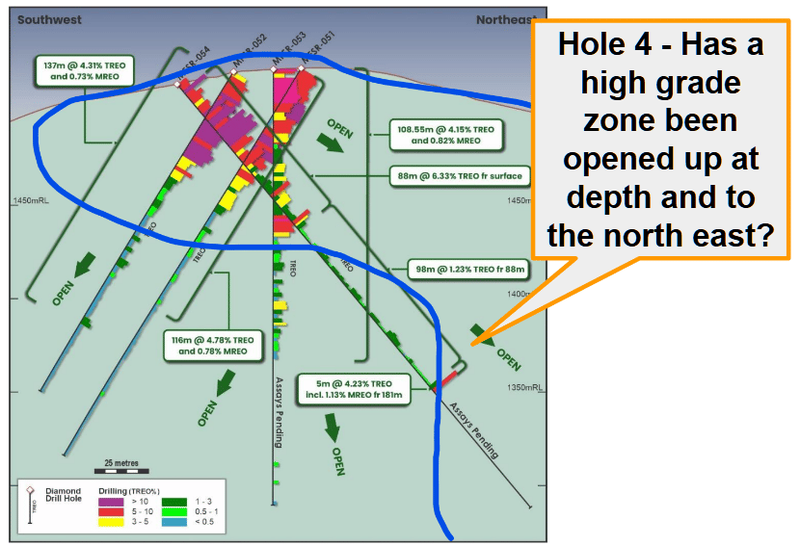
(source)
Assays are now pending for the rest of that hole - if those assays also come back with high grade mineralisation, it could change the size/scale potential of PNN’s project.
PNN’s last announcement said those assays “will be progressively released as they become available” (source), so we could see assays any day.
The western rare earths problem still hasn’t been resolved either
The big rare earth elephant in the room is still there for western supply chains.
China still controls ~90% of the world's rare earth magnet supply chain. (source)
For the heaviest, most valuable rare earths like dysprosium and terbium, China controls ~98-99% of refined supply. (source)
China announced these export restrictions in April 2025 (in response to Trump’s tariff threats). (source)
Then momentarily paused while China and the US worked on a deal (that pause was extended by 2 months just last week, it was due to expire November 10 - source).
Right now dysprosium and terbium (two of PNN's four magnet metals) still need case-by-case export licences out of China.
And a few months ago, China banned exports of “dual-use items” to US defence contractors including two US rare earths companies:
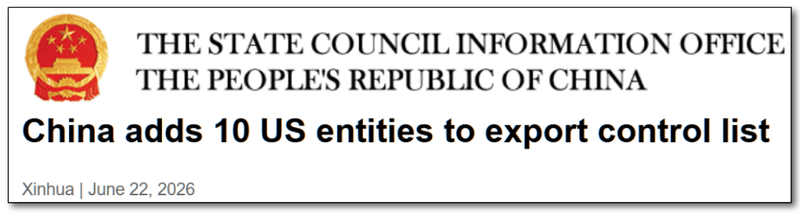
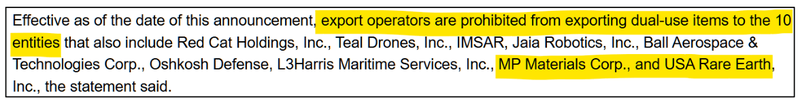
(source)
Rare earths are considered “dual-use” items:
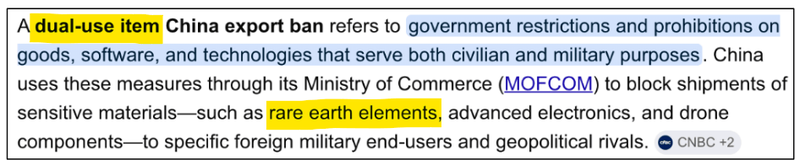
(source - we google’d dual-use item China ban)
So while the official export ban hasn’t really kicked into place, China has maintained its right to stop any export at any time whenever it sees fit.
Enter Brazil... as an alternative to Chinese rare earth supply for the USA
Brazil is home to the world's second biggest rare earth reserves (behind only China). (source)
Below is an article specifically highlighting the region that PNN’s project sits in as a rare earth hotspot inside Brazil, the Wall Street Journal calling it the "new front" for rare earths:
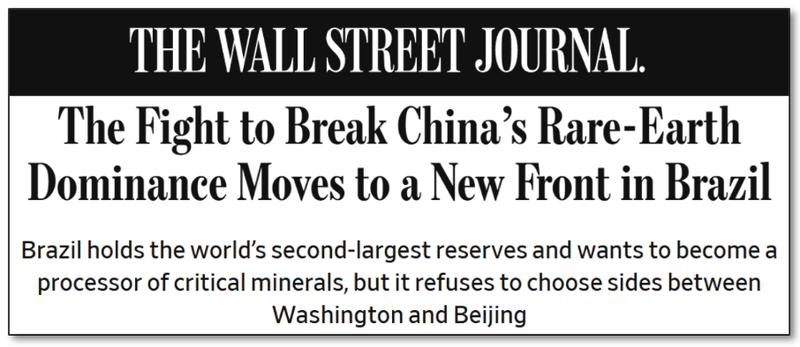
(source)
There is also US corporate precedent for interest in Brazilian assets:
- The US$2.8BN USA Rare Earth's takeover of Serra Verde - the only large-scale producer outside Asia producing rare earths from ionic clays. The deal comes with a 15-year US government supply agreement including a price floor. (source)
- A US$250M letter of interest from the Export-Import Bank of the United States (EXIM) to PNN's next door neighbour Meteoric Resources for its Caldeira project. (source)
- And then yesterday, the takeover offer from Lynas for Meteorics project next door to PNN. (source)
Even the EU is looking to do a Brazil minerals deal:
(source)
The positives from all of this is that PNN now has an asset where western capital is comfortable going to AND there are benchmarks being set for the type of prices that need to be paid to get deals done.
Ultimately, we are hoping that as PNN progresses its project, it attracts some sort of strategic/corporate interest and delivers our Big Bet as follows:
Our PNN Big Bet:
"PNN proves up a major high-grade rare earths resource in Brazil and re-rates 1,000% from our Initial Entry Price - via development, strategic investment or acquisition"
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our PNN Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
Power Minerals
11 reasons why we are Invested in PNN
Here are the reasons we set out as part of our new PNN Investment Memo on the 15th of June 2026. Read that full article here.
We have added some minor updates to the reasons where necessary.
1. Rare earths as an exposure to AI and Robotics
Rare earths are a group of 17 metals, a small group of them - neodymium, praseodymium, dysprosium and terbium - are used to make the strongest permanent magnets on earth.
Those magnets are in EV motors, wind turbines, robots, drones, fighter jets, guided missiles, smartphones and the cooling systems of AI data centres.
There are no commercial substitutes.
An F-35 contains ~400kg of rare earth materials. A single EV uses 1-2kg of rare earth magnets. A humanoid robot is expected to use more.
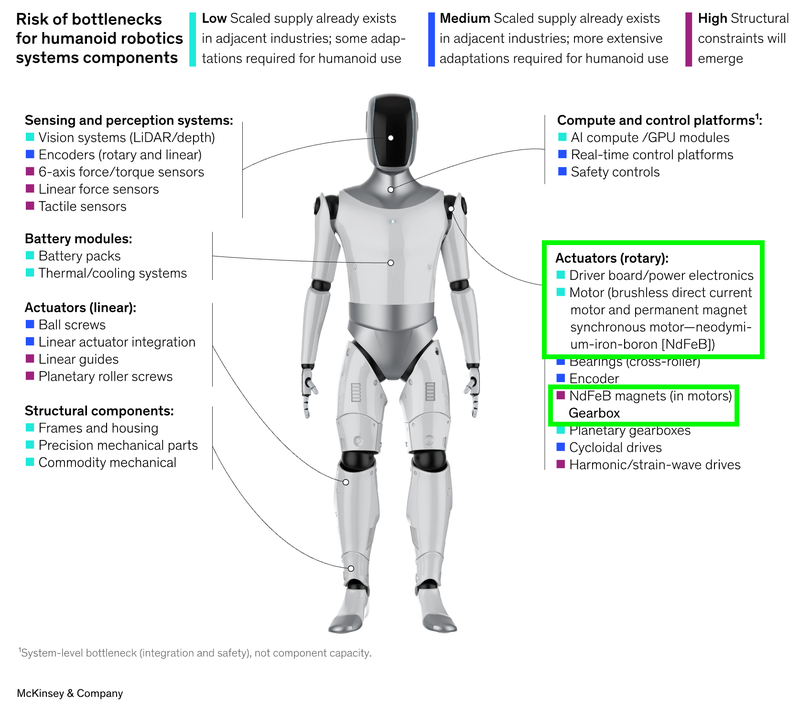
(source)
2. PNN's project is advanced stage (an existing discovery)
PNN’s project has passed the early exploration stage with ~156 holes drilled into it.
The asset has already had 50 drill holes for a total of over 4,000m of diamond core drilling AND 106 holes for a total of 846.5m of auger drilling.
The existing discovery de-risks the asset from an exploration perspective and gives PNN something to expand.
🚨UPDATE: PNN is active on the drilling front now, and continues to release assay results.
3. PNN’s project has some of the highest rare earth grades we have seen on the ASX
Historic drilling at Morro do Ferro returned 60.85m at 8.92% TREO, 70.9m at 8.00% TREO and 100.44m at 4.99% TREO - all from surface to the end of the hole.
For context $18BN Lynas Rare Earths project (which is the highest grade on the ASX) has a resource with an average grade around ~4.1% TREO.
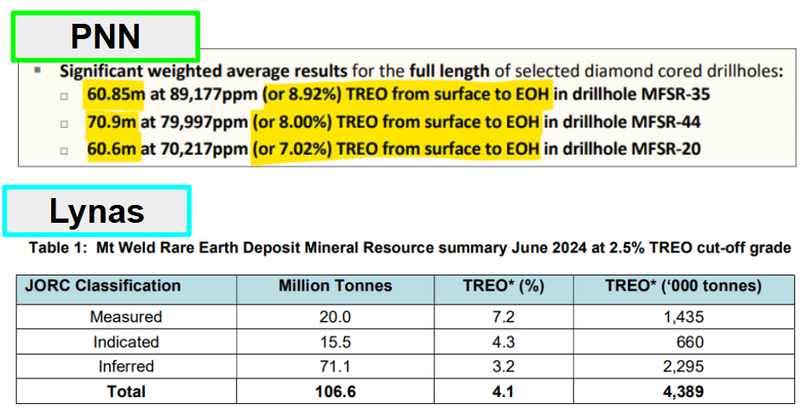
🚨UPDATE: PNN has since hit even higher grade hits like 53m at 10% TREO and 1.7% MREO (source) and LYC is now capped at $13BN.
4. The grades are rich in the rare earths that actually matter
PNN’s due diligence confirmed MREO values up to 3.53% of whole rock - and one hole averaged 1.47% MREO over its entire 60.85m length, a higher magnet rare earth grade than the total rare earth grade of many deposits globally.
The four magnet rare earths (MREO) - Nd, Pr, Dy, Tb - account for more than 80% of the market value of all rare earths.
They are the ones that go into humanoid robots, drones, jet fighters, missile guidance systems, naval propulsion, next-gen submarine sonar, AI data storage & displays.
5. PNN’s project has a special type of mining title - “Manifesto de Mina"
A "Manifesto de Mina" is a legacy Brazilian mining title with no expiry date that already grants the right to mine, with only environmental permitting required to move to production. (source)
PNN also owns the freehold land above the deposit, so there are no third-party landholders to negotiate with.
We think the special type of license means IF PNN can define a large enough resource to put the project into production it can get to a decision point a lot quicker than other rare earths projects globally.
6. Geology analogous to the world’s highest grade operating rare earths mine
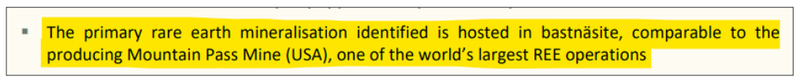
PNN says that its project's mineralisation is hosted in bastnäsite - the same well-understood mineral processed for decades at MP Materials' ~A$14BN Mountain Pass operation in California.
That gives the metallurgical workstream a meaningfully better starting point than most early-stage rare earths projects.
(source)
7. Next door to two ASX rare earths success stories
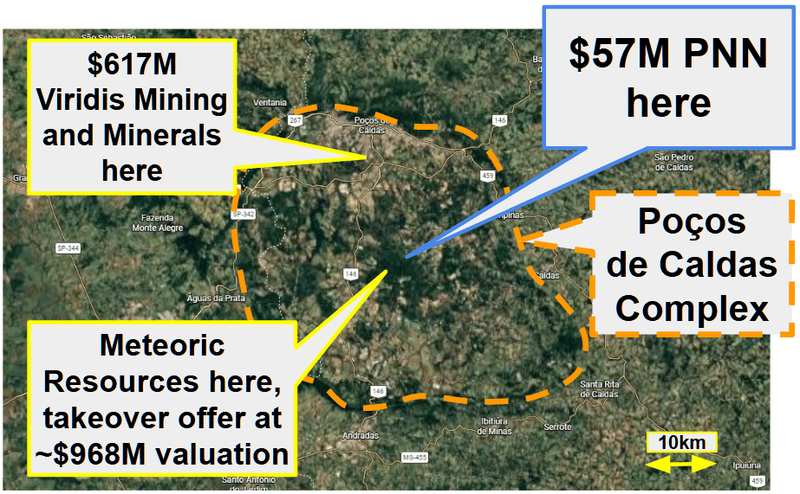
Morro do Ferro is in the Poços de Caldas complex alongside the ~$494M capped Meteoric Resources and the ~$463M capped Viridis Mining & Minerals.
PNN is capped at ~$44M.
We think that with some drilling, PNN can close the gap to its neighbours (assuming exploration is successful).
🚨UPDATE: Meteoric just received a $968M takeover from Lynas Rare Earths (based on Lynas’ share price at the time of the offer).
Viridis is capped at $617N, and PNN is capped at $57M:
(source)
8. We have had success Investing in Brazil before
Brazil has an established mining industry - Minas Gerais (the state where PNN’s project sits in) literally translates to "General Mines" - the state was founded on mining and has hosted it for over 300 years.
This is not a frontier jurisdiction. The workforce, the drilling contractors, the labs, the infrastructure and the regulator all exist at scale.
Some of our biggest wins have come from companies with projects in Brazil (both of them also being in Minas Gerais):
- Latin Resources - which made a lithium discovery in Brazil and went from ~3c to a high of ~45c per share - at its peak LRS returned 2332% for us. Eventually the company was taken over by Pilbara Minerals in a deal worth ~$560M.
- St George Mining (ASX: SGQ) - We Invested in SGQ at 2.5c when it first acquired its rare earths project in Brazil. At its peak SGQ was up 620% for us - now it trades at 11c per share - still 340% above our Initial Entry Price.
The past performance of LRS and SGQ is not a reliable indicator of the future performance of PNN.
9. Brazil matters for US critical minerals independence
China still controls ~90% of the world's rare earth magnet supply chain.
For the heaviest, most valuable rare earths like dysprosium and terbium, China controls ~98-99% of refined supply.
The US is pouring capital into Brazil to try and solve its domestic rare earth supply chain dependency issue.
Brazil is home to the world's second biggest rare earth reserves (behind only China).
So far committed more than US$565M to Brazilian critical minerals projects and just last month US listed USA Rare Earths agreed to a US$2.8BN takeover of a producing rare earths mine in Brazil. (source)
Both of PNN's Brazilian projects sit in states (Minas Gerais and Goiás) that have been in talks to sign critical minerals cooperation agreements with the US. (source)
We think more of these type deals between the US and Brazil are possible for rare earths assets.
10. The "SGQ 2.0" set-up
PNN's deal has a lot of similarities to the deal our Investment SGQ did for its asset in 2024.
SGQ paid a similar amount for its project AND the same corporate advisor behind SGQ is behind PNN.
SGQ re-rated from ~2.5c to a high of 18c and is now capped at ~$435M.
We are hoping some of the capital from people who had a winner with SGQ finds its way into PNN as it proves out its asset.
The past performance of SGQ is not a reliable indicator of the future performance of PNN.
11. PNN’s project also has ionic clay optionality
Parts of PNN's ground trend toward its neighbours' ionic clay deposits - the style of rare earths mineralisation the ASX understands well with PNN’s two neighbours - $463M Viridis and $494M Meteoric.
IF PNN defines an ionic clay resource on top of its existing discovery then it could all of a sudden draw comparisons to its project and that of Viridis and Meteoric.
🚨UPDATE: Meteoric just received a $968M takeover from Lynas Rare Earths (based on Lynas’ share price at the time of the offer), Viridis is capped at $617M and PNN is capped at $57M.
What's next for PNN?
🔄 Results from current drill program
Here are the milestones we are tracking:
- 🔄 More drilling (two rigs currently drilling through to December)
- 🔄 Assay results (partial assays remain from holes 3 & 4, plus the next 14 holes). (source)
- 🔄 Metallurgical test work drilling (samples have been sent for testing. (source)
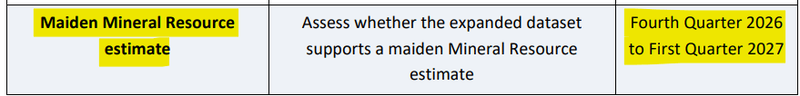
🔲 Maiden JORC resource estimate
Expected Q4 26/Q1 27 (should the drilling data allow it) - this is the big one for us.
(source)
🔲 Ionic clay potential tested at Morro do Ferro (MDF)
The "free shot" at the style of deposit that made PNN's neighbours worth a combined ~$1BN.
This one is especially relevant now after yesterday’s news with Lynas’s takeover of Meteoric.
What could go wrong?
One of the biggest risks right now is “exploration risk”.
The results so far are a strong start, but it's only 4 assays (including partial holes) into PNN’s drill program.
There is always a risk that the remaining holes in PNN’s drill program come in below market expectations.
Exploration risk
All of Morro do Ferro's headline grades were drilled by previous owners, mostly in shallow holes. The project has no JORC resource yet. IF PNN's drilling fails to confirm the historic grades, or the deposit doesn't extend, the investment thesis takes a direct hit and we would expect the share price to re-rate lower.
Source: “What could go wrong” - PNN Investment Memo 15 June 2026
Other Risks
Like any early-stage exploration company, PNN carries significant risk, here we aim to identify a few more risks.
Rare earth prices and supply-chain geopolitics are highly volatile and heavily influenced by government policy changes in China and the US. Any unexpected shift in trade restrictions or commodity pricing could negatively impact the commercial value of PNN’s deposit.
While hard rock carbonatite mineralisation is well understood globally, commercial extraction depends entirely on achieving viable metallurgical recovery rates. If upcoming processing test work returns lower recovery rates than expected, the overall economics of the project would take a hit.
PNN is currently funding an active two-rig drilling campaign that burns through substantial capital. To complete planned exploration and deliver a maiden JORC resource, the company may need to raise additional capital, creating potential dilution for existing shareholders.
Even with the advantages of the "Manifesto de Mina" title, full environmental permits and regulatory sign-offs are still required before any mining can take place. Any unforeseen environmental hurdles or regulatory delays could push back project timelines significantly.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our PNN Investment Memo
You can read our PNN Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
Our PNN Investment Memo covers:
- What does PNN do?
- The macro theme for PNN
- Our PNN Big Bet
- What we want to see PNN achieve
- Why we are Invested in PNN
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.