MNB: Commences early stage mining of phosphate rock
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 42,049,459 MNB Shares and 39,378,833 MNB Options. Some Shares and Options are subject to shareholder approval. The Company has been engaged by MNB to share our commentary on the progress of our Investment in MNB over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
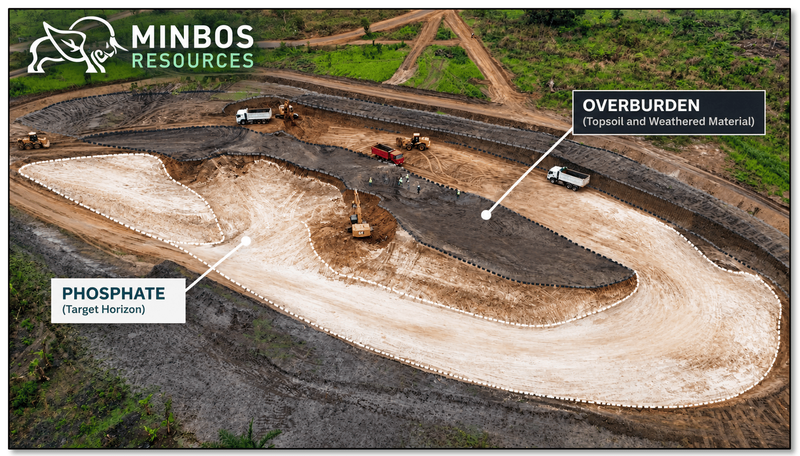
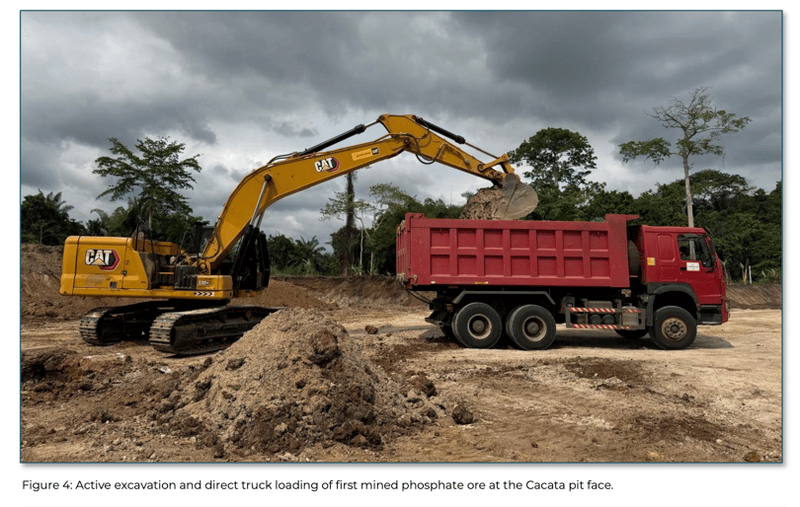
This morning, our Investment Minbos Resources (ASX:MNB) said it has commenced early stage mining operations - now mining phosphate rock at its project in Angola.
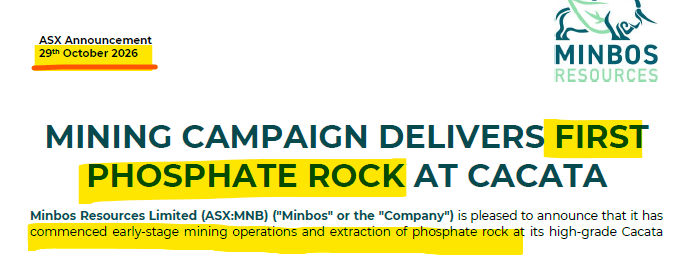
(read the announcement here)
We have also been shown over the last few weeks some serious progress on their phosphate processing plant construction:
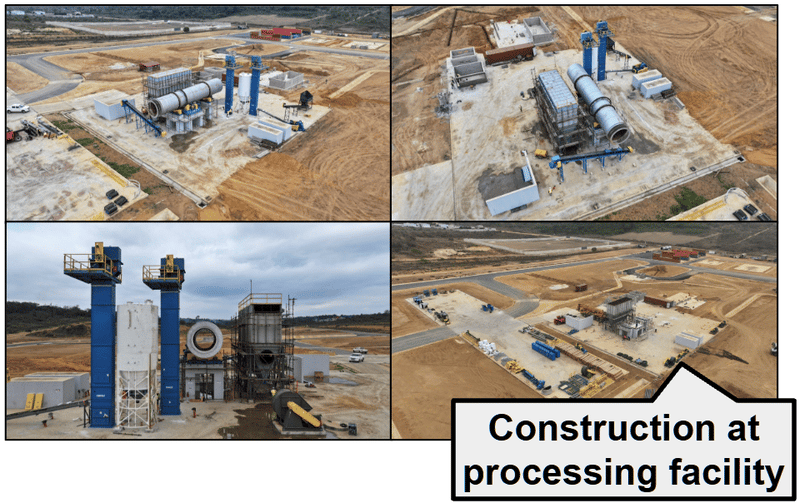
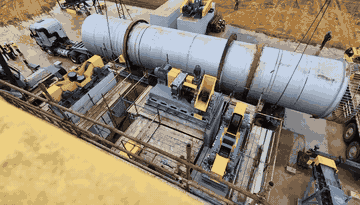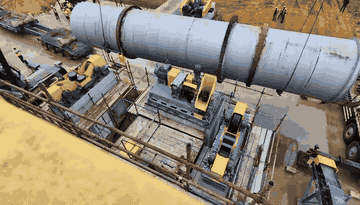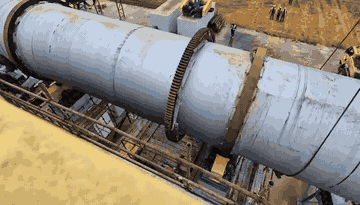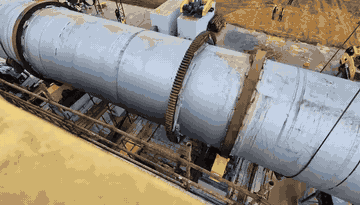
(read our commentary on the plant build from last week here)
MNB is starting to stockpile ore ahead of its plant being constructed and commissioning, which is planned for Q2 2027.
MNB has a Ministerial site visit scheduled for December - when Angolan government representatives are expected to “inspect the completed plant structures”. (source - 29 July project update)
So there is a soft deadline to at least have the processing plant put together by then.
Meaning we COULD now be just a few months away from MNB producing its first sack of phosphate fertiliser.
A project that according to MNB's 2022 Definitive Feasibility Study was supposed to generate ~US$55M in EBITDA per year over a 20 year mine life, with a post-tax NPV of US$203M. (source)
And potentially US$399M NPV using today’s input prices - more on that later in today’s note.
Note however since that study was completed 4 years ago, MNB’s plan did change, including a simplified plant flowsheet in late 2025, a number of assumptions could also be out of date, we would expect these numbers would look different by now. We only use the study as a basis for what the project economics could look like.
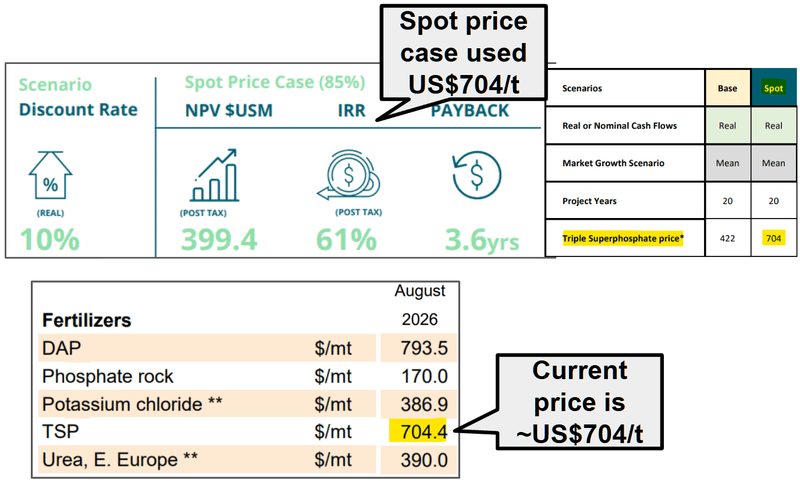
According to today's announcement, mining has already started, and soon the plant will have stockpiles that can go straight into it.
$55M/year EBITDA when built? Phosphate prices at highs? Photos of processing plant almost built last week? Photos of mining commenced today?
So why is MNB’s market cap ~$24M (at 1.5c per share)?
MNB’s share price has been a lot higher in the past, based on the market believing they could build this project.
But after too many broken promises on timelines to build and mine, the market stopped believing MNB and here we are at 1.5c.
We think that if MNB actually delivers it this time (so far so good over the last two weeks), the share price will hopefully snap back as the market starts believing MNB will get it built and start producing and selling phosphate.
(no guarantees of course, mining developments are risky and anything can happen)
We ALSO want to see MNB deliver the final two things outstanding that are in the way of MNB completing its mine build, commissioning it, and commencing phosphate sales.
Here’s the latest on progress on these two final things:
From today’s MNB announcement License transfers: “Administrative processes regarding operational instruments and title transfer procedures are progressing with the regulators, ensuring alignment between government stakeholders, local communities, and the Company’s operational schedule.” (source)
BFA Funding: This is a key priority for MNB, in the last quarterly report the company said issuance of the FGC guarantee is expected to assist with BFA funding and an initial drawdown of approx US$1.3M (source)
The last full detailed update on BFA funding was in MNB’s 2nd September announcement.
MNB needs to secure access to the BFA funding required to finish construction AND obtain formal sign-off from Angolan authorities on the outstanding licence transfers and operational approvals.
And we are hoping for a decent snap back on the Lassonde curve theory, given how big MNB’s second wave dip has been.
After a few shaky years sitting in the “feasibility/development” trough of the Lassonde Curve - it looks like over the next 3-6 months, MNB could start "operating" its mine.
For anyone who doesn’t know the Lassonde Curve - it’s a generalised pattern a mining stock’s share price follows over the life of a project:
- A run on discovery,
- A long drift lower through the “boring” years of studies, permits, financing and construction
- Then (hopefully) a second leg up once the mine is producing and cash is coming in.
MNB has spent four years in that “drift lower” phase - longer than we (and the rest of the market) would have liked, but it's behind the company now.
Not to mention MNB dipped hard after many broken timelines for construction and mining to start.
Here is where we think MNB is on the Lassonde Curve:
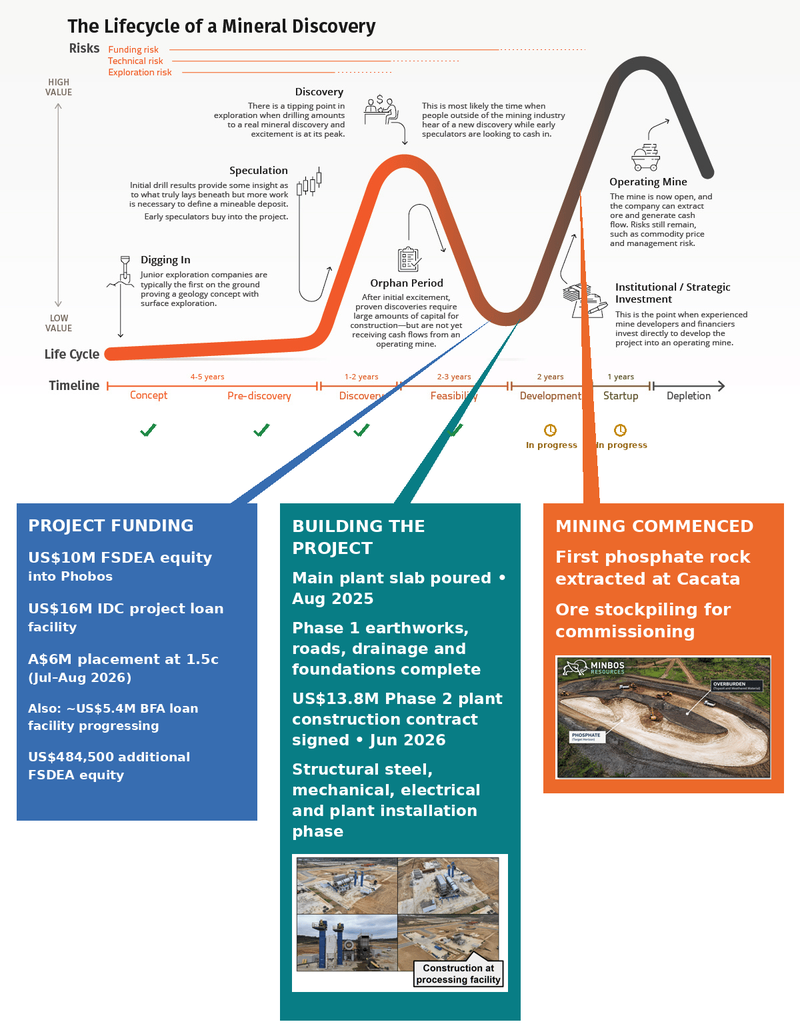
Despite the (slow) but steady transition toward becoming a producer.
AND the mining/processing plant progress.
As we said above, we think MNB’s share price is where it is today (around all time lows) because the market lost trust in MNB’s ability to deliver things when guided.
But today’s update is starting to make us think things are changing for MNB.
(after last weeks update showing how much progress has been made building their processing plant - read our update on that here)
And the company is starting to build up a little bit of momentum...
MNB upsized the recent raise to $6M in August at 1.5c and at the time had said - "grade control, mine mobilisation and commencement of mining". (source)
Less than 3 months in and MNB has mobilised to the mine, commenced mining AND is doing grade control from the mined material right now.
(Hopefully the first of many delivered timelines - which helps MNB regain the market’s trust)
We think there is a good chance MNB can hit its next batch of major catalysts too - including:
- Commissioning its processing plant (Q2-2027) - MNB is already mining so that could become feedstock sitting on site that can be taken straight to the plant when it's constructed.
- Fully completed processing plant (hopefully by December) - Surely MNB will push as hard as it can to have that plant built and ready when the ministerial site visit happens in December 2026. (this would de-risk point #1)
- MNB gets to first revenues even before that Q2-2027 date - this would be under the HOA MNB signed with Fertiafrica to sell unprocessed rock - so we could see first revenues pretty soon too. (source)
IF/when all three happen, MNB completes that explorer/developer to producer transition.
And along the way selling the unprocessed rock would (by a technicality) mean MNB officially generates its first revenues (before the plant is commissioned).
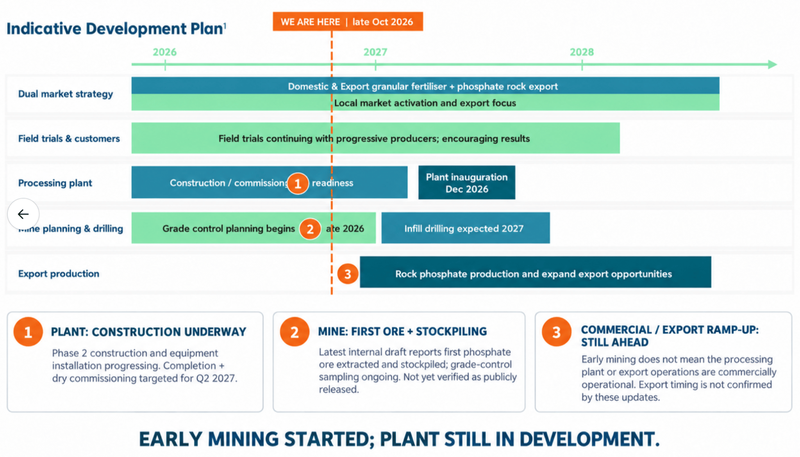
(source)
How we got here (the short version)
We have been Invested in MNB for six years.
(at 3c, 8c, 11c, 7c, 2.6c and most recently 1.5c)
We Invested to see them build a phosphate (fertiliser) mine and processing plant in Angola.
For a few years in a row the company signalled "financing almost secured" and "about to build"...
The build didn't happen on time, the market stopped trusting what MNB promised = share price went down a lot.
Then over the last three months the plant site went from a bare slab to a rotary dryer, silos and structural steel going up - here are the before and after photos:
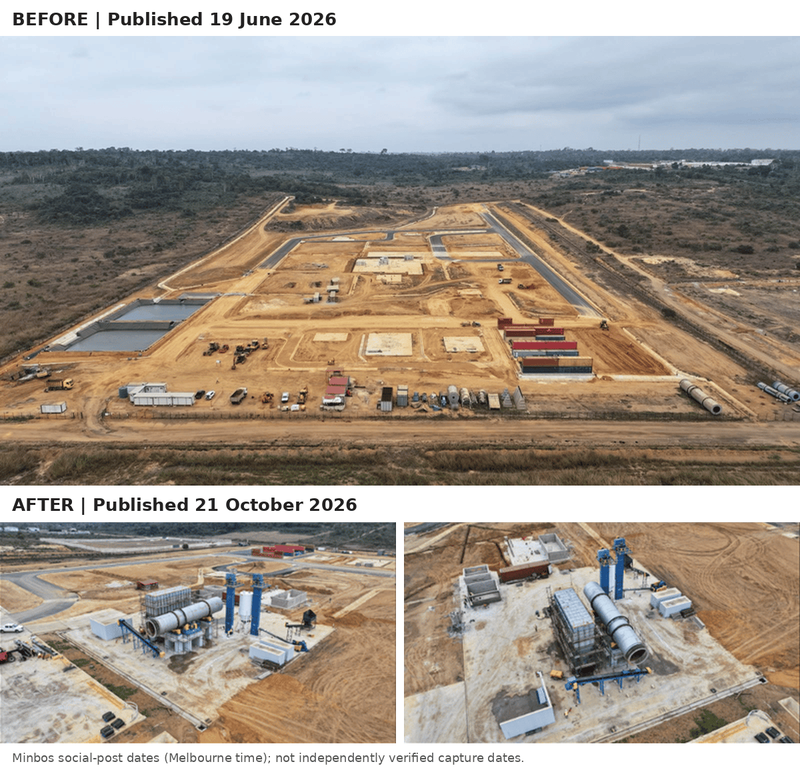
As of this morning, MNB’s also confirmed that mining operations are underway too...
As mentioned earlier, MNB is now a few months from having its mine and processing plant up and running in unison.
Once in production, MNB will own Angola's first and only integrated phosphate mine and fertiliser plant.
A project that according to MNB's 2022 Definitive Feasibility Study was supposed to generate ~US$55M in EBITDA per year over a 20 year mine life, with a post-tax NPV of US$203M. (source)
In a nice stroke of luck for MNB (for once), the TSP (triple superphosphate) price has been trading around MNB’s "spot case" scenario from that DFS back in 2022 - averaging ~US$705 per tonne in the September quarter. (source)
Using the spot-case had the project generating US$95M EBITDA per year and a post-tax NPV of US$399M. (source)
However, we note that MNB’s development plan has changed since that study - MNB simplified the plant flowsheet in late 2025 - so these numbers could be different now.
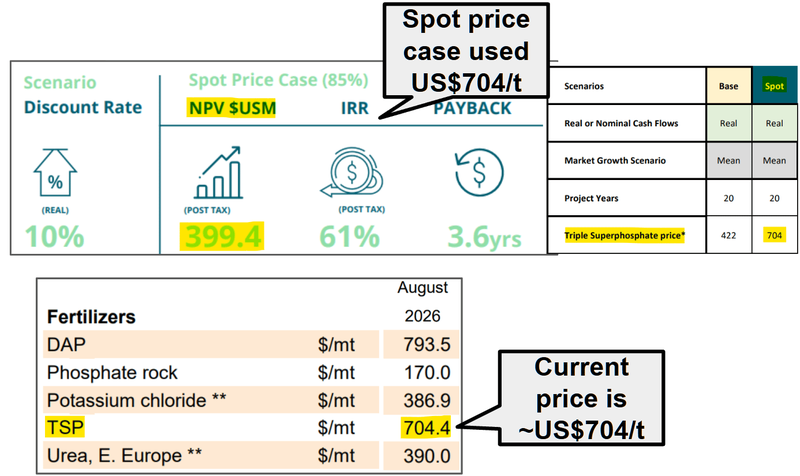
So somehow, with the delays, MNB might be coming into production into a strong pricing environment...
(a rare bit of luck for MNB... for a change)
And just as the macro investment environment for phosphate/fertiliser has turned in MNB's favour (mainly because of the war in the Middle East).
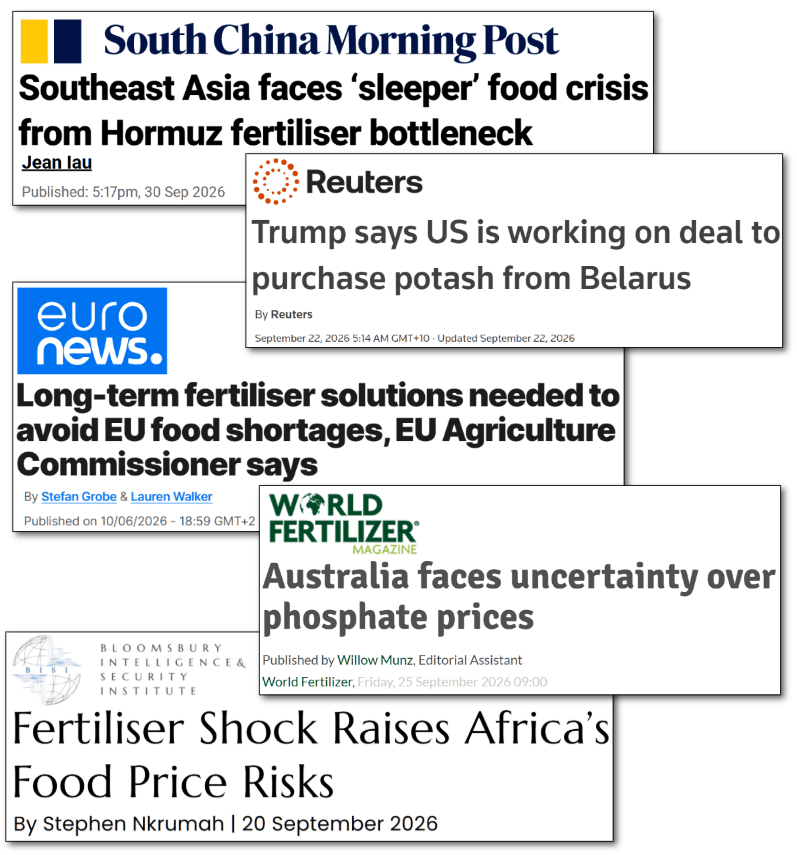
(source)(source)(source)(source)(source)
A big part of our MNB thesis is the "food security" macro - the idea that governments would eventually start treating fertiliser like a strategic resource.
We had expected this to come from mainly within Africa, which has well documented food security issues over many decades.
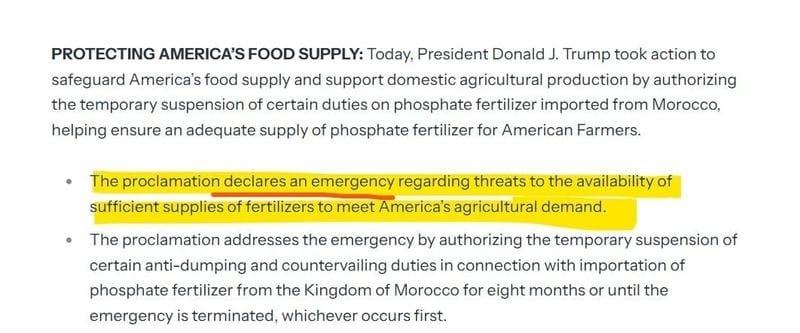
But then on the 29th of June, President Trump signed the following Executive Order, declaring:
"an emergency regarding threats to availability of sufficient supplies of fertilizers to meet America's agricultural demand".
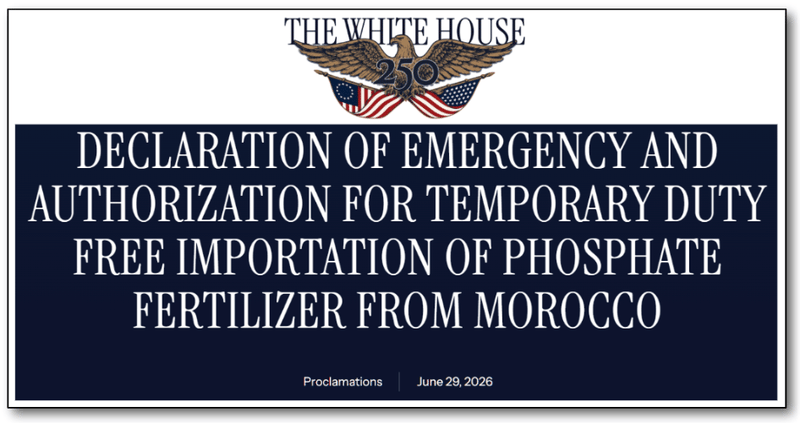
(source)
The US cutting duties on Moroccan phosphate makes two things clear, both of which are clearly outlined in the Executive Order.
- Firstly, domestic production is not enough to cover what American farmers need.
- Secondly, the US is willing to look toward Africa for phosphate supply in the meantime.
The Strait of Hormuz situation doesn't look like it's going to get resolved any time soon.
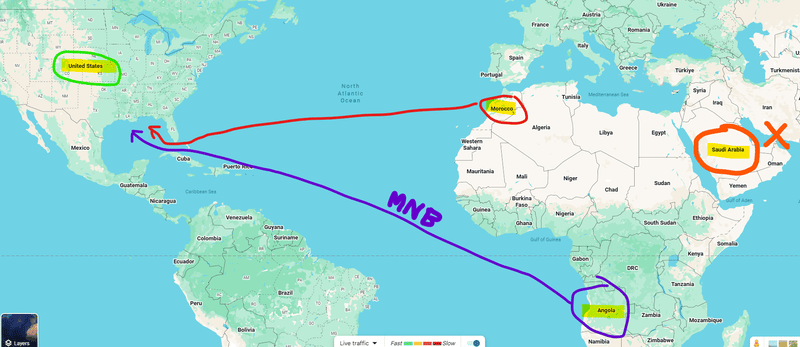
Saudi Arabia's Ma'aden's Ras Al-Khair complex (one of the world's biggest integrated phosphate operations) sits on the Gulf coast - every export cargo must transit Hormuz, no workaround.
Unlike USA's newly crowned phosphate best mate Morocco on the West African coast, which has a clear, Houthi free, Atlantic Ocean run to the USA.
MNB's phosphate fertiliser project is in Angola, also on the West African coast which has the same clear run to the same ports in the USA:
And it's not just the US looking for fertiliser solutions - the EU Agriculture Commissioner is calling for "long-term fertiliser solutions" to avoid food shortages in Europe. (source)
Why does all this matter to MNB?
Because MNB's go to market strategy for its product is to sell locally into the Angolan market AND sell product into the export market.
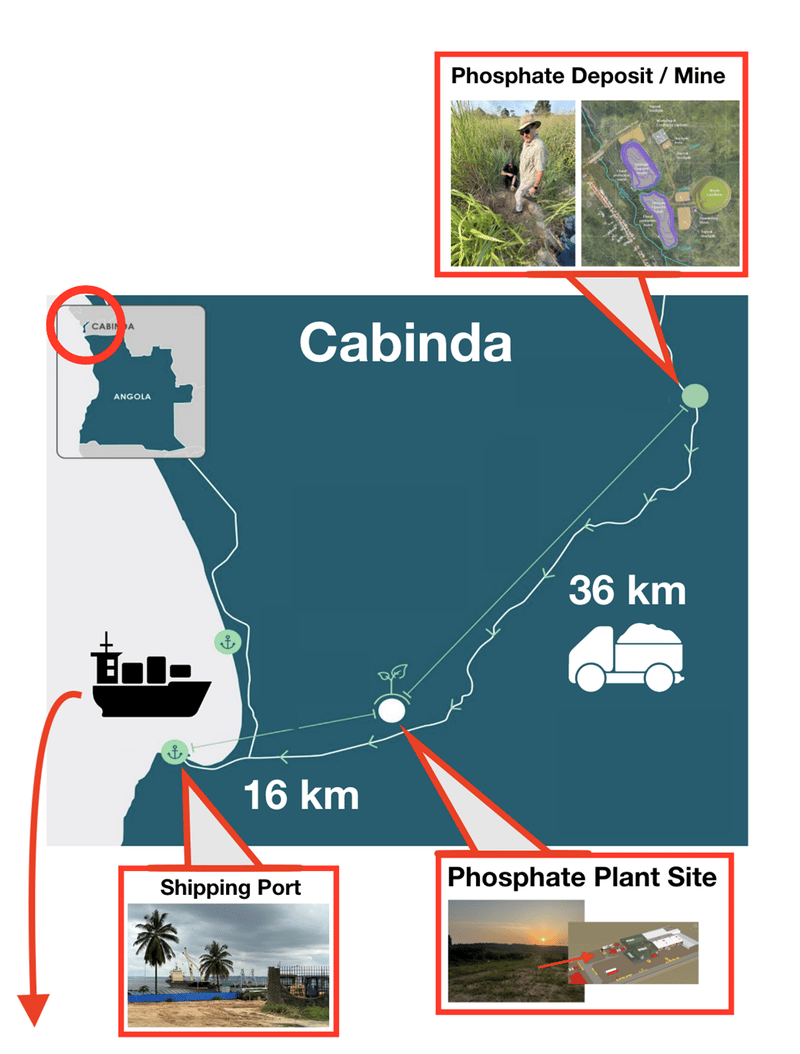
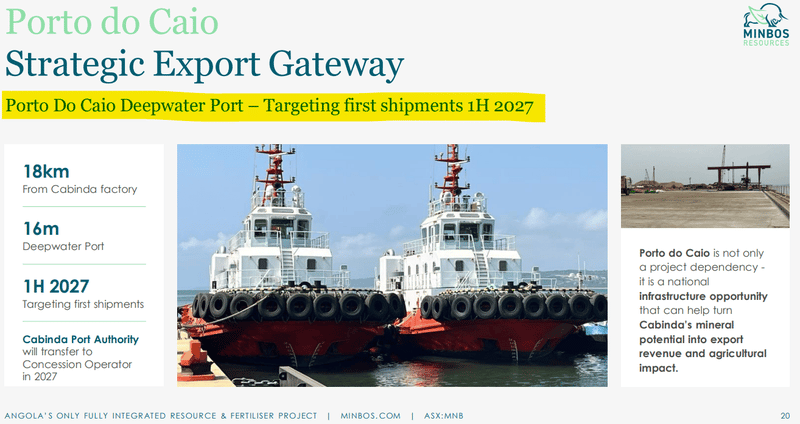
MNB expects to be shipping export product through the Porto do Caio deepwater port in H1 2027:
(source)
The port is ~79% complete and its inauguration is expected by the end of this year. (source)
(we saw it being built on our 2023 site visit)
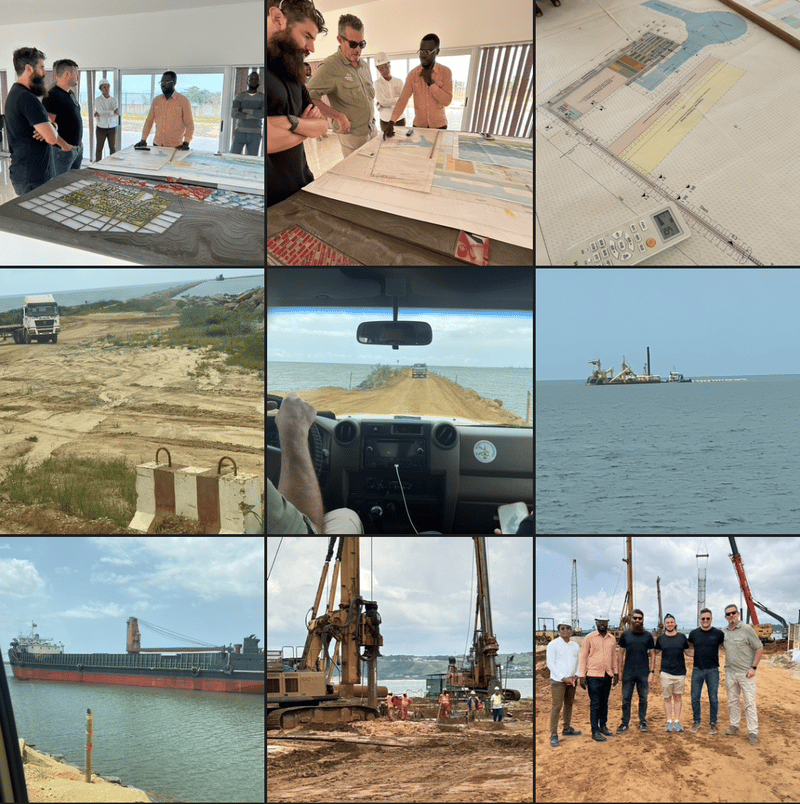
(read our MNB site visit article here)
On the domestic side, twenty of Angola's largest commercial growers have committed to MNB's 2026/27 fertiliser demonstration program. (source)
And as of this morning, there is actual Angolan phosphate rock sitting on a stockpile that could feed those domestic campaigns early - IF the approvals and sales arrangements come together.
The main thing we are watching out for now
The single biggest thing to watch now is MNB's capacity to fund the rest of the build AND ramp-up production from the project.
Mine build and ramp-up is usually the riskiest stage of the morph from explorer to producer.
A time where there is a lot of cash going out the door, but nothing coming back (YET).
MNB has so far secured:
- ✅ US$10M equity from Angola's Sovereign Wealth Fund (FSDEA) - received in full and already spent getting the project to where it is today. (source)
- ✅ US$16M project loan from the Industrial Development Corporation (IDC) of South Africa - A$6.94M drawn so far, A$16.19M still undrawn which MNB should be able to use throughout its build. (source)
- ✅ $6M equity placement at 1.5c (July/August) - fully completed now.
The last remaining funding piece is the ~US$5.48M loan facility from Banco de Fomento Angola (BFA) - one of Angola's largest commercial banks. (source)
For that one, in early September MNB said representatives of the guarantor from the lender visited site in mid-August as part of the final assessment for the guarantee supporting MNB's loan facility:
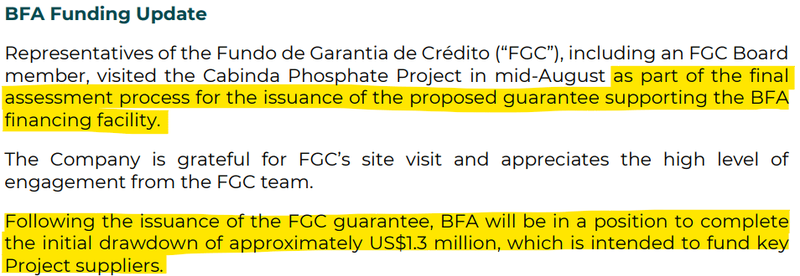
(source)
And then in the quarterly that came out last week, MNB said the guarantee is still pending and that:
"BFA remained a key funding priority” and that “Issuance of the FGC guarantee is expected to assist with the BFA funding and an initial drawdown of approximately US$1.3 million to support payments to key project suppliers".
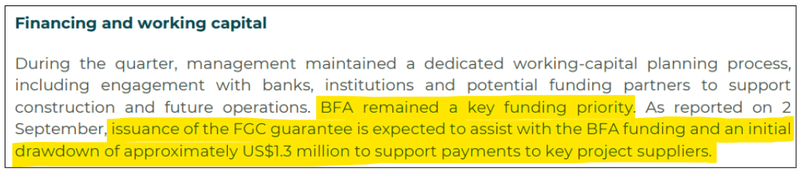
(source)
So that one is still a 🔄 - “pending”.
Next we want to see that funding deal closed ahead of that big "Ministerial site visit in December" - which is when the government is expected to be on site to see the plant structures completed.
Hopefully not long now until we see that first sack of phosphate...
AND hopefully the bigger re-rate toward our Big Bet happens once the market sees product being produced and ready to ship to customers.
MNB right now is capped at $23.4M.
Our new MNB Big Bet
"MNB re-rates to a $200M+ market cap by completing construction of its Phosphate Project, moving into production and generating its first fertiliser sales - and/or attracts a strategic investment or takeover bid at multiples of our Entry Price."
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true.There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our MNB Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
The 10 reasons we are Invested in MNB
Here are the 10 reasons we are Invested in MNB from our note on the 20th of July, 2026: We just put more money into MNB...here's why
(here they are summarised - with updates where things may have changed since July)
1. The Angolan government labelled MNB's project "nationally important"
2. Angola's Sovereign Wealth Fund is a shareholder
3. Definitive Feasibility Study (DFS) with strong economics
🚨 UPDATE:
The World Bank TSP (Triple Superphosphate) price averaged ~US$705/tonne in the September quarter.
At those prices, MNB’s DFS modelled US$95M of EBITDA per year and US$399M of post-tax NPV.
(NOTE the study is 4 years old, so the numbers could look very different nowadays)*
4. The hard part is done - civils complete, final build contract signed
5. After years of delays, the build funding is secured
6. The plant is already bought, paid for, and sitting in country
🚨 UPDATE:
No longer sitting - being assembled. See the photos from earlier in today’s note.
7. Fertiliser sold inside Africa carries an "inland premium" and MNB's product has been tested in country
8. MNB can produce a product that domestic and export customers want
🚨 UPDATE:
MNB now says the stockpiled rock could feed "potential early local campaigns" and a future granulation campaign.
Granulation is how MNB is turning its phosphate rock into NPK fertiliser granules which farmers can spread straight onto their fields - this is what the Heads of Agreement with Fertiafrica Benguela was all about back in August 2025.
9. MNB is moving into production now
🚨 UPDATE:
First phosphate rock mined and stockpiled at the project this morning so - Mine mobilisation is now ✅. (source)
10. (BONUS REASON) MNB also has a green ammonia project
Minbos Resources
What do we want to see MNB deliver over the coming months?
🔄 Complete Phase 2 construction
We want to see the plant assembled and reach dry commissioning.
Here are the milestones we are tracking:
- ✅ Civil works complete
- ✅ Structural steel installation started
- 🔄 Mechanical modules delivered to Cabinda and installed
- 🔲 Electricals, instrumentation and process control installed
- 🔲 Ministerial site visit (December)
- 🔲 Dry commissioning (Q2 2027)
🔄 Start mining
We want the mine side to keep pace with the plant.
Here are the milestones we are tracking:
- ✅ Mining contractor appointed
- ✅ Site prep + access roads
- ✅ Overburden removed, first phosphate rock extracted (NEW - this morning)
- 🔲 First grade control / assay results from mined rock
- 🔲 First ore hauled to the processing plant site
🔄 Complete the funding package
We want the full project funding closed out to cover construction AND ramp-up to full operations ("wet commissioning").
Here are the milestones we are tracking:
- 🔄 Transfer of Mining Investment Contract and Mining Licence
- ✅ US$10M FSDEA equity received
- ✅ US$16M IDC loan signed, drawdowns underway
- 🔄 US$5.48M Banco de Fomento Angola facility formalised
- 🔄 Working capital facility secured
🔲 First production and first sales
We want to see the plant wet commissioned, first product produced, and first revenue banked.
Here are the milestones we are tracking:
- 🔲 Wet commissioning
- 🔲 First shipment to a customer (including any unprocessed rock sales).
- 🔲 Binding offtake agreement(s) converted from existing MoUs/HOAs
- 🔲 First revenues
What could go wrong?
With the plant going up and now rock coming out of the ground, the biggest risk in the near term is still "Construction and commissioning risk".
Construction and commissioning risk
This is the big one right now. Plants rarely bolt together on time and on budget, and commissioning a first-of-its-kind-in-country plant can surface problems that take months to fix. Any delay would likely hit the share price hard given MNB's history.
Source: "What could go wrong" - MNB Investment Memo 20 July 2026
The other major risk is "tenure formalisation risk".
MNB's rights to the deposit sit under a Mining Investment Contract (December 2020) and a Mining Licence (March 2021) held by MNB, these need to be transferred to MNB’s Angolan subsidiary.
Today’s announcement says the transfer of those instruments and other "operational instruments" is still "progressing with the regulators". (source)
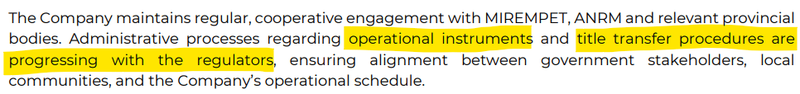
(source)
Meaning the formal licensing hasn’t been transferred into MNB’s Angolan subsidiary YET.
If the paperwork drags, it could delay MNB’s transition to a steady state producer.
Other risks
Like any small-cap mining developer, MNB carries significant risk, here we aim to identify a few more risks.
The remaining US$5.48M debt facility from Banco de Fomento Angola is still waiting on a guarantee to unlock critical drawdowns. If this final funding component stalls, the company may face cash flow pressure during ramp-up and be forced to raise further equity, diluting existing shareholders.
Commercial arrangements with local growers and partners like Fertiafrica remain early-stage or non-binding. There is no guarantee these discussions will smoothly translate into long-term, binding offtake contracts that deliver reliable revenue.
MNB’s export route relies on third-party infrastructure, particularly the Porto do Caio deepwater port which is still under construction. Construction or operational delays at the port could bottle up transport and limit export sales even if the processing plant is ready.
Much of the project’s modelled upside relies on strong global fertiliser prices driven by geopolitical supply disruptions. If global trade routes stabilise or phosphate demand softens, realised selling prices could drop significantly and hurt project margins.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our MNB Investment Memo
You can read our MNB Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
In our MNB Investment Memo, you can find the following:
- What does MNB do?
- The macro theme for MNB
- Our MNB Big Bet
- What we want to see MNB achieve
- Why we are Invested in MNB
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.