Sunday Edition: 11th October
Published 11-OCT-2026 15:10 P.M.
|
14 minute read
Disclosure: S3 Consortium Pty Ltd and its associated entities may hold direct or indirect interests in securities referred to in this publication and may receive fees or other forms of consideration from entities mentioned. These interests and arrangements may create a potential conflict of interest in the preparation of this material.
The information contained in this communication is provided for general information purposes only and may relate to speculative investments. It does not constitute financial product advice, and has been prepared without taking into account your personal objectives, financial situation or needs. You should consider obtaining independent financial advice before making any investment decision.
Any forward-looking statements are uncertain and not a guaranteed outcome.
Below you can find short overviews of all the content we published last week, plus links to each full note.
Further down, there’s also some links to other interesting stuff we came across on our travels around the internet.
Yesterday’s Saturday note: We're looking at Europe to add to the critical minerals theme
Quick Takes: OD6, TG1, EMD, PNN (x2), BKB, WCE, BPM, ION
Deep Dives: HVY, ROC
Other content: WAU, BUY, ILA, MTH, OD6, LSR, VKA, RML, WCE, SGQ, IVZ
OD6 raised $6.9M for its US fluorspar push.
Nice cleanly structured capital raise by OD6 at 9.5c, with no oppies attached.
We participated in this placement.
OD6 should now have more than enough cash to explore its fluorspar project in Nevada over the coming months.
Maiden drilling, bulk sampling, met results, ‘district scale’ exploration, and resource definition are all in the pipeline of upcoming catalysts.
The company’s name will soon be changed to “Adaven”, with a new ticker ADA, following an upcoming shareholder meeting.
Fun fact - “Adaven” is Nevada spelt backwards. If you google Adaven, it comes up as a “former mining settlement” turned ghost town in Nevada.
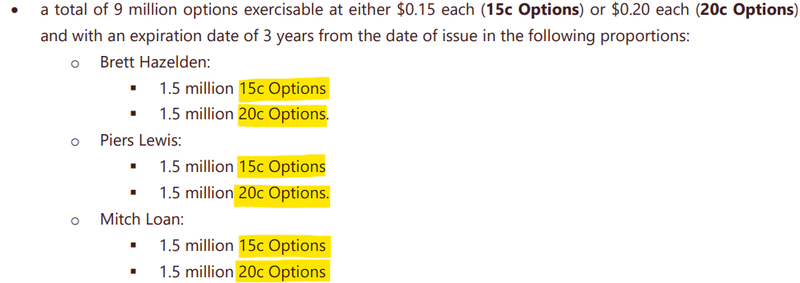
Also, good to see the directors incentives being set at much higher share prices relative to the raise & current market price for OD6:
(source)
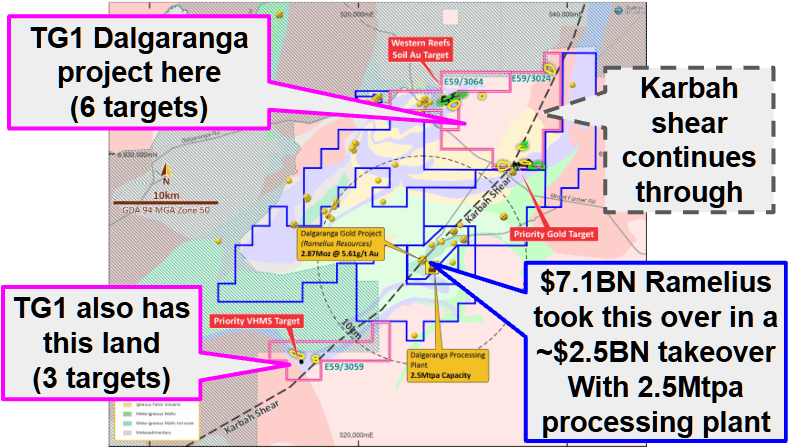
TG1 added five new gold targets next to $7.3BN Ramelius.
In total nine targets identified, five of which TG1 says are “priority 1 targets”.
All five have never been drilled before.
The reason we like the project is because it sits ~8km away, on the same geological structures that host $7.1BN Ramelius Resources’ gold mine (2.87Moz at 5.61g/t gold).
That is the Never Never discovery that was made only a few years ago - so you never know what micro cap TG1 might find here.
A big discovery would re-rate TG1 many multiples of its current valuation. But of course, no guarantees of exploration success - greenfield exploration is risky.
Long time TG1 shareholders would be familiar with the risks with early stage exploration given a few unlucky misses in recent years...
TG1 is working through tenement granting and heritage approvals, aiming to be drilling these targets before the end of the year.
We think there is still a lot of exploration to happen in this part of WA, so we are looking forward to seeing what comes from TG1's new ground.
(source)
EMD - investor webinar with former US Veterans Affairs Secretary.
Former US Veterans Affairs Secretary Dr David Shulkin joined EMD as Strategic Advisor on September 21.
See our take on his appointment here.
And to hear why he joined EMD as well as Shulkin’s (and EMD’s Chair - Greg Hutchisons) take on the US psychedelic medicine space - check out the full webinar here.
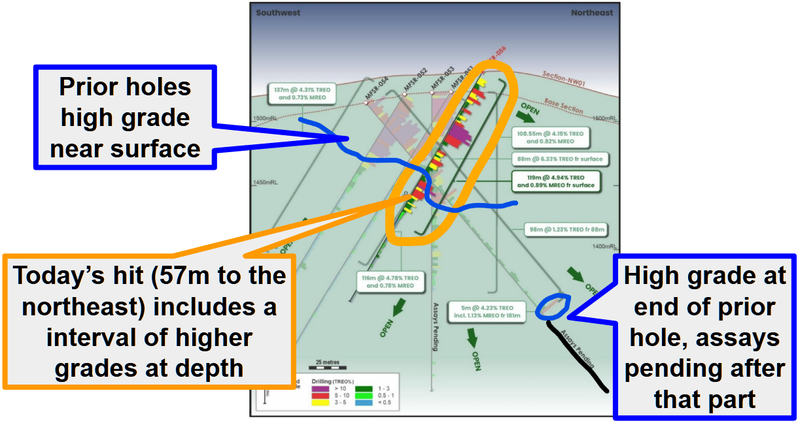
PNN hits 119m of high grade rare earths from surface.
This week’s partial assay covered the surface to 80m section of last week's hole, which now shows 119m at 4.94% TREO from surface.
Nicely timed assay result, with this part of Brazil having increased attention on it after PNN’s neighbour Meteoric received a $968M takeover offer from $13BN Lynas.
More of these drill hits along with PNN’s maiden JORC resource estimate and prelim met studies should hopefully build some momentum into the stock.
This weekend esteemed Sydney analyst Warwick Grigor from Far East Capital featured PNN in his weekly email to investors, saying PNN is his ‘favourite rare earths stock right now’.
Key takeaways from Warwick’s note:
- PNN is 20 holes into the first drilling program, starting in the centre of the mineralisation and stepping out in a 50m x 25m pattern from there.
- Drilling is 90% complete, but assays have been slow in returning from labs, with only five holes received so far - all look impressive so far, so no criticism about selective reporting
- Met studies are very important for rare earth companies - PNN’s prelim met studies are underway now and expected to be finalised by the end of the year.
- PNN’s market cap is around $65M, only 10% of the price Lynas has agreed to pay in the takeover of Meteoric Resources.
- PNN’s market cap is also much lower than Brazilian Rare Earths, which is $968M in size for a comparable resource.
Warwick cant see PNN staying around these prices for too long... and we tend to agree - but of course - no guarantees in life, much less in the stock market, and even less in small cap markets...
If you want to follow more of Warwick’s insightful commentary, sign up here: http://www.fareastcapital.com.au/register/
(source)
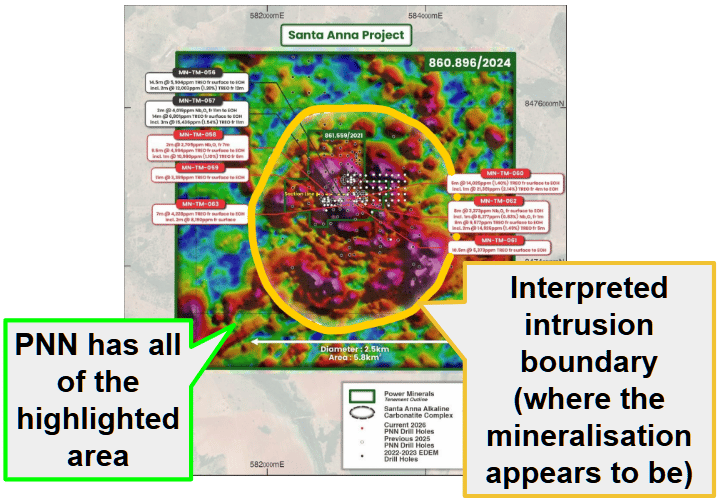
PNN also had an announcement out from its niobium project in Brazil.
This news comes from PNN's secondary asset in Brazil and it was a fairly technical one.
We are not professional metallurgists OR geologists - so the key thing we look for with any of these type announcements is whether or not the technicalities marry up against other well understood deposits globally.
PNN’s niobium is hosted in pyrochlore, a primary mineral source of niobium
PNN analysed 38 drill core samples, which averaged 68.8% niobium, with a peak of 73.9%, which is at the upper end of major carbonatite-hosted niobium deposits globally.
The results will now feed PNN's planned metallurgical testwork, the steps that work out how its possible to recover the niobium.
(source)
BKB hit gold at its primary silver project in the US - JORC resource estimate next.
BKB's Texas project produced ~35.2M ounces at 521g/t silver between 1883 and 1942.
The project had never been systematically drilled or assayed for gold - BKB has now found historic records showing sniffs of gold in old underground drilling data.
If BKB can get its project back into production, this time BKB can also focus on getting the gold credits out as well (especially with gold at ~US$4,000 per ounce).
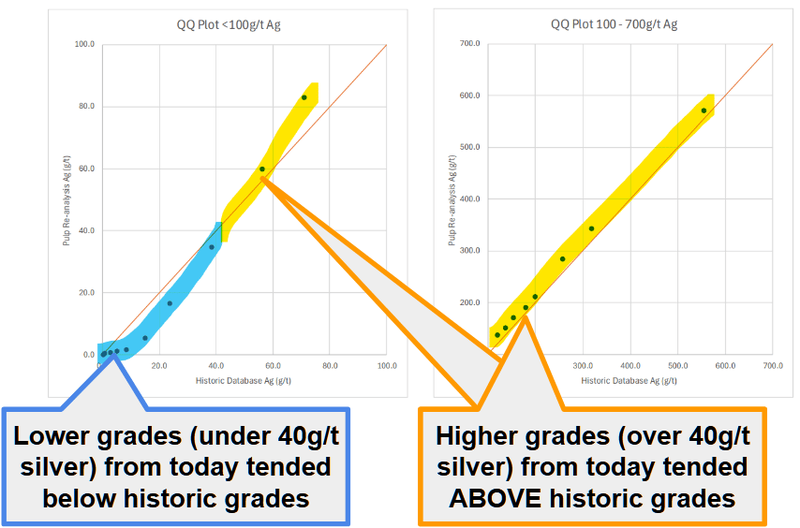
Also nice to see the re-assays keep delivering silver grades above the historic assays results:
(source)
WCE kicked off regional geophysics to hunt for WA silver mine repeats.
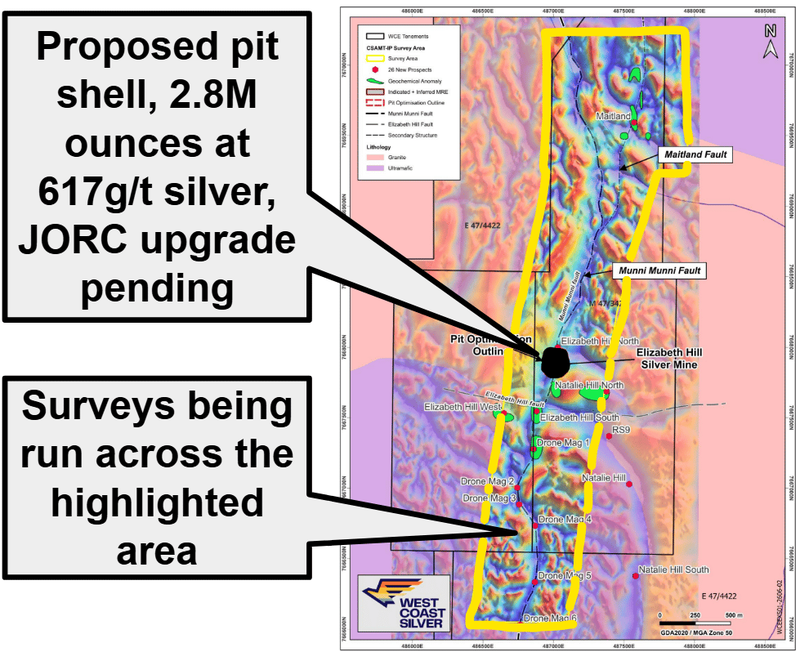
WCE's project currently has a maiden resource estimate of 2.8M ounces at 617g/t silver - the highest grade silver project on the ASX.
This round of geophysics will test ~4km of the fault that hosts the current resource - deeper than explored before - and eventually form part of the targets WCE will drill in the first half of next year.
(source)
BPM hit extensions to its WA gold project.
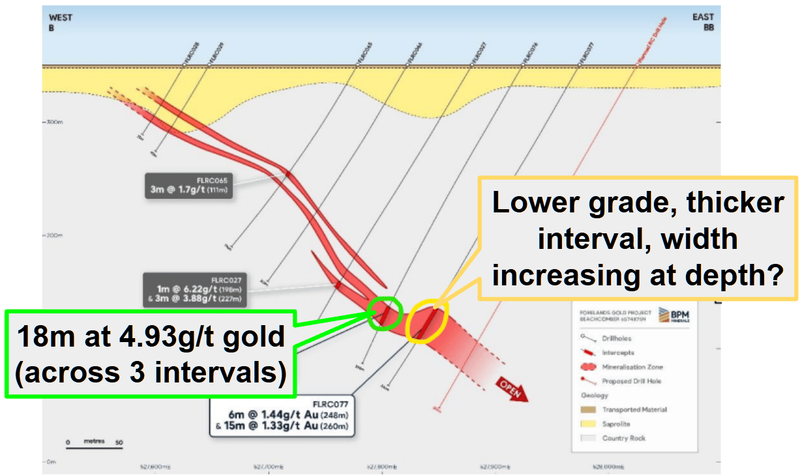
The assays came from BPM’s Beachcomber project - where BPM is running its third round of drilling, aiming to define a maiden JORC resource estimate for the project.
The standout was 18m at 4.93g/t gold, which looks to have extended the known gold structures on the project.
Bigger should mean a bigger resource estimate, with the rest of the results from this program still to come.
Meanwhile BPM is drilling its giant Bonnie & Clyde targets, paused by weather but expected to resume in coming days.
That program is big enough to tell us whether BPM has made a new discovery, with drill results expected this quarter or next.
(source)
ION targeted US$18M in funding for its first US rare earths module.
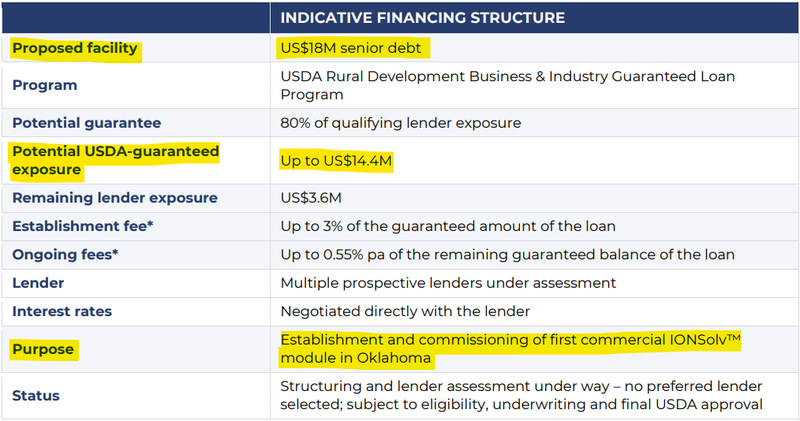
The US$18M debt funding pathway that ION outlined this week would fully build and commission ION's first commercial recycling module in Oklahoma, ramp up costs included.
Up to 80% (US$14.4M) of the debt could be guaranteed under a USDA (US Department of Agriculture) program.
ION is also assessing a prepared industrial site in Latimer County, Oklahoma, which could cut the cost, time and complexity of the build versus a greenfields site.
A module there would sit right near USA Rare Earth, which has said it will use third party feedstock as its magnet plants ramp up.
(source)
Heavy Minerals (ASX:HVY)
Half the battle in public markets is keeping your company’s capital structure pristine long enough to thrive when the macro winds turn in your favour.
Especially in the small end of the market where heavily dilutive cap raises, 1:1 oppies, broker options, and convertible death notes run rampant.
One of our Investments that’s managed to defend its capital structure (beyond even our most bullish expectations) over the last couple of years is Heavy Minerals (ASX:HVY).
HVY is capped at $23.5M, with only ~73.4M shares and ~13.7M options/performance rights on issue.
Housed in this tight capital structure is a portfolio of three different assets at three different stages of development:
- Port Gregory, WA - flagship pre-production mining asset - at the Pre-Feasibility Study stage, showing a Net Present Value (NPV) of $322.8M.
- Kanmantoo, SA - fast tracking garnet production by processing tailings from an operating copper mine. Our rough calcs show it could generate up to ~$31.1M in gross revenue for the first 3 years, followed by up to ~$62.2M per year after that.
- Red Hill in WA - where HVY now expects to have a maiden resource estimate due within ~4-5 weeks.
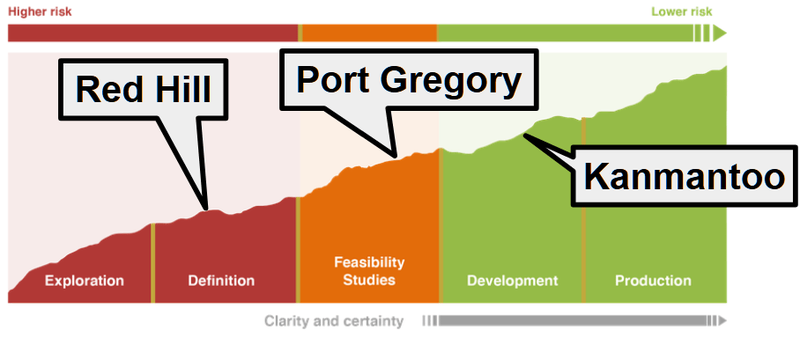
Typically, by the time any small cap is anywhere near production OR even just a Pre-Feasibility Study, it has issued billions of shares, raised capital more times than you can count and sometimes even done a share consolidation as well.
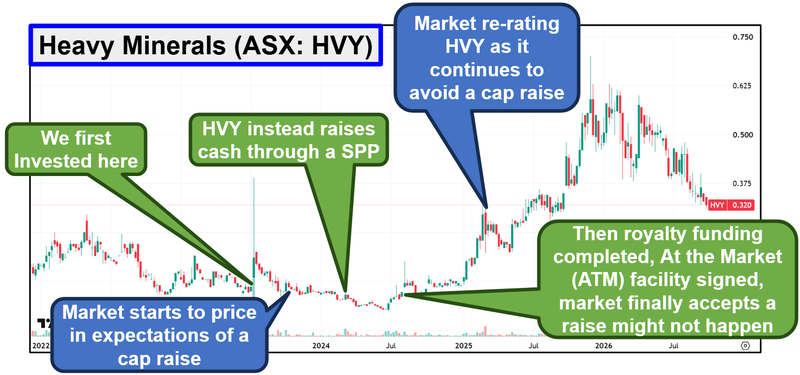
HVY has been able to get to where it is today via a non-dilutive royalty funding arrangement and some clever small conversions of shares into cash from an “At the Market facility”.
The ability to dodge a large capital raise has taken out overhang and resistance over its share price.
Check out the HVY share price chart below - the market didn’t really believe it would avoid a cap raise for a few years and then just said “okay we get it” and started re-rating the stock in ~2025:
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Read more: HVY - ducking and weaving, avoiding dilution
RocketBoots (ASX:ROC)
What does the AI boom and the railroad buildout of the 1840s have in common?
In the 1840s, during the big railroad buildout, a bubble formed around railway stocks.
(like we are seeing now with the AI models - OpenAI (ChatGPT) & Anthropic (Claude))
But, in the long run the big winners weren't the railway stocks themselves.
It was actually the retail, manufacturing and logistics businesses built on transporting stuff around faster.
The same thing happened with electricity, the internet and even smartphones.
Our view is that every technology boom follows the same pattern.
And the businesses that survive (and dominate) are the ones that find the best ways to build a business using that new tech infrastructure.
Which is one of the big reasons we made RocketBoots (ASX:ROC) our 2025 Tech Pick of the Year.
ROC was "doing AI" way before ChatGPT was released - back in 2022. (source)
Taking in-store video and catching theft + optimising staff productivity for giant retailers and banks.
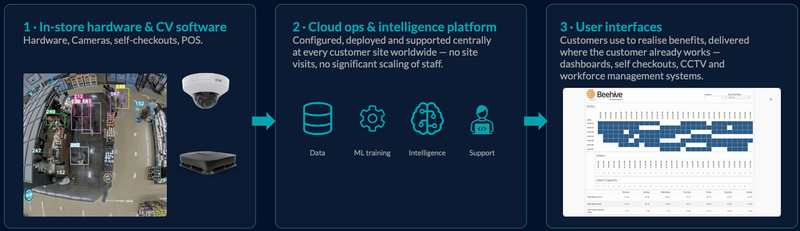
ROC is already servicing customers across retail grocery and banking - including two ASX 20 companies.
More on what ROC does (and why its customers pay for it) later in the link below.
The big company making deal for ROC came in December last year and then March this year when ROC announced these two:
- ~$9.1M PER YEAR in Annual Recurring Revenue, for at least 5 years, with a "tier-one multinational retailer" (source);
- PLUS a $3.3M one-off "activation contract" from the same customer - ROC gets paid to switch the tech on (source).
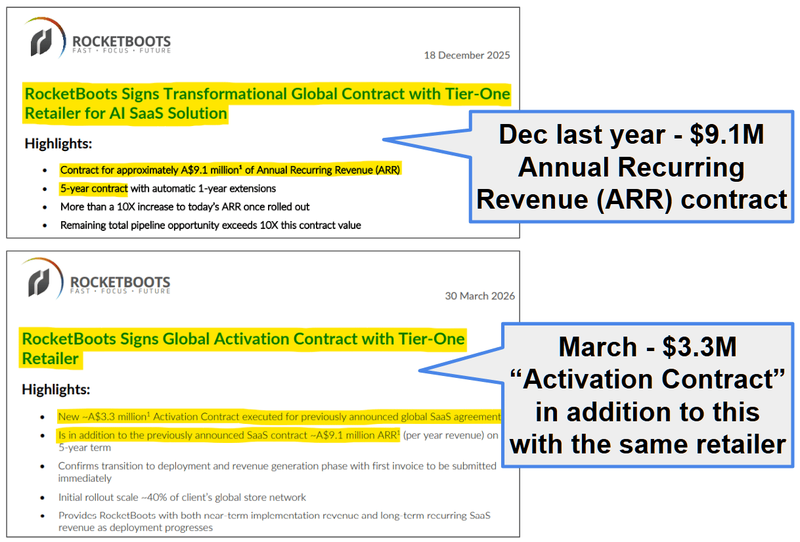
ROC's total revenue for FY26 was ~$725k.
So this one deal with a Tier 1 global retailer can more than 12x the entire company's last-year revenue - on a recurring annual basis - once fully rolled out.
And the first contract is only for about 40% of their stores - perhaps we can expect more stores in the future?
Seriously one of the best deals we have ever seen from any small ASX listed tech company.
At the same time, there’s activation risk still at play, timing of full roll outs is unclear, and things can and will change (especially in small cap stocks).
This week ROC confirmed the first store installations under that deal have started - in the USA.
The Australian - Wiluna Mining nears $180m ASX float
(Our Investment WAU has a non-binding MoU with Wiluna that if completed, could allow for a low-capex, fast-track pathway to production without the need to build a $100M+ processing plant.)
FT - Saudi Aramco Chief Warns World's Oil Stockpiles Are 'Scarily Thin'
The Guardian - Trump promises not to attack Iran before November's US midterms
Reuters - US Gulf producers shut in more oil and gas as Isaias nears landfall
Bloomberg - Europe’s Tough Choices to Avert a Gas Supply Crunch This Winter
Reuters - US, Russia explore gas sale to Europe amid Ukraine war, say sources
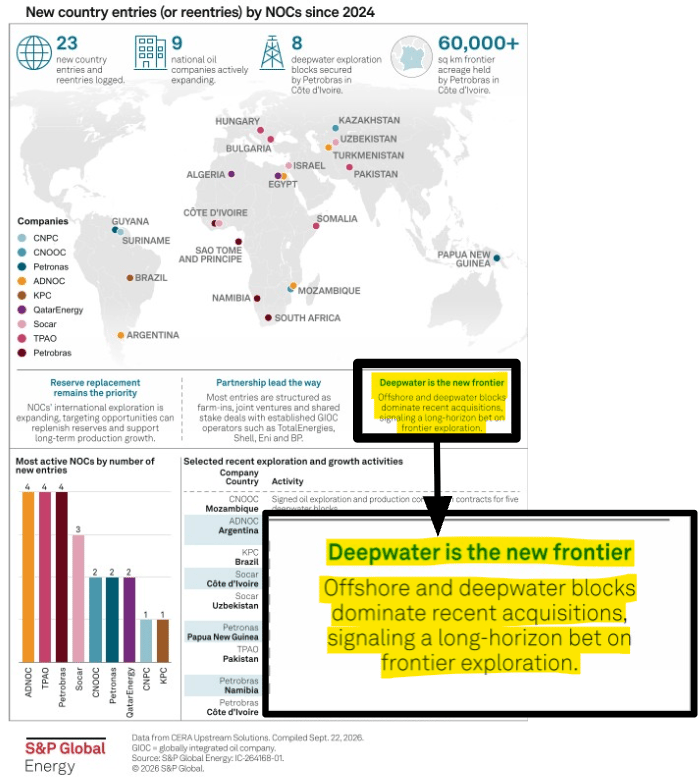
LinkedIn (S&P Global Energy) - We came across the below infographic, which shows a greater interest in big “swing for the fences” type of oil and gas exploration, particularly offshore deepwater targets.
This is part of the reason for our recent Investment in BUY, which acquired an offshore deepwater exploration target that fits this exact bill, see our initiation note:
Sprott - The Rare Earths Powering the Next Wave of Robotics
(a nice in depth report here about rare earths and their uses in robotics)
Australian Resources & Investment - Nolans breaks ground as Arafura faces next investor test
Bloomberg - Germany, France Push New Trade Weapon Before EU-China Talks
Reuters - Zambia says it is negotiating US minerals deal after decoupling health pact
AFR - Fears mount Russia covering up a lab plague leak
Substack (Arb Letter) - Russian Plague Outbreak or Psy Op?
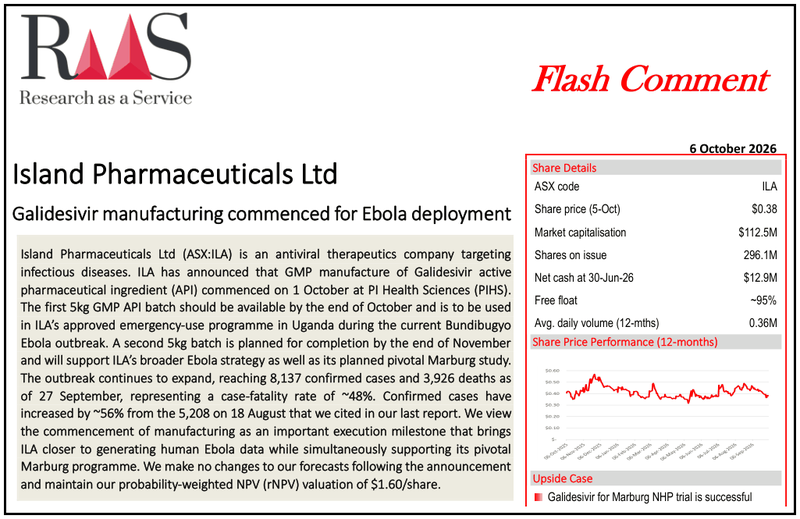
ILA - Flash Comment (Research Report) - RAAS
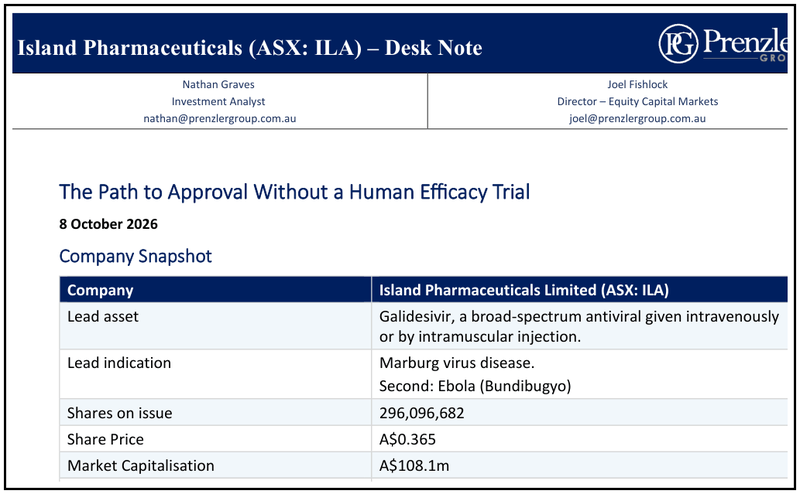
ILA - The Path to Approval Without a Human Efficacy Trial - Prenzler Group
MTH - A silver district with high-grade gold - Durango, Mexico - Target 1 economics, Target 4 growth, Copalquin district scale
OD6 - Advancing USA and Australian Critical Mineral Projects - Investor Briefing 7 October 2026
LSR - Gold REE Copper Tier-1 Mining Jurisdictions - Presentation October 2026
LSR - Lodestar Minerals Investor Update (October 8, 2026) (Webinar)
MTH - The Next SilverCrest or Palmarejo? Mithril Silver & Gold CEO: "We've Definitely Got the Scale" (CEO interview)
VKA - Linka LIGHTS UP as Viking hits ‘high-grade’ tungsten (MD interview)
RML - Gold, Antimony, Tungsten in Idaho, But Can They Really Mine It? | Resolution Minerals CEO Interview (CEO interview/podcast)
RML - JMM Gold Forum - Resolution Minerals (ASX:RML) - 30 September 2026 (CEO forum interview)
WCE - Silver hunt ramps up along Munni Munni Fault (Company news update)
Geopolitics (including rare earths) - Russia, China, Iran, Energy: Why Every Western Move Makes Things Worse | Doomberg (Raise Your Average.) - In particular the section on rare earths from ~66mins caught our attention
Rick Rule: The Next 10 Years Will Be Nothing Like The Last 40 (Michael Campbell's Money Talks)
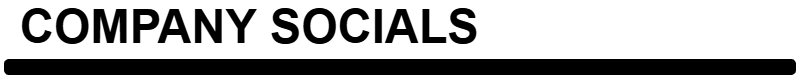
SGQ - highlighted its Araxa project sitting beside CBMM's niobium operations in Brazil, which controls around 92% of global supply share:
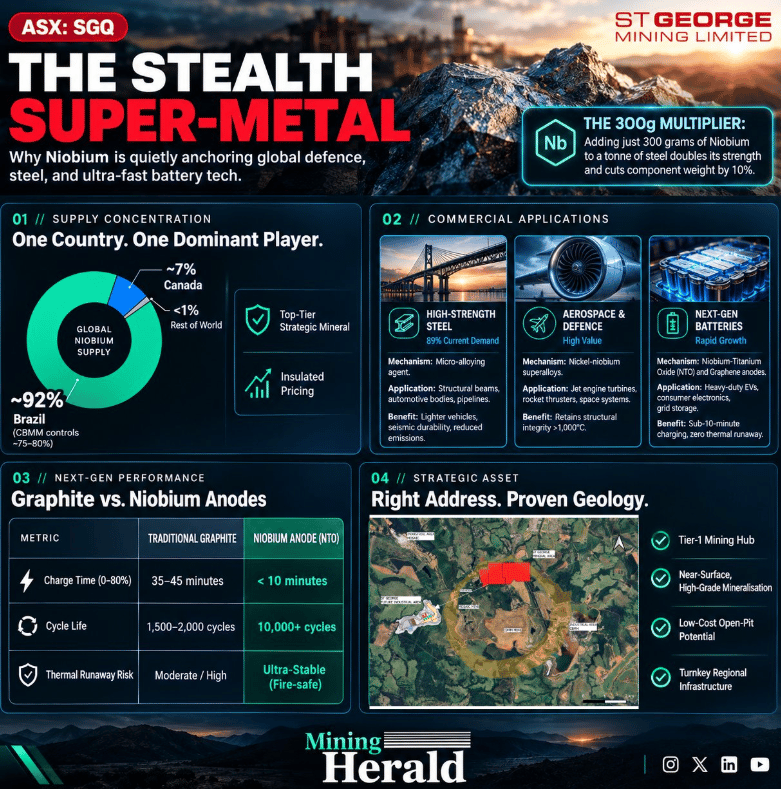
SGQ - also compared SGQ’s Araxa's rare earths resource against Meteoric's Caldeira project, showing far higher grade.
Last week Meteoric caught an almost $1BN bid from Lynas, so it was interesting to see how SGQ’s asset stacks up:
Of note is the different types of mineralisation - Meteoric's asset is an ionic clay asset, and SGQ’s asset is carbonatite hosted, similar to Lynas’ WA asset and MP Materials’ in the USA.
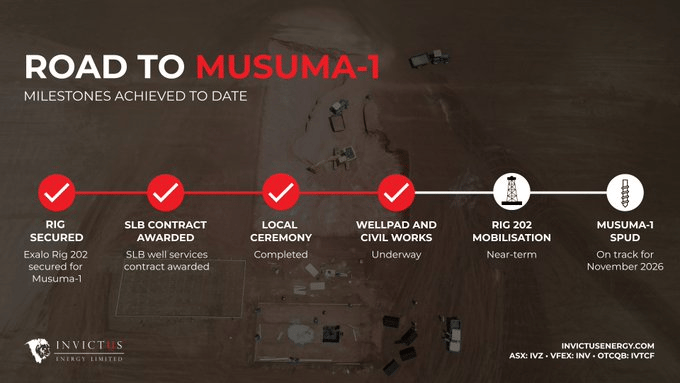
IVZ - reiterated the path to drilling in November, the rig is secured, well services contracted, next up civil works then mobilisation ahead of the November spud:
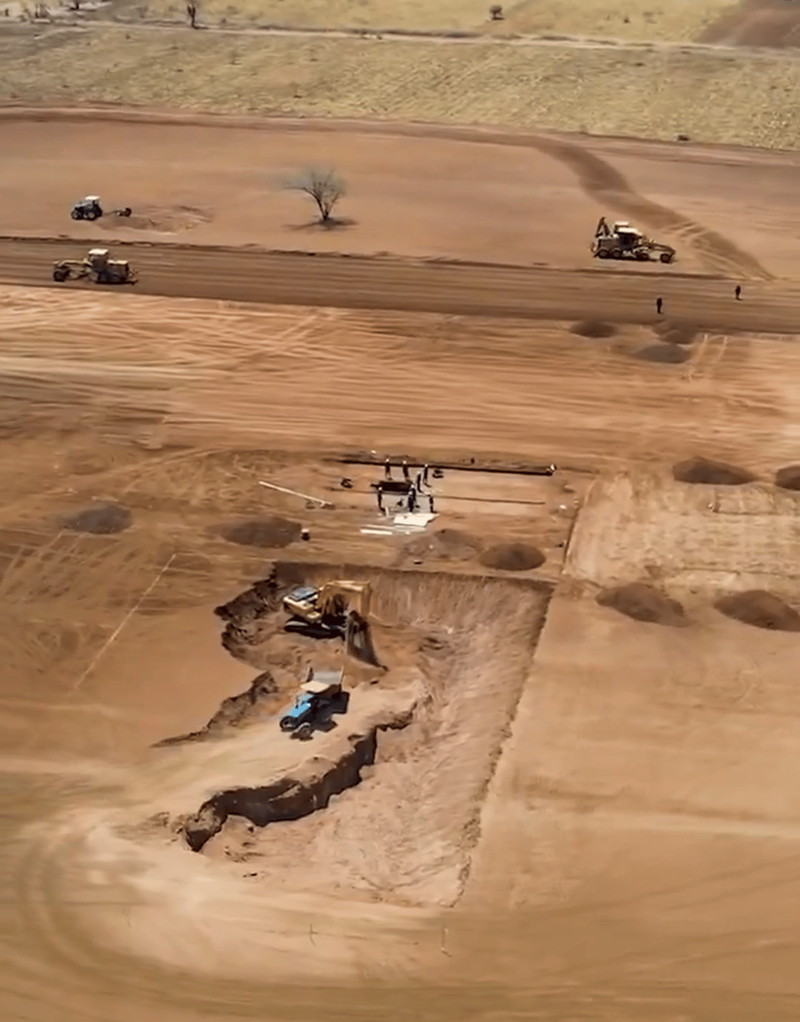
IVZ - also had country manager Barry Meikle walk through progress at Musuma-1 ahead of the targeted November spud in an on site video:
A word of caution...
While we aim to highlight developments in the small cap space, investing in early-stage and small cap companies - like those we cover - is inherently risky.
These companies often face funding challenges, regulatory hurdles, and market volatility. Announcements may reflect aspirations more than guaranteed outcomes.
Things can, and often do, change.
Just because a company has signed a deal, released drill results, or appointed a new director doesn’t mean success is assured.
Always assume delays, cost overruns, or results that don’t pan out.
We’re here to share insights, not offer personal financial advice - so please do your own research and speak with a licensed adviser before acting on anything mentioned.
Follow us on social media: X, LinkedIn, Facebook
Bye for now.
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.