HVY - ducking and weaving, avoiding dilution
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 3,745,000 HVY Shares at the time of publishing this article. The Company has been engaged by HVY to share our commentary on the progress of our Investment in HVY over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
Half the battle in public markets is keeping your company’s capital structure pristine long enough to thrive when the macro winds turn in your favour.
Especially in the small end of the market where heavily dilutive cap raises, 1:1 oppies, broker options, and convertible death notes run rampant.
One of our Investments that’s managed to defend its capital structure (beyond even our most bullish expectations) over the last couple of years is Heavy Minerals (ASX:HVY).
HVY is capped at $23.5M, with only ~73.4M shares and ~13.7M options/performance rights on issue.
Housed in this tight capital structure is a portfolio of three different assets at three different stages of development:
- Port Gregory, WA - flagship pre-production mining asset - at the Pre-Feasibility Study stage, showing a Net Present Value (NPV) of $322.8M.
- Kanmantoo, SA - fast tracking garnet production by processing tailings from an operating copper mine. Our rough calcs show it could generate up to ~$31.1M in gross revenue for the first 3 years, followed by up to ~$62.2M per year after that.
- Red Hill in WA - where HVY now expects to have a maiden resource estimate due within ~4-5 weeks.
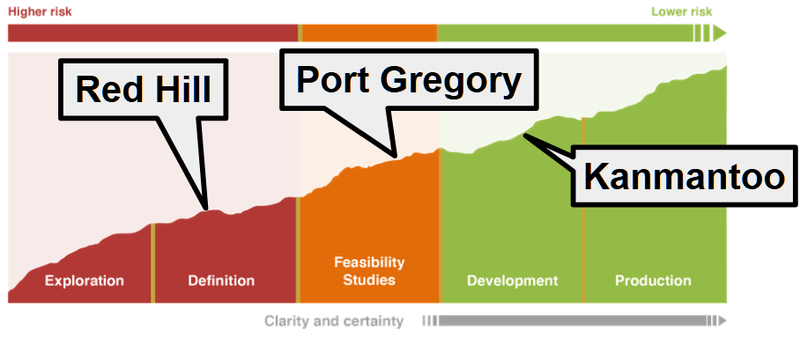
Typically, by the time any small cap is anywhere near production OR even just a Pre-Feasibility Study, it has issued billions of shares, raised capital more times than you can count and sometimes even done a share consolidation as well.
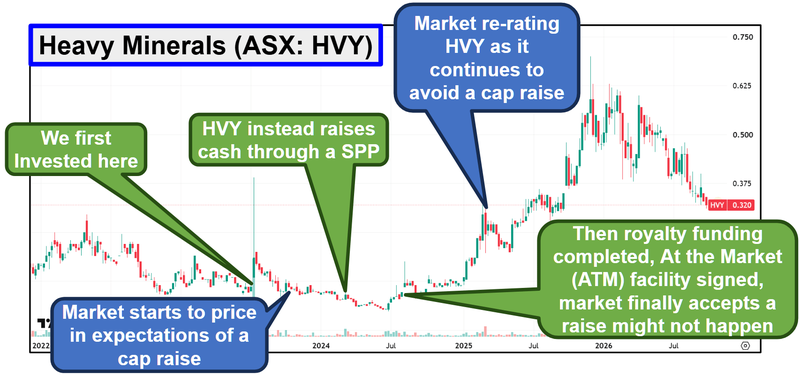
HVY has been able to get to where it is today via a non-dilutive royalty funding arrangement and some clever small conversions of shares into cash from an “At the Market facility”.
The ability to dodge a large capital raise has taken out overhang and resistance over its share price.
Check out the HVY share price chart below - the market didn’t really believe it would avoid a cap raise for a few years and then just said “okay we get it” and started re-rating the stock in ~2025:
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Cool, so what is garnet anyway?
Garnet is an industrial mineral, and its two big industrial applications are:
- Waterjet cutting - garnet + high pressure water jet to precision-cut steel, titanium, glass and composites (think aerospace parts, defence manufacturing).
- Abrasive blasting - garnet used to strip rust and old coatings off ship hulls, bridges, pipelines and tanks before they're re-coated.
Here is what the stuff looks like:
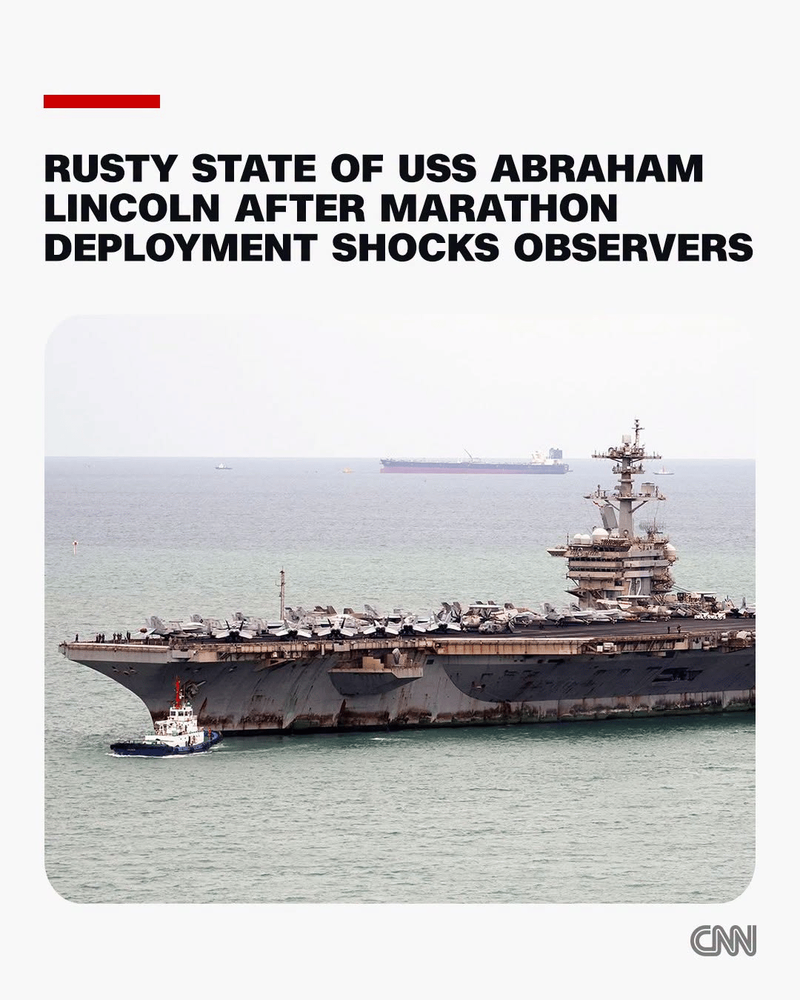
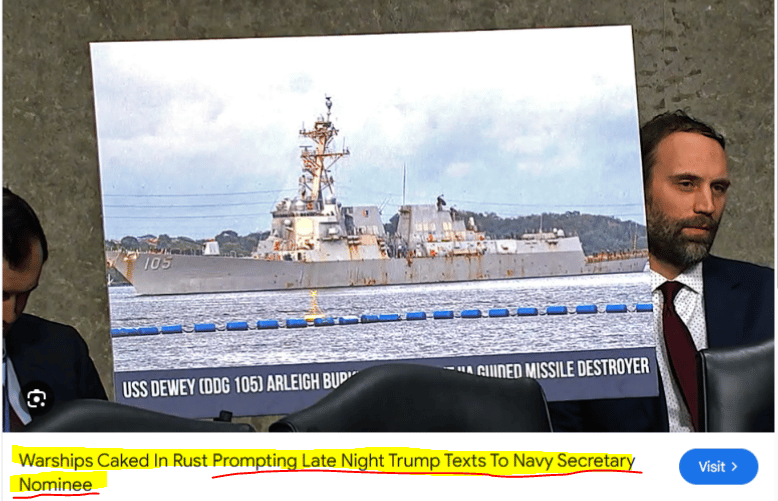
We will explain more later in today’s note, but for now all you need to know is that every time you see something like the below in the news, there’s consequences for the garnet market:
(source)
Rusty ships, rusty bridges = need garnet to fix.
We like HVY because it's one of the only ways to get genuine garnet exposure in the ASX small cap end of the market - and because we are starting to see there is everything HVY needs to build a large scale pureplay garnet business.
Development financing pending of course...
It won’t be easy... but we can see how everything could fall in place in an ideal world.
HVY says it's already “progressing discussions with multiple funders” for the $25M to $30M needed to build its plant in South Australia.
Not a huge amount of capital in the context of a mining operation.
And HVY has a PFS for its WA asset saying it needs $122.1M in CAPEX funding to build that project.
There is a world where HVY becomes a big ASX listed garnet producer by:
- First, financing its South Australian project (processing only, no mining).
- Getting into production (processing only, no mining).
- Producing and selling garnet.
- Using that cashflow to finance the development of its Port Gregory asset in WA. (mining and processing).
Based on the July Pre Feasibility Study, the Port Gregory Project could return to HVY:
- Net Present Value (NPV) of $322.8M.
- EBITDA of $1.34BN over 24 years.
- Internal Rate of Return of 47.6%.
- A 3.1 year payback,
- Based on $122.1M CAPEX
(read our detailed take on the PFS here)
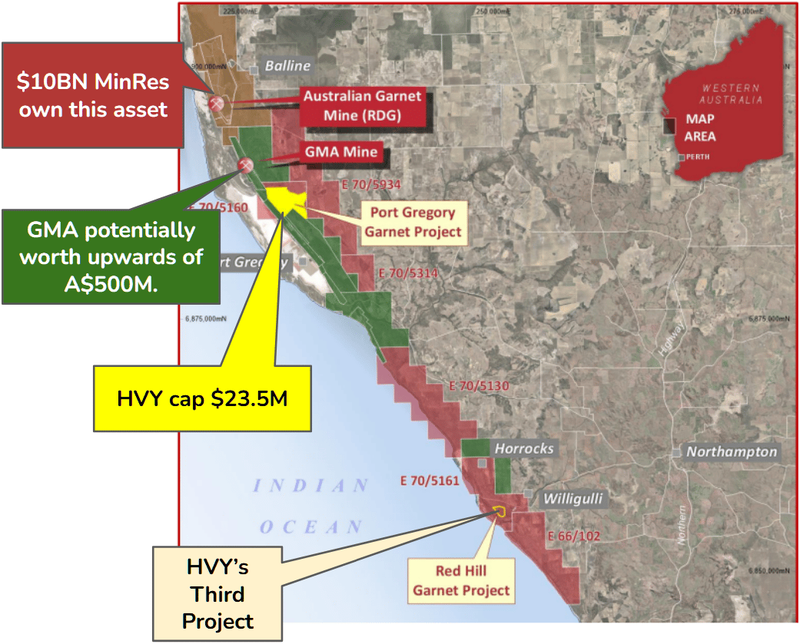
Right next door to the world’s biggest operating garnet mine.
(source)
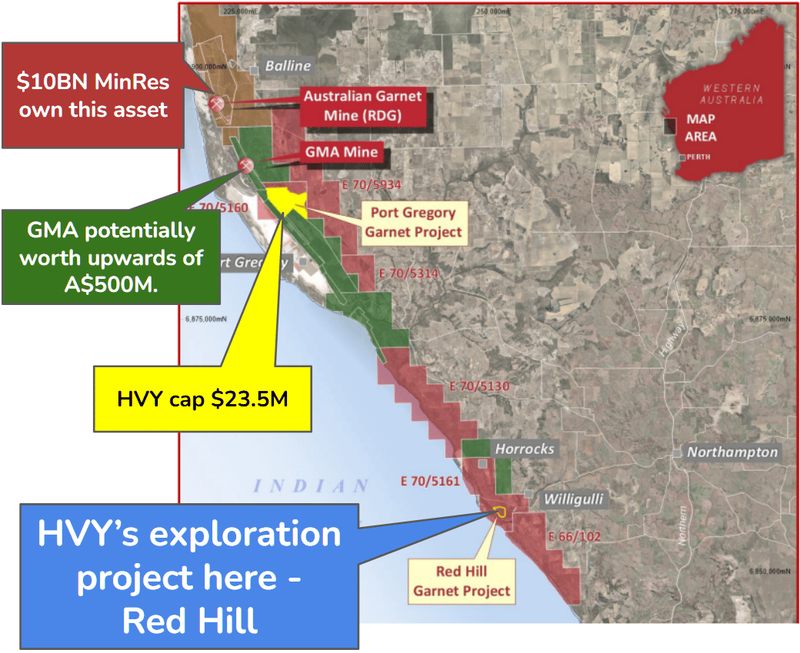
And then once that's brought online, HVY can slowly drip feed some of that cash into advancing its third exploration asset to build up a resource base capable of being mined for decades.
Obviously, a lot of things need to go right for that to happen, but it's why we are in the game of Investing long term in small cap stocks.
It can be very rewarding for shareholders when that tiny chance that a tiny company successfully executes on a big vision actually happens.
But there’s no guarantee of success in this game.
So how does HVY get into production quickly without any mining?
The project we think is closest to being production ready is Kanmantoo in South Australia.
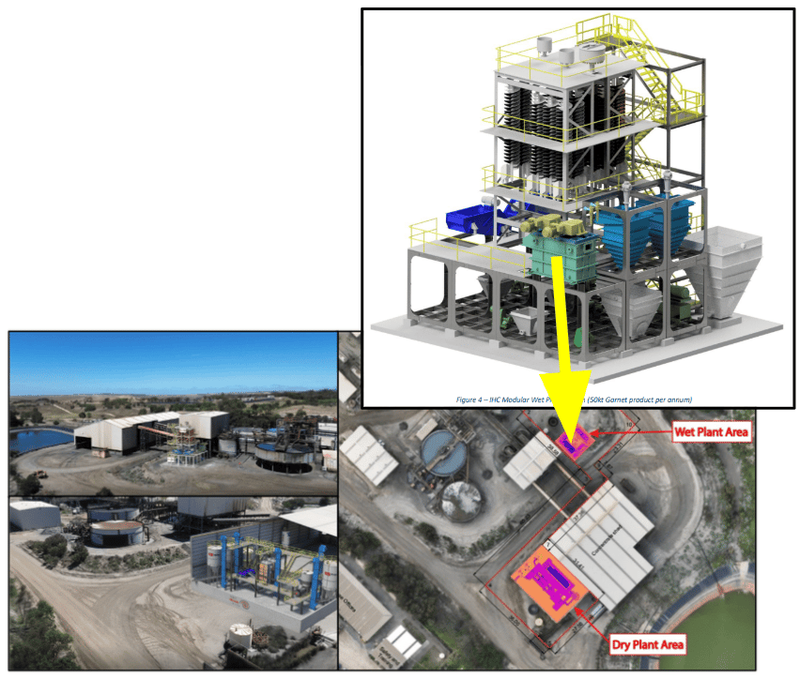
That’s the project where HVY signed a binding deal earlier this year with ASX listed South Australian copper miner Hillgrove Resources (which recently changed name to Kantra Copper) to:
- Take the garnet rich tailings (waste) from its producing copper-gold mine,
- Process the tailings,
- Extract valuable industrial use Hardrock Almandine Garnet, and;
- Sell that garnet for cash.
(source - HVY announcement)
Here is a quick overview of why we like HVY’s deal with Hillgrove (now Kantra Copper):
- HVY is partnering with an established copper producer capped at ~$283M - this producing company is letting HVY onto their mine site to plug into their processing plant - a strong show of confidence in HVY’s ability to execute.
- HVY has already done most of the technical work - Bulk sampling, metallurgy and flowsheet work is all done. The process plant is designed. End-product testwork is complete and distribution, financing discussions are underway.
- HVY could produce $31.1M to $62.2M per year gross revenue from just $25M to $30M CAPEX (our rough gross revenue calcs, full details in a second)
- Simple, predictable permitting process - HVY is plugging into Kantra’s existing processing circuit, so there shouldn’t be any major permitting issues getting HVY’s plant built.
- Quick timeline to production subject to funding - HVY expects to be in production ~8-10 months after making a Final Investment Decision on the project.
- HVY can scale up to meet demand - HVY is planning to produce up to ~50ktpa of waterjet garnet (~10% of global demand) and eventually aims to increase capacity to 100ktpa. This means, HVY can scale up/scale down based on market demand for its product.
🎓 We covered the Hillgrove (now Kantra) deal in detail when it was announced - read: HVY: Transformational new deal just announced? Producing by end of this year?
Why HVY and why now?
Well back in 2007 when Kantra was going through permitting on its project, garnet was listed as one of the commodities that would be mined from the project. (source)
Despite that, no one has had a crack at recovering the garnet (not even Kantra).
Enter HVY.
While Kantra is focused on copper, HVY is fully focused on garnet, has garnet knowledge and would know the industry inside and out having worked on its garnet asset for years.
HVY is the natural partner to extract and sell the valuable garnet from Kantra’s mine tailings.
HVY’s deal with Kantra means HVY pays ~$200k to Kantra ($50k was due on signing then $150k at FID), plus 15% of gross revenue (from garnet sales) made while the copper mine is still operating, then 5% of revenue (from garnet sales) after the mine shuts down.
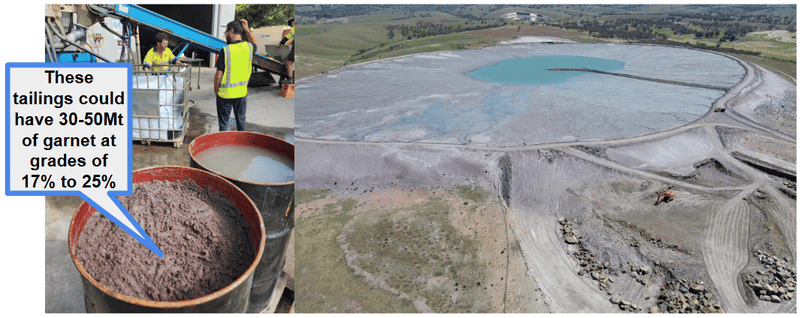
Wait... HVY keeps producing garnet even when the copper mine shuts down?
Yes, from all of the already processed material sitting in Kantra’s tailings storage facility.
(source)
It's a win-win for both companies.
HVY can become a revenue generating garnet producer without all of the CAPEX and mining operating costs associated with building a resources project completely from scratch.
Kantra gets to monetise a resource that was going untouched until HVY entered the picture.
Our rough calcs show that HVY’s South Australian project could generate up to ~$31.1M in gross revenue for the first 3 years, followed by up to ~$62.2M per year after that.
What does the “fast to production” strategy mean in terms of numbers for HVY?
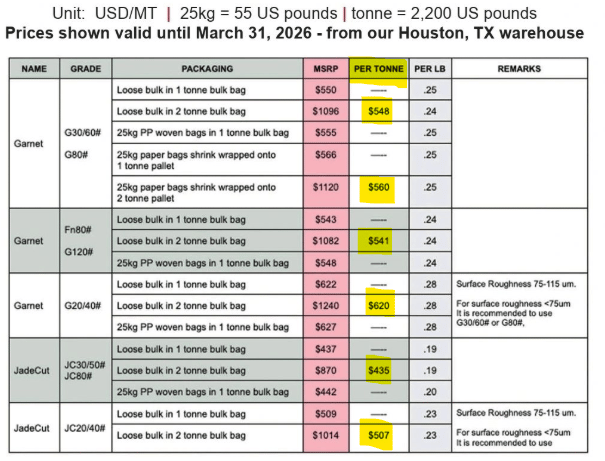
According to this (now deleted) post, garnet prices range between US$435 to US$620 per tonne:
(source)
Even taking the LOWEST price per tonne of US$435 = ~$630 AUD per tonne.
(for the simplicity of this basic calc just to show simple total gross revenue, let’s assume full capacity to 50,000tpa from day 1. In reality, it will likely take time to get the plant humming smoothly and up to this capacity)
50,000 tonnes per annum x $630 per tonne = $31.1M gross revenue for the first 3 years.
Then after 3 years, 100,000 tonnes per annum x $630 = $62.2M gross revenue per year after that for the life of mine.
Even taking out Kantra’s 5% to 15% cut, the rough numbers look very good for a $23.5M capped company like HVY.
Caution - this is a VERY rough calc, net revenue to HVY will need to take into consideration either 15% or 5% gross revenue payment to Kantra, the cost to produce, plus any fees paid to distributors - also garnet prices may go up OR down over life of mine - this rough calculation is for illustration purposes of the general scale of the project and should not be relied on.
The big variable will be the “cost to produce” which could be minimal given HVY doesn't have to actually mine anything.
However, processing tailings can be notoriously tricky - so it's not completely without risk.
HVY says it's already “progressing discussions with multiple funders” for the $25M to $30M needed to build this plant. (source)
HVY has previously said production would be 8-10 months after the build starts.
Initial expectations were by the end of 2026 for production - but that looks like it must have slipped now given we are already in October of 2026 - in any case, hopefully it means we are very close to a Final Investment Decision AND financing.
More on garnet and why it’s important
Garnet is an industrial mineral used in high-precision manufacturing, global shipbuilding, defence infrastructure, and heavy engineering.
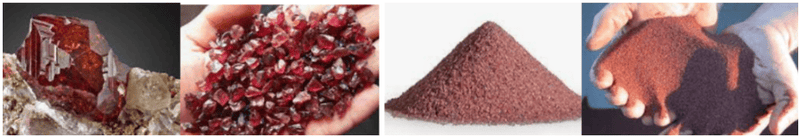
Being an industrial mineral, garnet doesn’t really get much mainstream attention - but it also means there are very few companies on the ASX looking to build a business in that space - a big part of where the opportunity is for HVY.
Garnet’s two big applications are:
- Waterjet cutting - garnet + high pressure water jet to precision-cut steel, titanium, glass and composites (think aerospace parts, defence manufacturing).
- Abrasive blasting - garnet used to strip rust and old coatings off ship hulls, bridges, pipelines and tanks before they're re-coated.
The more the world builds ships, maintains navies, and patches up old steel infrastructure, the more garnet gets used.
And there is a LOT of that going on right now.
The US budgeted ~US$40BN for bridge repair, replacement and rehabilitation - including ~US$2BN to fix rusting steel bridges. (source)
The Trump Administration has singled out the rusting US Navy fleet as a national embarrassment - and rust removal is exactly what garnet does.
(source)
Major shipbuilding companies and infrastructure maintenance companies use garnet to safely reduce corrosion and extend the life of surfaces that are prone to rust.
A lot is happening on the demand side, but admittedly, it's a lot harder to forecast.
What’s easier to understand and model is what’s happening on the supply side.
The garnet market is getting squeezed - hard
Here is what’s been happening on the supply side over the last 12 months:
- Australian Garnet (next door to HVY, owned by $10BN Mineral Resources) is now on care and maintenance.
This was the newest garnet mine in Australia and it was put on care and maintenance by its owner MinRes, effective 1 July 2026, after a strategic review.
That's a mine that was supposed to be a meaningful new source of global supply.
We can’t see MinRes diverting attention away from its multi billion dollar iron ore and lithium mines to focus on this.
So it's hard to see it being switched back online and ramped up any time soon.
- Nordic Mining (Norway) is still not ramped up.
Europe's great garnet hope has struggled to get to nameplate capacity - producing just ~5,587 tonnes of garnet in the March 2026 quarter, with bottlenecks in its dry plant and design capacity now targeted for late 2026.
The June quarter saw 10,127 tonnes (production near planned capacity), however this quote was reported in the first half report "pending the outcome of ongoing discussions regarding the quality of products shipped" (source)
So while production numbers are up, there are obviously concerns on the quality of the garnet that’s being produced.
- And India - once a major garnet exporter - has had beach sand garnet production effectively banned for years. (source)(source)
So is the price responding?
US warehouse pricing had garnet at US$435 to US$620 per tonne earlier this year - which was already a significant step up on prior years.
The biggest garnet name in North America (Barton International) also went to Norway to lock up distribution rights over Nordic Mining’s garnet. (source)
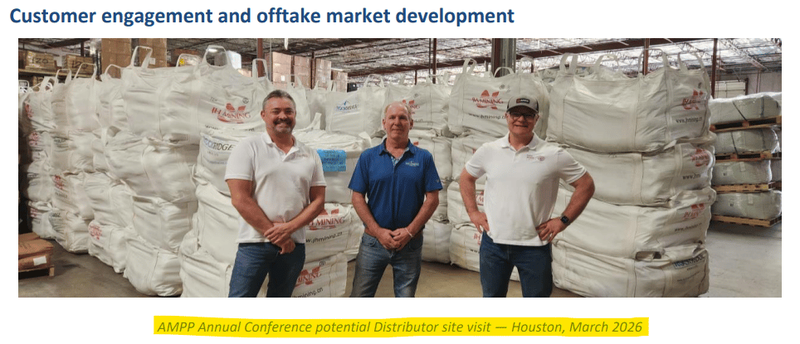
Hopefully, HVY was able to land a few meets and get in front of the big garnet buyers at this year’s AMPP conference in Houston (which HVY attended back in March). (source)
The AMPP conference in Houston is a trade show for the coatings, surface-prep and abrasives industry, meeting US garnet distributors and end-users about potential offtake:
(source)
Hopefully they have been briefed on HVY’s WA asset (after the PFS back in July) AND the South Australian “fast to production” strategy - both assets capable of solving any supply bottlenecks around the world (with appropriate funding ofcourse).
An offtake/distribution deal could unlock whatever funding HVY is looking to secure for either of its assets - which would help HVY deliver our Big Bet as follows (albeit later than the 2026 we ambitiously had in our Big Bet):
Our "Big Bet" for HVY
"We want to see a 20x return (from our Initial Entry Price of 11.3c) as HVY moves into production by 2026 and becomes a profitable garnet mine"
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is a lot of work to be done and many risks involved - some of which we list below. Success will require a significant amount of luck. There is no guarantee that our Big Bet will ever come true.
What's next for HVY?
🔄 South Australian garnet project (deal with Kantra Copper, formerly Hillgrove Resources)
In our minds this is the closest project HVY has to first garnet production.
Next we want to see HVY complete all of the engineering work needed for a Final Investment Decision to be made on the project.
Then it will be all about seeing how HVY raises the ~A$25-30M for its plant.
HVY has said it’s progressing discussions across project debt, royalty financing, prepay/offtake structures, government grants and equity. (source)
Here are the milestones we are tracking for this project:
- 🔄 Engineering works completed
- 🔄 Secure CAPEX funding for the project
- 🔄 Distribution/offtake deals
- 🔲 Final Investment Decision
- 🔲 Plant build
- 🔲 First production
🔄 Port Gregory (garnet development project in WA)
This is the asset HVY put a PFS out on back in July which demonstrated:
- Net Present Value (NPV) of $322.8M.
- EBITDA of $1.34BN over 24 years.
- Internal Rate of Return of 47.6%.
- A 3.1 year payback,
- Based on $122.1M CAPEX
Here are the milestones we are tracking for this project:
- 🔲 Mining Lease application progress
- 🔲 Offtake and project financing conversations off the back of the PFS.
🔄 Red Hill - maiden resource
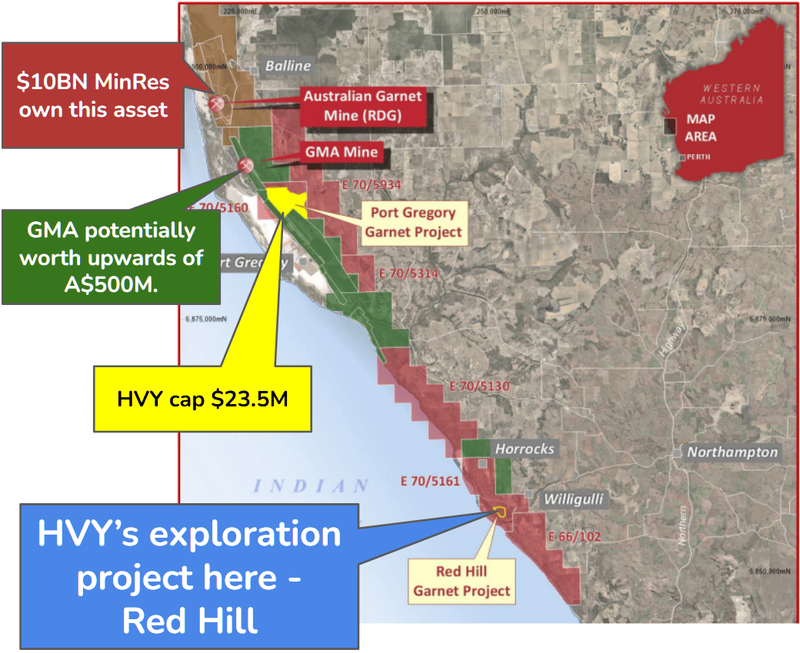
This is HVY’s third asset - an earlier stage exploration asset also in WA, ~37km away from its more advanced Port Gregory asset:
(source)
Here are the milestones we are tracking for this project:
- ✅ Assay/mineralogy results (due this quarter)
- 🔄 Maiden JORC Resource Estimate (HVY expects this in 4-5 weeks from commencement) (source)
What could go wrong?
The single biggest risk for HVY right now is "funding risk".
HVY had $37k cash in the bank at 30 June 2026 and is currently funding itself through an “At-the-Market facility” (~$1.8M undrawn).
It's an unusual funding strategy for a listed company, but HVY has been able to run the company with this (and a royalty funding deal) for over two years now.
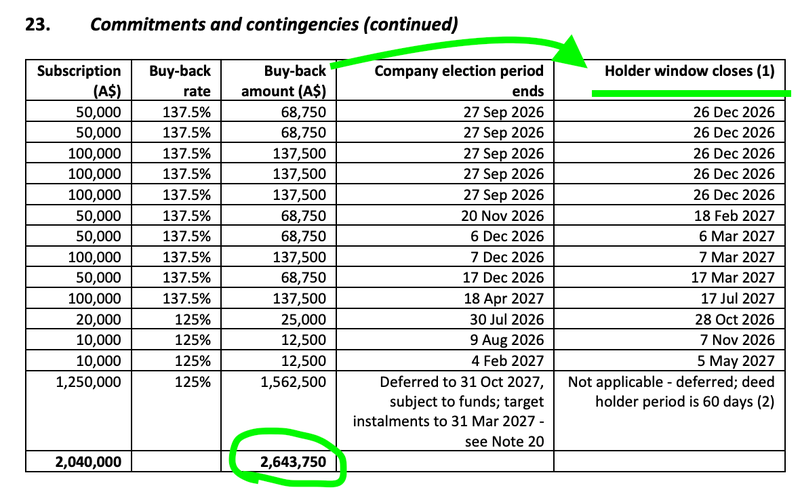
We note HVY has ~$2.6M in royalty funds that are repayable upon the subscribers’ election over the next ~12 months.
HVY put the below note in its 2026 Annual Report showing those ~$2.6M in notes could still be called in by royalty financiers at any time between now and ~October 31 2027:
(source)
There is always a risk, one of these financiers calls in the cash and HVY needs to raise capital to meet that cash call.
This can be done partially with the At The Market facility in place with Acuity Capital, a tool which HVY can use to manage cash requirements.
HVY will also need to find $25-30M for the Kanmantoo plant, and multiples of that for Port Gregory.
The company wants to do this via debt, pre-sales and royalties - but there is no guarantee these funds are secured, and if they are, the terms could dictate how much dilution existing shareholders wear.
If HVY can't secure non-dilutive funding, a traditional discounted equity raise becomes more likely - which would run against the tight capital structure story that has underpinned the share price.
Financing risk
Due to a combination of any or all of the above risks, financing for the project is hard to come by or unavailable, and the project does not become operational.
Source: “What could go wrong” - HVY Investment Memo 14 July 2023
Other risks
Like any small-cap resources company, Heavy Minerals (ASX:HVY) carries significant risk, here we aim to identify a few more risks.
Processing mine tailings presents specific technical and metallurgical complexities that could lead to unexpected recovery challenges or operational bottlenecks. Any engineering or processing issues at the Kanmantoo plant could delay the ramp-up schedule and increase production costs.
Development timelines have already shown signs of slipping past initial target dates. Further delays in securing a Final Investment Decision (FID) or completing plant construction could push back first cash flow and jeopardise management performance incentives tied to production targets.
The overarching commercial model depends on successfully negotiating binding distribution and offtake agreements with global end-users. Unfavourable shifts in global industrial demand or garnet market pricing could directly impact projected revenues.
Managing three distinct projects at different stages across South Australia and Western Australia can stretch operational resources. Balancing exploration work, study progression, and plant development simultaneously creates management bandwidth risks.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our HVY Investment Memo
Our Investment Memo provides a short, high-level summary of our reasons for Investing. We use this memo to track the progress of all our Investments over time.
Click here to read our HVY Investment Memo where you will find:
- What does HVY do?
- The macro theme for HVY
- Our HVY Big Bet
- What we want to see HVY achieve
- Why we are Invested in HVY
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.