BUY: Swing for the fences...?
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 126,041,667 BUY Shares and 41,666,666 BUY Options and the company’s staff own 5,735,294 BUY Shares and 2,450,980 BUY Options at the time of publishing this article. The Company has been engaged by BUY to share our commentary on the progress of our Investment in BUY over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
We Invested in Bounty Oil & Gas (ASX:BUY) because the ASX is starved of big “swing for the fences” oil explorers.
(one of our favourite albeit riskiest types of Investment)
And we liked BUY’s planned acquisition of an offshore block that is going after the same style of targets that delivered multiple multi-billion barrel discoveries offshore in Guyana.
BUY is in the process of acquiring an exclusive right to negotiate a “Production Sharing Contract” on a deepwater offshore oil and gas exploration block in Liberia.
This is proper deepwater, swing-for-the-fences, high risk, (potentially) high reward frontier oil exploration exposure (my first and favourite - buckle up it will be a ride... and already has been for the wrong reasons after some post deal announcement selling beat up the BUY share price - more on that later.)
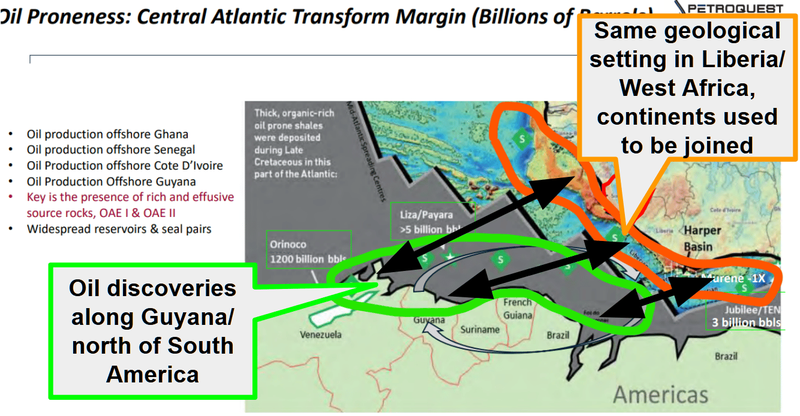
Liberia is on the west coast of Africa, and the offshore geological profile happens to be almost identical to the eastern top of South America - in particular offshore Guyana.
Offshore Guyana is one of the world’s newest oil hotspots, delivering over ~13BN barrels of discoveries since 2015.
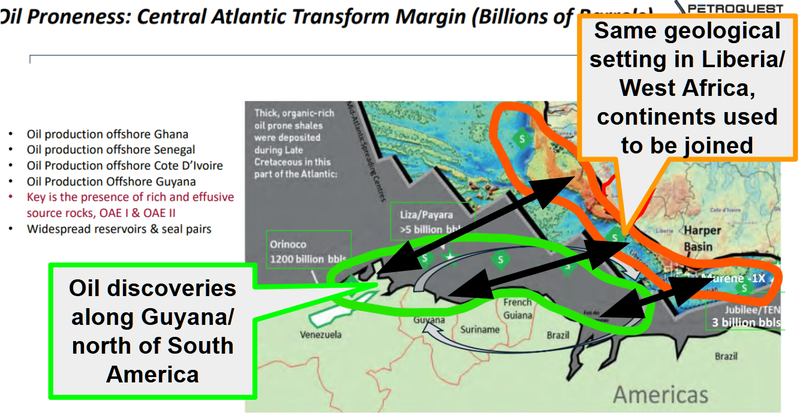
The geological thesis is that BUY’s offshore Liberia block holds the same style of target that delivered the big discoveries offshore in Guyana:
Offshore Liberia and offshore Guyana are known as ‘tectonic conjugate margins’.
Liberia and Guyana were directly connected as part of the supercontinent Gondwana until they began rifting and pulling apart between 120 and 100 million years ago.
Here’s what the geology looked like 100+ million years ago (when the continents were next to each other):
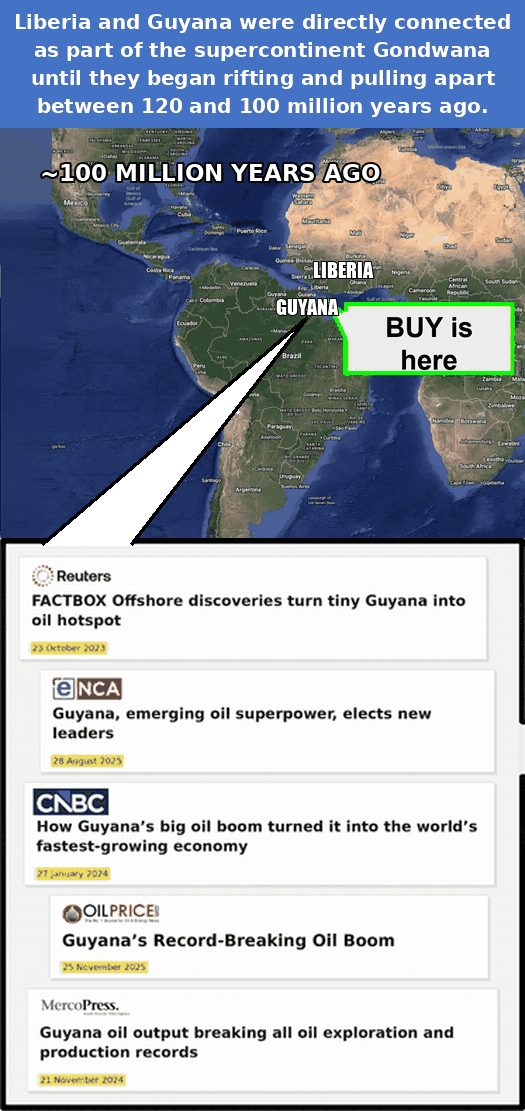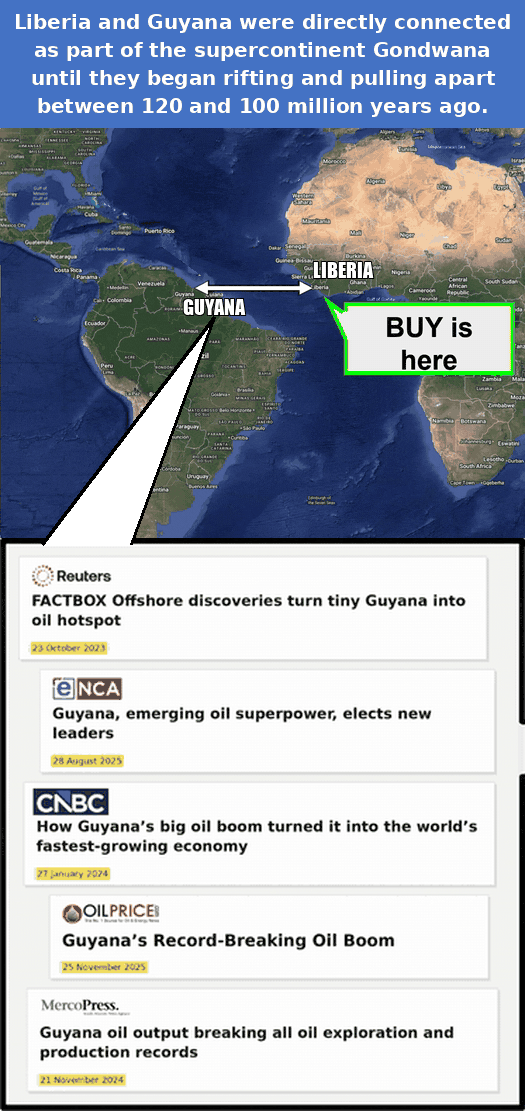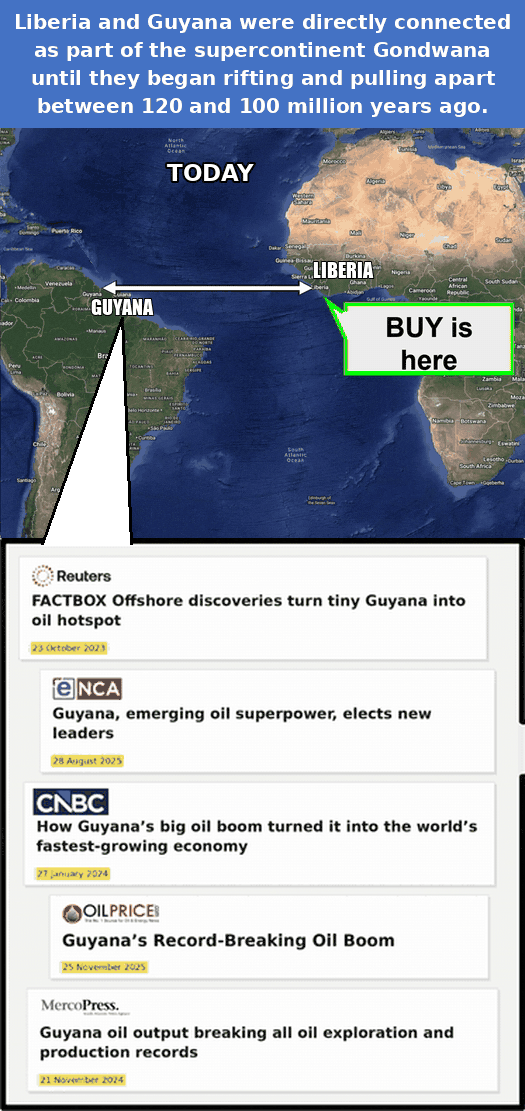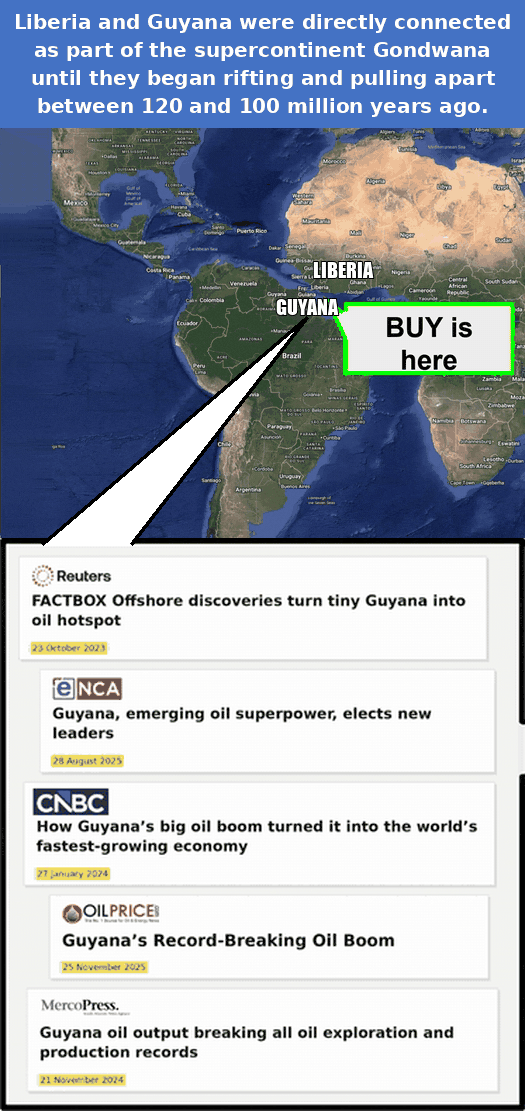
(source)
So far, it’s been a rough start for BUY’s share price.
BUY is currently trading at 0.5c which is lower than before the Liberia deal was announced – you can see our commentary on what we think happened here (what happened with BUY share price).
We hope most of the post project acquisition BS is behind us - and the remaining conditions precedent to the deal are sorted over the coming weeks.
(like the T2 placement, shareholder approvals and DD - more in the risks section later in the note).
Despite the short term share price pain, we haven’t sold any BUY shares - it's way too early here - we have Invested in BUY with a time horizon of a couple of years, as ultimately we are here for a drilling event and (hopefully a big discovery).
Something a little more positive though...
THIS MORNING: BUY put out an announcement on interpretation of 3D seismic data and is saying that early:
"significantly exceeds initial expectations".
Initial expectations which would have been based on a report prepared by the block’s vendor’s where the vendor’s geo team was estimating...
... the block could contain ~4.5BN barrels of “OOIP” (Original Oil In Place), unrisked, based on the screening volumetrics:
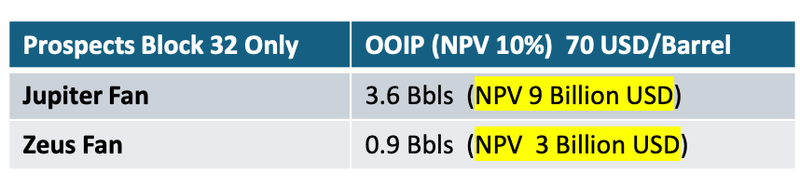
(source - this giant 127 page technical report for the project)
BUY is capped at ~$12.8M (once all the acquisition shares are settled) at 0.5c per share.
(there are also 1BN milestone shares for the vendors, only issued if an independent report and a farm-out hit agreed hurdles - at 0.5c that would take the cap to ~$18M)
BUY also (sort of) confirmed the vendor’s thesis that the block BUY is negotiating on could be an extension of the structures on the $294BN TotalEnergies block next door.
Yes, the block BUY is planning to acquire is supposedly an extension of one of the targets inside Total’s block which are estimated to contain ~7.3 billion barrels of oil equivalent. (source)
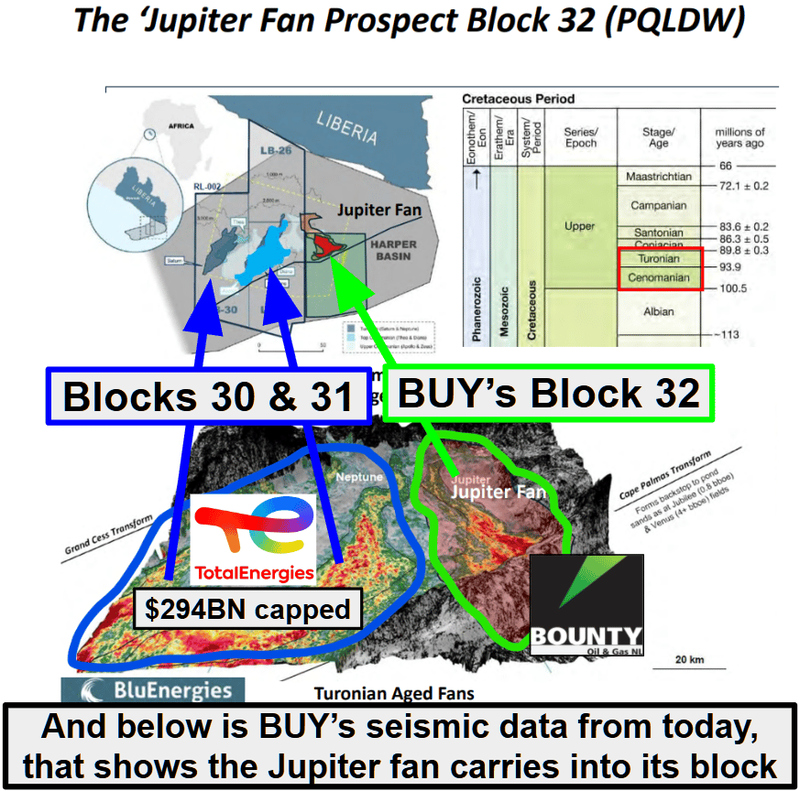
(source)
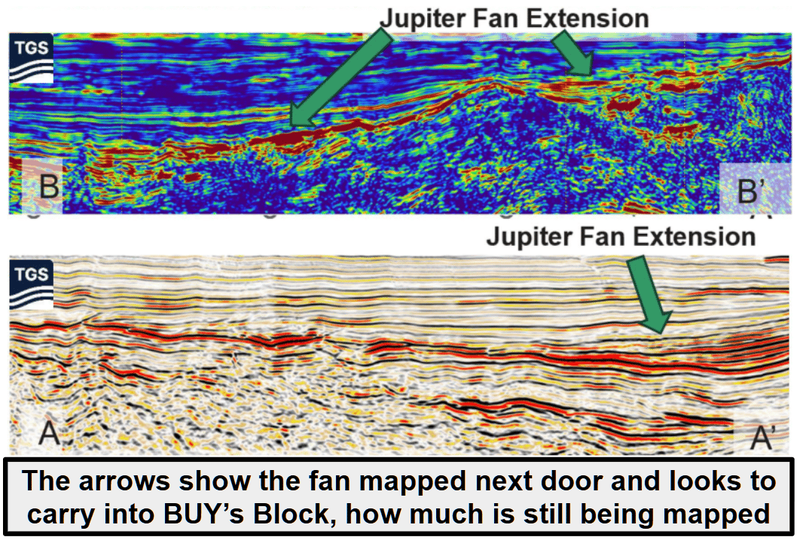
And here is BUY's own seismic from the announcement today which shows the Jupiter fan carrying on into its block:
(source)
So the main thing that was inferred from the vendor’s mega report (based on no seismic data).
BUY is now starting to confirm - after only a first pass LOOK AT 3D seismic data on ~25% of the licence area.
We now know the main target DOES actually cross into BUY’s block - seismic shows the eastern portion of the “Jupiter” fan extends into the block.
(how much of it, and whether it forms a trap, is still being mapped)
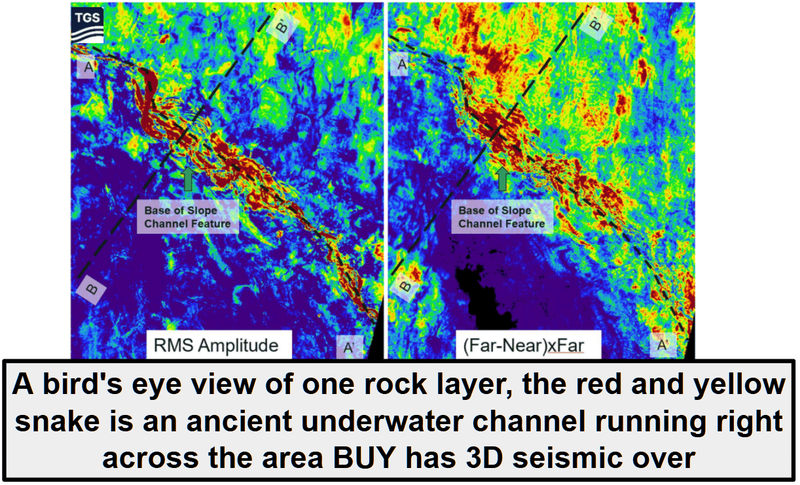
(source)
Technical stuff those images - but after looking at them for decades you start to think you know what you are doing.
(looking for “flat spots” and colourful bits in the images)
The colourful bits = “amplitude anomalies” = unusually strong reflections.
BUY says several of the leads have them.
Flat spots = POTENTIALLY where the oil or gas and water meet - which is why oil nerds get excited about them.
BUY says some reflectors “may be sub-horizontal in depth”. (source)
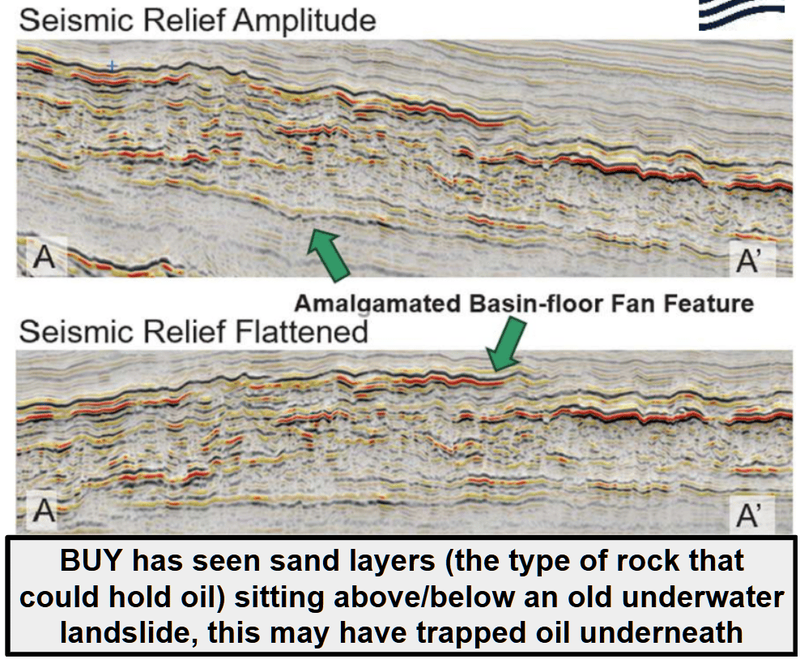
(source)
In total BUY found four leads, including a channel BUY calls “previously unrecognised”.
Okay, so technically the seismic is showing more than the vendor’s report had...
So, why has BUY’s share price done nothing but come down - now down ~70% since the close on the day we launched our initiation note?
We think it's a bit of a combination of the shitty market - where even good news is being sold into and anything with no news, or slightly heavy selling just gets compounded with even more selling.
(fear of getting stuck... holding shares in small cap stocks).
The positive for us as long term investors is that the underlying business doesn't really change no matter what happens with share prices.
And we still really like the block BUY is acquiring - more on the geology and why we like it in a second.
For now though, the capital market’s sentiment (really bad) and ASX small cap paper hands win.
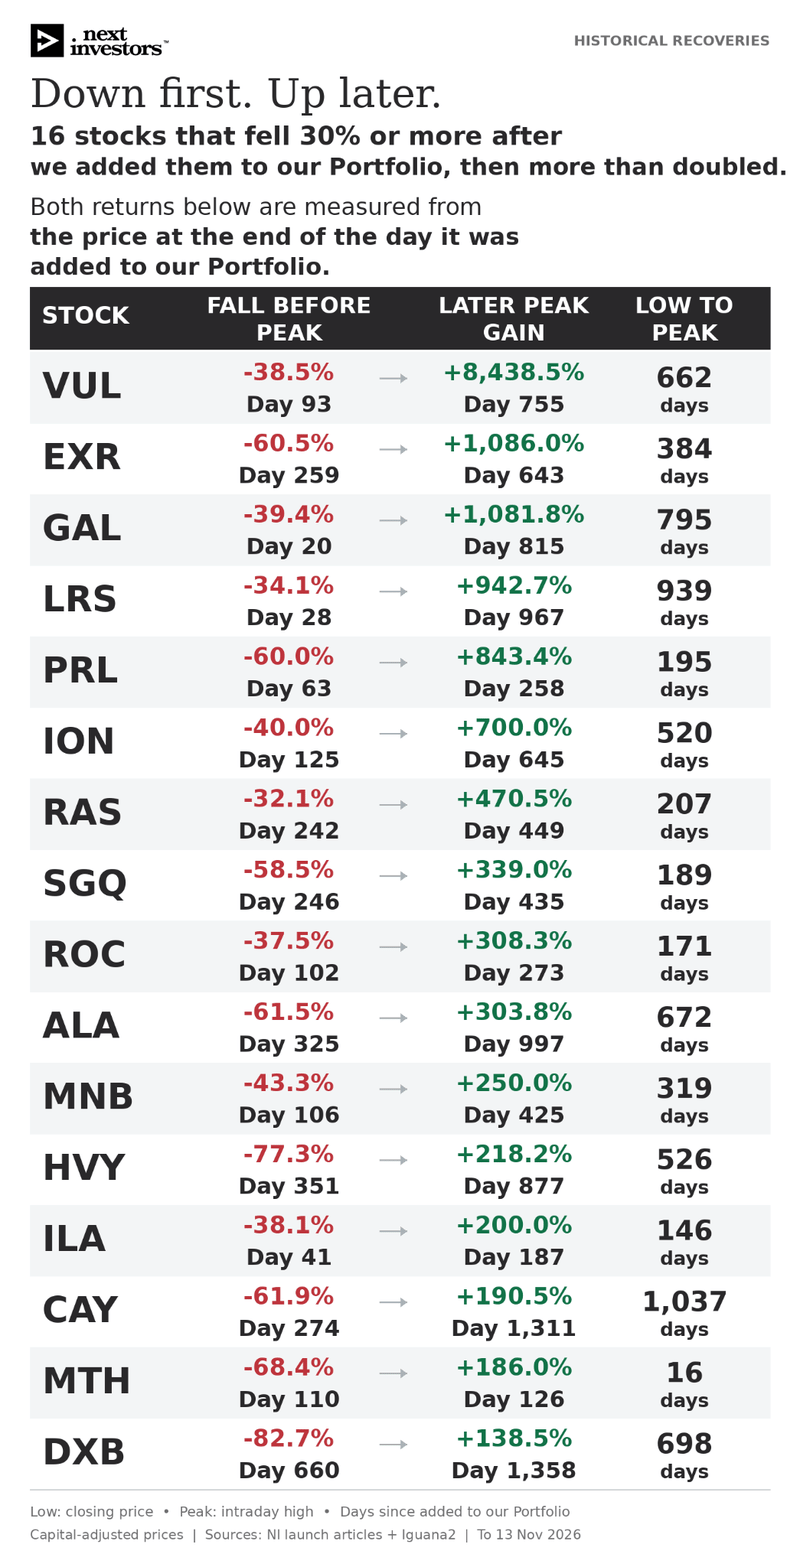
In our Saturday email we shared a list of 16 of our Investments that fell 30% or more after we added them to our Portfolio... and later ran to highs above where we added them:
(source)
NOTE: Not all stocks recover. We've had stocks in our Portfolio that fell and have stayed down, and some may never recover. The image above highlights the comebacks, not our full track record. It shows that stocks can recover, not that recovery is the rule or something to count on. Past performance is not a reliable indicator of future performance.
We are hoping that BUY can work its way up and into that list of stocks...
Whether that happens inside the next 30-60-90 days, or in a few years we won't know...
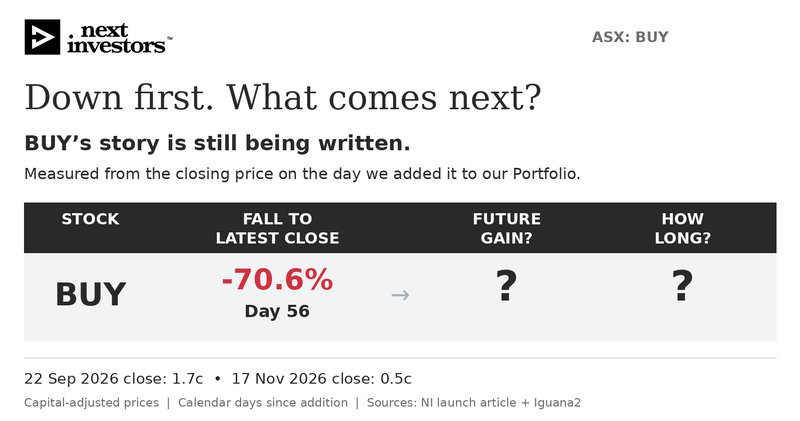
Ultimately though, we are Invested in BUY for the long term to hopefully see a well drilled on a multi-billion barrel target, with all the typical, value building activities and share price catalysts along the way.
Any drilling event is probably at least 2 years away.
Between now and then we think BUY has four clear catalysts that could re-rate the stock:
- Reprocessed seismic data - squiggly lines on an image, where we want to see things like “flat spots”, “AVO’s” and “DHI’s” - all clues of potential oil locations (ask your AI chatbot what these are).
- An ASX compliant prospective resource estimate - this is when we find out how big the targets really are for the first time based on 2D/3D seismic data.
- The Production Sharing Contract (PSC) being awarded - converting the letter of engagement into a Production Sharing Contract. The vendor has advised BUY that this could happen as soon as January 2027.
- Then the big one, a farm-out to a partner to fund the first well.
We think BUY COULD have all of the above ticked off within the next 12 months (assuming nothing goes terribly wrong and the oil price is high enough for a farm-in deal to get done).
We think that oil prices will no doubt have the biggest impact on how attractive a deal BUY can cut when the farm-in discussions begin.
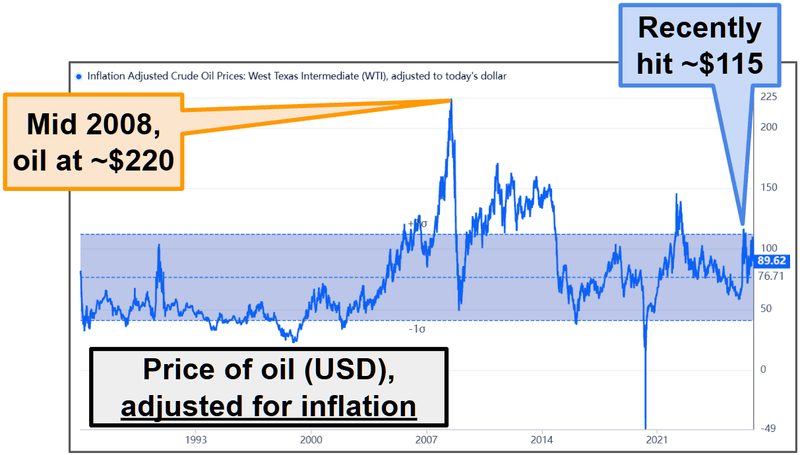
If all of the disruption in the Middle East continues any longer - we think the oil price could really start to take off...
...like it did the last time the Middle East supply went offline - keep in mind we are nowhere near those inflation adjusted peaks yet - to go past those oil would need to go through US$220 per barrel:
(source)
Past performance is not an indicator of future performance. Commodity prices are volatile and can fall as well as rise.
No matter what happens, at oil prices above US$70–80 a barrel, big swing-for-the-fences exploration is still very attractive.
Especially when it's not in the Middle East.
Why Liberia why now?
BUY is acquiring an exclusive right to negotiate a “Production Sharing Contract” on a deepwater offshore oil and gas exploration block in Liberia.
Liberia is on the west coast of Africa, and the offshore geological profile happens to be almost identical to the eastern top of South America - in particular offshore Guyana.
(The vendor’s thesis is actually that BUY’s block holds the same style of target behind the big discoveries offshore in Guyana)
Offshore Guyana is one of the world’s newest oil hotspots, delivering over ~13BN barrels of discoveries since 2015. (source)
Offshore Liberia and offshore Guyana are known as ‘tectonic conjugate margins’.
The regions that are now Liberia and Guyana were directly connected as part of the supercontinent Gondwana until they began rifting and pulling apart between 120 and 100 million years ago.
And so there could be a chance that the same offshore oil discovery success had in Guyana can be replicated in Liberia:
(source)
There have been a few waves of exploration in the past trying to unlock offshore Liberia (and there has been some success) BUT no one has made a commercial discovery YET.
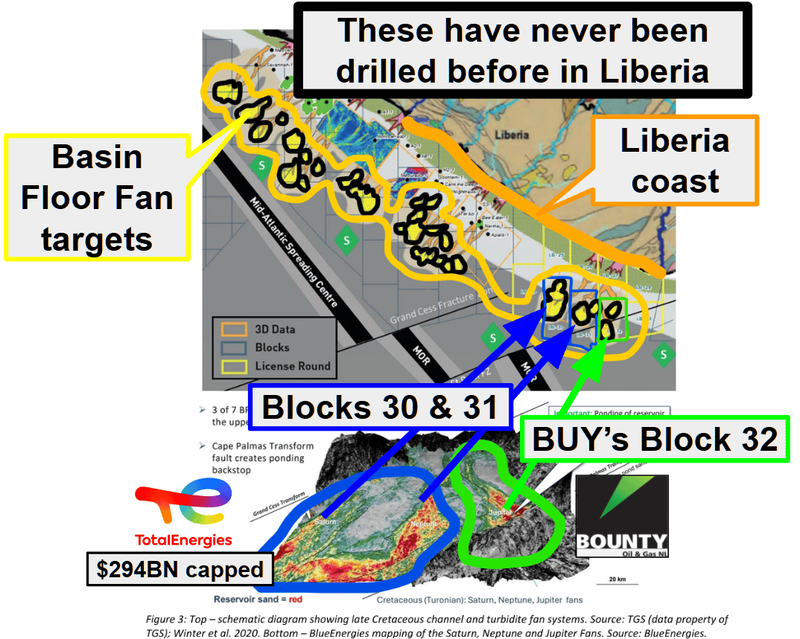
None of that previous drilling was on the deepwater Guyana style targets in deeper offshore Liberia - those have NEVER been drilled before.
All of the supermajor activity now is chasing those deepwater targets.
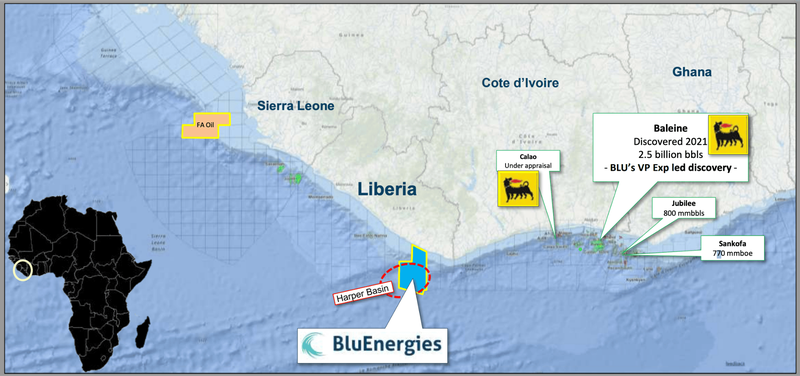
The energy supermajors who flooded to offshore Guyana and delivered multi-billion barrel discoveries have now started piling into offshore Liberia.
Here is what offshore Liberia looked like in 2024:
(source)
And here is what it looks like now:
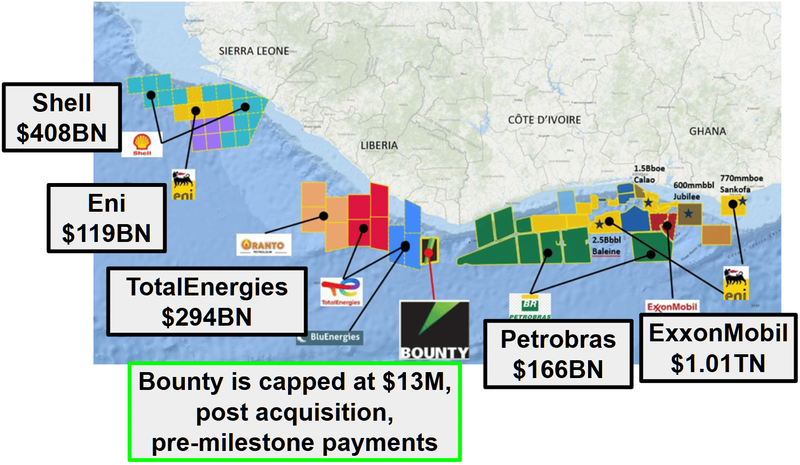
(source)
This is proper deepwater, swing-for-the-fences, high risk, (potentially) high reward frontier oil exploration exposure (my first and favourite - buckle up it will be a ride...)
In a frontier basin that has yet to be opened up.
And BUY will have the exclusive right to negotiate a Production Sharing Contract (PSC) on a block with a potential multi-billion barrel target.
As mentioned earlier, the vendor’s technical report suggests that the block BUY is negotiating on could contain ~4.5BN barrels of “OOIP” (Original Oil In Place), unrisked, based on the screening volumetrics.
(source)
Some caution is needed here - it is the vendor’s exploration team quoting those massive numbers - so it's not independent and it wasn’t put together using any seismic data - so it will likely change once BUY does further work and releases an ASX compliant resource estimate.
Here is the geological reason why supermajors might be interested in BUY’s block
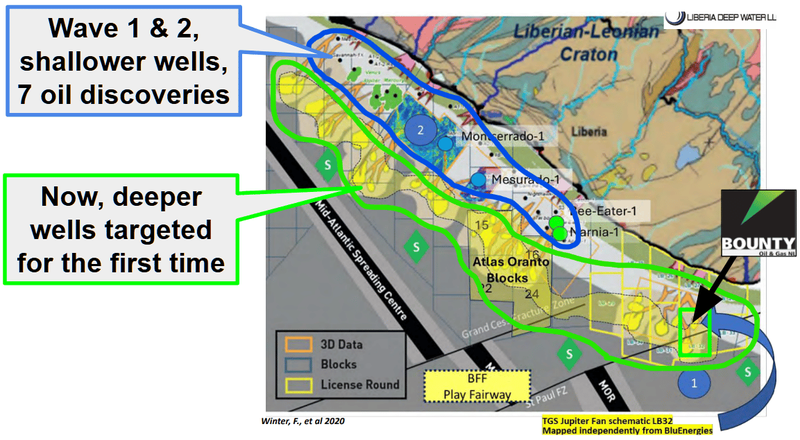
Historically there were two waves of exploration in Liberia:
Wave one: 1970s-80s where wells hit oil shows but no commercial discoveries were made.
Wave two: 2009-2016 where ~15 wells were drilled.
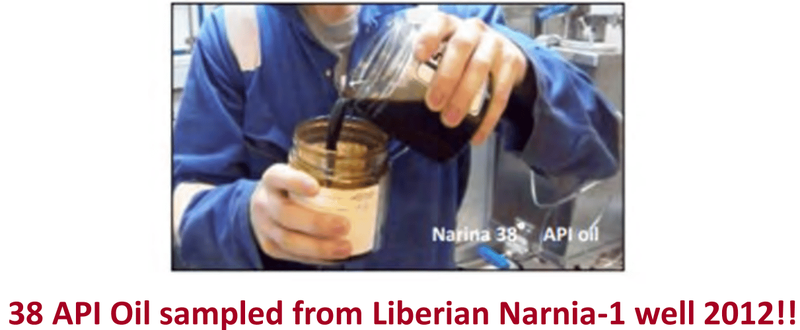
A few of those in wave two had decent oil shows (like the Narina-1 well with 32m of net oil pay) - but none were commercial discoveries.
(source)
The thing is that all of that drilling was on shallow close to shore targets sitting in ~1,000-2,000m deep water - mainly because that was considered ultra-deep water in the 2000’s and early 2010’s.
No one was drilling beyond that - because rigs literally couldn't do it.
(source)
Now supermajors are drilling in 3,000m+ water
Then in 2013, ~6,167km2 of 3D seismic was shot over the deeper-water target areas in ~3,000 to 4,000m of water.
Drill rig technology also improved in that time - by February 2013, rigs were drilling in 3,000m deep water. (source)
Then by 2016 - drilling in ~3,400m deep water. (source)
But the real reason the supermajors started dropping US$100M+ wells on deepwater targets was because of what happened in offshore Guyana in 2015.
In May 2015 Exxon made the Liza-1 discovery offshore in Guyana.
Then over the next 11 years over ~13BN barrels of oil equivalent have been discovered offshore in Guyana.
Then in 2022 TotalEnergies (yes the same TotalEnergies next door to the block BUY will be negotiating a license on) drilled Venus-1X offshore Namibia in ~3,000m of water and made a giant discovery. (source)
All of a sudden - the supermajors' attitude towards these ultra deep water targets had changed.
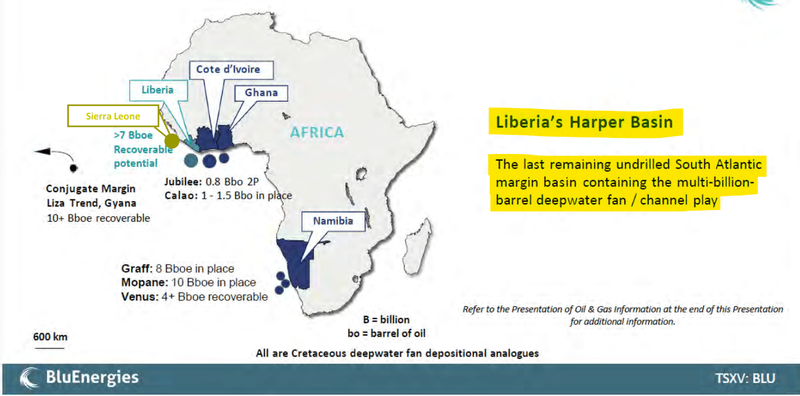
Now, the current wave of exploration offshore in Liberia is going after the same geological system that those ultra deep water discoveries were made in.
Called “basin floor fans” on the “South Atlantic Margin Basin” - like Guyana.
Liberia’s deep water targets are the last remaining undrilled deepwater targets across that structure.
(source)
Geologically the deep water changes things too (in a good way)
So, WTF is a “basin floor fan”? We didn't know until we went down the rabbit hole on that 127 page technical report either.
But deep diving on the Guyana example - it started making sense to us.
- Guyana before Exxon’s 2015 discovery had decades of failed “shelf” and “slope” wells.
- Guyana after Exxon’s 2015 discovery = 51 discoveries and over ~13 billion barrels discovered.
- What changed: someone finally drilled the “basin floor fan” targets...
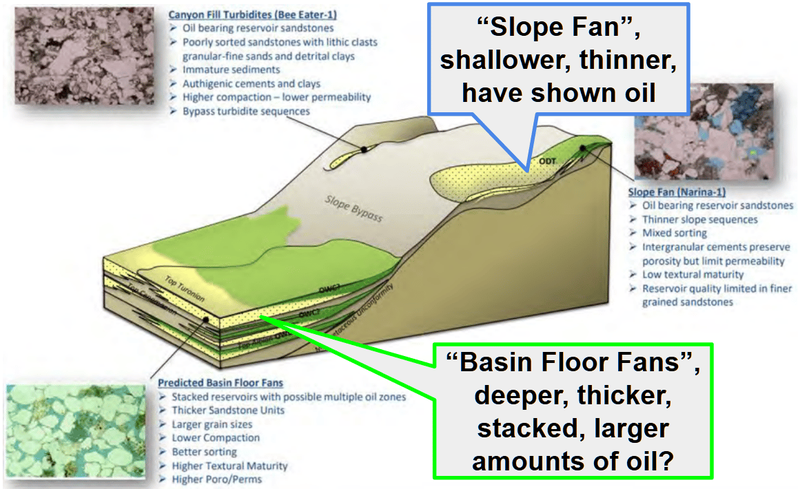
All the drilling in Liberia up to now has been on “slope fans” too.
The deeper water “basin floor fan” targets are UNDRILLED.
Even though, more than ~50% of discovered resources across offshore Africa came from just ~12 basin floor fan wells (versus over 115 on other targets).
We are not geophysicists, but looking at the image below - basin floor fans do look A LOT bigger AND are supposedly meant to solve all the technical risks that “slope fans” have.
(source)
Here are those Basin Floor Fan targets all across the deepwater in Liberia:
(source)
Now with this new way of looking at these ultra deep water blocks - and a way to actually drill them.
The supermajors are coming back into deep water exploration chasing the big elephants - here is that map from earlier again:
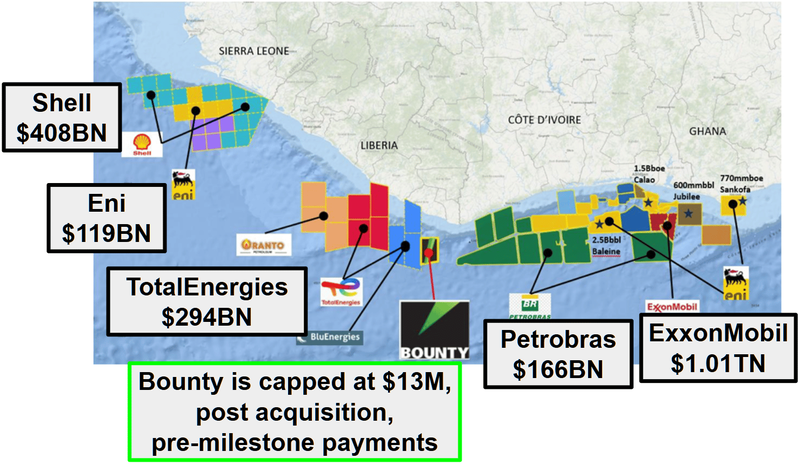
(source)
Based on the work Total is doing next door to BUY, it looks like the first well on those deep targets could also happen next door.
Between now and then, we are hoping one of two things happens:
- Either BUY works its project up to the point where it becomes an attractive farm-out opportunity (realistically for a supermajor like Total, Petrobras, Exxon etc).
- OR Total goes on to make a discovery next door and BUY’s block becomes more valuable on a look through basis.
Before all of that though, we will need to see BUY get a PSC granted over the block.
That is the key risk in the short term.
And of course the big unknown is how big BUY's targets will end up being once the seismic data has been 100% processed and interpreted.
Ultimately, we are hoping those reasons contribute to our BUY Big Bet as follows:
Our BUY Big Bet
“BUY is granted a Production Sharing Contract over its offshore Liberia block, farms the block out and a discovery is made (on or next door to the block) re-rating BUY to a $300M+ market cap”.
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved - just some of which we list in our BUY Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
10 Reasons Why We Are Invested in BUY
Below is a summary of the 10 reasons why we Invested in BUY.
To see the deep dive into each reason, check out our initiation note from 22-Sep-2026 here.
- BUY’s block could have ~4.5BN barrels of speculative “original-oil-in-place"
- BUY’s block has existing 2D and 3D seismic data
- BUY can be farm-out ready relatively quickly
- Liberia’s Guyana style deepwater targets (basin floor fans) have never been drilled before
- The supermajors are coming back into deepwater West Africa
- BUY's block is next door to $279BN TotalEnergies
- BUY has the exclusive right to negotiate the licence - the same position Total was in before it got its blocks.
- We (and the ASX) like big African swing-for-the-fences oil explorers
- Small market cap leveraged to a potentially giant oil target
- The oil price is strong - and we think it wants to run.
Bounty Oil & Gas
What we want to see next from BUY
🔄 Complete the proposed acquisition
- ✅ First tranche of the placement in the bank (7 October)
- 🔲 Shareholder approvals at the AGM (27 November)
- 🔲 Deal conditions satisfied (due 31 December)
- 🔲 Deal completed
🔲 Independent prospective resource
After the deal’s completed we want to see BUY put together a prospective resource estimate across the leads in its block.
Here are the milestones we are tracking on that front:
- ✅ Licence the 3D and 2D datasets
- 🔄 Acquire and interpret seismic data
- 🔄 Detailed mapping of the leads
- 🔲 Targets confirmed (Zeus and Jupiter)
- 🔲 Independent prospective resource
🔄 Production Sharing Contract
At the moment, BUY is acquiring an exclusive right to negotiate a “Production Sharing Contract” on a deepwater offshore oil and gas exploration block in Liberia.
Ultimately, we want to see that exclusivity convert into a Production Sharing Contract.
Here are the milestones we are tracking on that front:
- 🔄 Negotiations with the Liberian regulator and national oil company (BUY said today, it expects this to be completed “in the coming weeks”).
- 🔲 PSC signed and ratified
What could go wrong?
Without a doubt the single biggest risk right now is “Deal risk”.
BUY doesn’t own the block yet.
The deal conditions fall due on the 31st of December (unless both sides agree to extend).
(source)
One big condition precedent for the deal is that BUY either has the Production Sharing Contract signed, or is satisfied there is a confirmed pathway to getting it. (source)
The others include:
- Shareholders voting it through at the AGM on Friday next week (27th of November).
- BUY finishing its technical and legal due diligence (today’s seismic work is part of that).
- The second tranche of the 1.2c placement (we note the current share price is down a lot on that level, so there is risk here)
IF the conditions aren’t met (or extended), the deal may not complete and BUY loses the deal.
Deal and liquidity risk
BUY still needs to complete DD on the blocks and so there is no guarantee this deal completes.
Source: “What could go wrong” - BUY Investment Memo 22 September 2026
Other risks
Like any early-stage exploration company, BUY carries significant risk, here we aim to identify a few more risks.
A lead is not a prospect, and a prospect is not a discovery. BUY’s own announcement says there is no certainty any of the four leads will mature into a drillable prospect, and that bright spots on seismic can occur with no oil present.
The ~4.5BN barrel number is still the vendor’s. Nothing in today’s announcement puts a size on the leads, and the independent estimate could come in a lot smaller.
BUY’s leads sit in ~1,500m to 4,200m of water. A well out there costs far more than BUY can fund on its own - without a farm-in partner there is no well, and BUY will likely need to raise more capital (and issue more shares) before then.
Our thesis assumes a strong oil price. If the Middle East situation gets resolved and oil falls sharply, appetite for frontier farm-ins tends to go with it.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our BUY Investment Memo
You can read our BUY Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
In our BUY Investment Memo, you can find the following:
- What does BUY do?
- The macro theme for BUY
- Our BUY Big Bet
- What we want to see BUY achieve
- Why we are Invested in BUY
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.