BUY is acquiring the exclusive right to negotiate a Production Sharing Contract on a deepwater exploration block (LB-32) in offshore Liberia, West Africa.
BUY's plan is to licence and reprocess existing 3D seismic, define an independent prospective resource, secure a Production Sharing Contract, and farm the block out to a major for drilling.
What is the macro theme?
Oil & gas is back on the market's radar after a couple years in the sin bin.
Small cap O&G explorers are active again and the market is willing to re-rate companies that are progressing assets.
Especially companies that provide exposure to frontier basins with multi-billion barrel potential.
BUY is one of the few ASX-listed companies with a potential multi-billion barrel prospect in frontier offshore basin that hasn’t been opened up YET.
Our Big Bet for BUY
“BUY is granted a Production Sharing Contract over its offshore Liberia block, farms the block out and a discovery is made (on or next door to the block) re-rating BUY to a $300M+ market cap”.
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is a lot of work to be done, many risks involved - just some of which we list in our BUY Investment Memo. Success will require a significant amount of luck. There is no guarantee that our Big Bet will ever come true.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
Why did we invest in BUY?
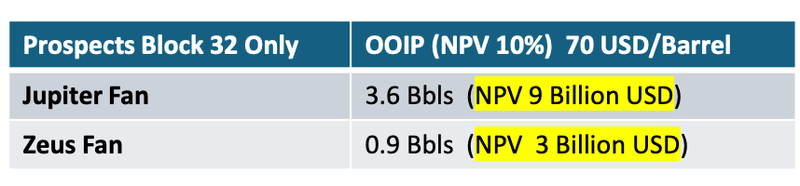
BUY’s block could have ~4.5BN barrels of speculative “original-oil-in-place"
According to a giant 127 page technical report - BUY’s block could contain ~4.5BN barrels of “OOIP” (Original Oil In Place), unrisked, based on the screening volumetrics.
(A ~1.1BN recoverable target - risked by the vendor’s exploration team)
(read it or paste into your favourite AI chatbot here)
That's the vendor's exploration team's number, so they're biased - and it's a screening estimate worked up from the neighbours' published data, not from BUY's own seismic data YET.
BUY’s block has existing 2D and 3D seismic data
BUY’s whole block is covered by 2D seismic data and the corner where BUY’s main target sits is covered by ~6,167km2 of 3D seismic shot in 2013.
That's years of time and we would estimate at least US$50M+ of seismic data costs that BUY won’t have to incur.
The existing seismic should mean BUY can pretty quickly (and cheaply), put together an independently certified ASX compliant prospective resource estimate for its block.
Having 3D seismic is also a big plus because it's usually the minimum any supermajor wants to see before considering drilling a deepwater well offshore.
BUY can be farm-out ready relatively quickly
BUY has THREE clear catalysts to get its project farm-out ready.
We think they are all achievable in a relatively short period of time:
Acquire and re-interpret existing 2D/3D seismic data.
Put together a maiden prospective resource estimate number from that data.
Convert its “exclusivity” into signed Production Sharing Contracts (PSC).
BUY could be farm-out ready right after the PSC is granted OR just before - where it could look to bring in the major partner to go in for the PSC together.
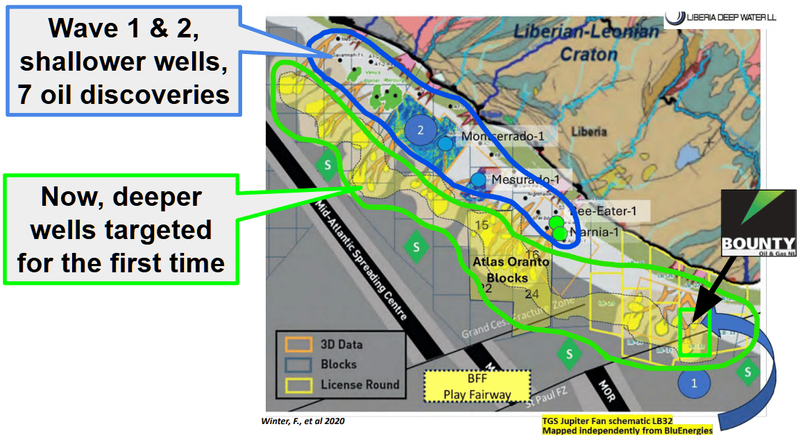
Liberia’s Guyana style deepwater targets (basin floor fans) have never been drilled before
~15 wells were drilled offshore Liberia and Sierra Leone between 2009 and 2016 - all of them on the shallower "slope fans" in ~1,000–2,000m of water.
The deeper "basin floor fans" - the structures responsible for ~11BN + barrels discovered offshore in Guyana and the big discoveries in Namibia - have NEVER been tested offshore in Liberia.
(Partly because drill rigs couldn't drill them before ~2013 AND because no one ever thought to try those targets)
Basin floor fans are typically big - just ~12 wells are responsible for more than half of everything discovered offshore in West Africa.
Offshore Liberia is one of the last basins where these deeper targets are yet to be tested.
The supermajors are coming back into deepwater West Africa
The big mega discoveries in Guyana and Namibia in deepwater has changed the attitude of supermajors for these deepwater targets.
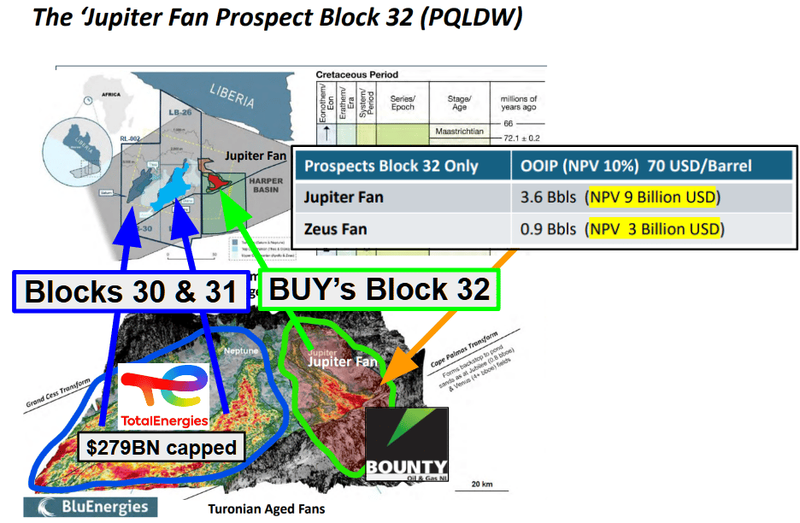
Now we have US$279BN TotalEnergies and Oranto (led by billionaire Arthur Eze) taking blocks on deepwater targets in offshore Liberia.
$914BN ExxonMobil has also been pre-qualified since 2023 and is now reportedly interested in new Liberian blocks. (source)
BUY's block is next door to $279BN TotalEnergies
BUY’s block sits in between blocks held by $279BN Total in Liberia and $187BN Petrobras in Cote D’Ivoire.
Also, again according to that giant 127 page technical report, the block BUY is negotiating a PSC over could be an extension to the Total block next door.
That is the blocks Total’s study partner (BluEnergies) says could contain ~7.3 billion barrels of oil equivalent.
IF Total makes a discovery next door, BUY's block could become a lot more valuable on a look-through basis without BUY drilling a thing.
BUY has the exclusive right to negotiate the licence - the same position Total was in before it got its blocks.
The Production Sharing Contract isn't signed yet, and that's without doubt the key risk.
But BUY is acquiring the company that has a “Letter of engagement” - the same permitting status that Total had before it signed its Production Sharing Contract with the Liberian National Oil Company (NOCAL).
Total went from exclusivity to granted blocks - that's why we're relatively comfortable backing BUY at this stage of the process.
We (and the ASX) like big African swing-for-the-fences oil explorers
With oil and gas, we are always looking to Invest in the big swing-for-the-fence explorers - where the upside is in the billions of barrels.
We had success with IVZ in Africa (our 2020 Pick of the Year).
At its peak IVZ was up 1057% from our Initial Entry Price.
(Past performance of IVZ is not an indicator of future performance.)
On the ASX there is also the Hardman Resources success story - which ended up a ~A$1.5BN takeover.
And other small caps which have farmed-out or had drilling success... we are hoping BUY is another one of those.
Small market cap leveraged to a potentially giant oil target
After today’s raise BUY will be capped at ~$16.4M (at 1.2c with over $4M in the bank).
(Moving up to ~$30M when transaction milestones are achieved and vendors shares issued).
Which gives the company plenty of room to re-rate in the lead up to a farm-out/drilling.
The oil price is strong - and we think it wants to run.
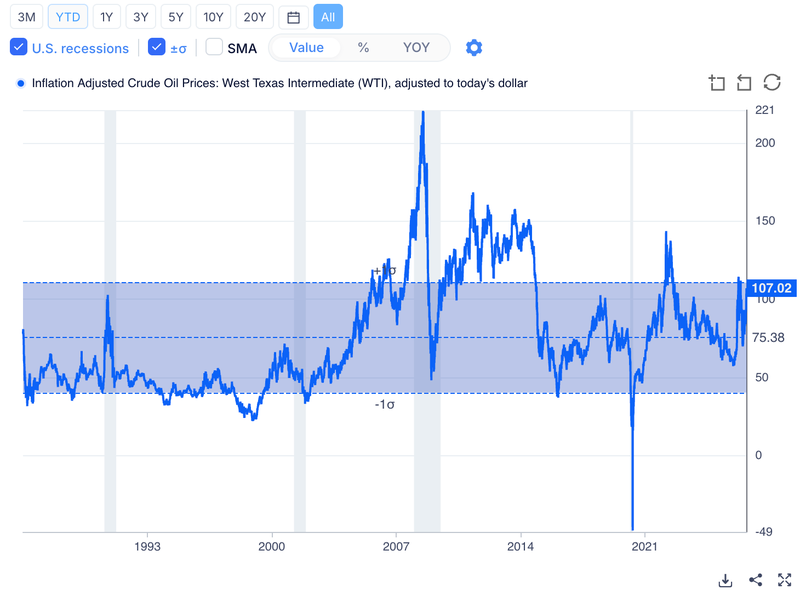
The oil price is rising again at ~US$95 per barrel.
~30% of oil and gas supply is offline or at risk right now because of the conflict in the Middle East.
If all of this Middle East supply stays offline for another few months, we think the oil price could really start to take off...
...like it did the last time the Middle East went offline - keep in mind we are nowhere near those inflation adjusted peaks yet - to go past those Oil would need to go through US$220 per barrel:
(source) Past performance is not an indicator of future performance. Commodity prices are volatile and can fall as well as rise.
At anything above US$70 - 80 a barrel, big swing-for-the-fences exploration is very attractive.
IF oil ends up at US$150 - 200, the companies holding giant undrilled targets are the ones with the most leverage.
What do we expect BUY to deliver?
Objective #1: Complete the LB-32 acquisition
We want to see BUY complete the acquisition of the offshore Liberia block.
Objective #2: Acquire and interpret seismic data
We want to see BUY acquire and then interpret the existing 3D/2D seismic datasets
Milestones
Licence the 3D and 2D datasets
Reprocessing complete
Seismic data results
Targets confirmed (Zeus and Jupiter)
Objective #3: Independent prospective resource
Post-seismic data we want to see BUY announce a maiden prospective resource over its block.
Objective #4: Production Sharing Contract
We want to see BUY convert its “Letter of engagement” over its Liberian block into a Production Sharing Contract
Objective #5: Farm-out and drilling
Ultimately we want to see BUY farm-out the project and lock in a carry on a well
Milestones
Data room opened / farm-out process begins
Farm-in partner secured with a carry through the first well
What could go wrong?
Permitting risk
Right now, BUY’s claim over the offshore block is through an “exclusive right to negotiate”. There is no guarantee BUY will be granted the block. Especially considering it is offshore and BUY is a small cap which may struggle to show financial capacity to retain and explore an ultra deep water block.
Sovereign risk
West-Africa has a history of conflict - Liberia itself is also a post-conflict frontier jurisdiction (civil war ended 2003) with an evolving regulatory framework. There is always a risk of geopolitical instability in the region.
Resource risk
The ~4.5BN barrel “speculative oil-in-place resources” are all estimates of the current vendor based on public data released by BUY’s neighbours.. When the real 3D is reprocessed and interpreted, the targets could be a lot smaller, thinner, or not hydrocarbon-charged at all. An independent evaluator may land on a materially different number.
Exploration risk
Even with a validated prospect, frontier deepwater exploration fails more often than it succeeds - the vendor's own risk is ~1-in-3 for this play type. Oil and gas discoveries on frontier blocks are rare and so there is no guarantee a discovery is made.
Funding and dilution risk
A deepwater well in 3,000–4,000m of water costs US$100M+. BUY as a small cap can’t fund that alone. Without a farm-out BUY may struggle to attract financing to drill its well. Before then there are the signature bonus, data licensing, reprocessing and study costs, and based on the vendor of the project’s previous decks a potential Hybrid 3D Seismic survey (~US$10–20M per the vendor) if the legacy data proves inadequate for well placement.
Deal and liquidity risk
BUY still needs to complete DD on the blocks and so there is no guarantee this deal completes.
Commodity price risk
Our thesis assumes a strong oil price. A reopening of Hormuz and the Red Sea, or a global recession driven by the energy shock, could see prices fall sharply. In that scenario, appetite for frontier farm-ins tends to evaporate quickly when oil falls.
Other risks
Like any early-stage exploration company, BUY carries significant risk, here we aim to identify a few more risks.
The deepwater basin floor fan targets offshore Liberia have never been drilled before, meaning the presence of commercial hydrocarbons remains entirely unproven. The preliminary 4.5 billion barrel estimate comes from vendor screening numbers, and reprocessing the legacy 3D seismic could result in materially smaller targets (and maybe nothing at all).
Finally, operating in post-conflict frontier jurisdictions in West Africa carries inherent regulatory, sovereign, and political risks that could lead to unexpected delays or operational hurdles.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
What is our investment plan?
We are long-term holders and intend to hold the majority of our position for 3 to 5 years, through the seismic, prospective resource, PSC and farm-out milestones.
We will apply our standard de-risking strategy:
We may look to sell up to 20% of our holding if the company delivers on its key objectives and/or the share price materially re-rates, in accordance with our trading and hold policy disclosure.
Disclosure: Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 126,041,667 BUY Shares and 41,666,666 BUY Options and the company's staff own 5,735,294 BUY Shares and 2,450,980 BUY Options at the time of publishing this Investment Memo. The Company has been engaged by BUY to share our commentary on the progress of our Investment in BUY over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.

 Licence the 3D and 2D datasets