Macallum New Energy (ASX:MNE) is an oil and gas explorer with 100% of two exploration permits in the onshore Perth Basin, WA.
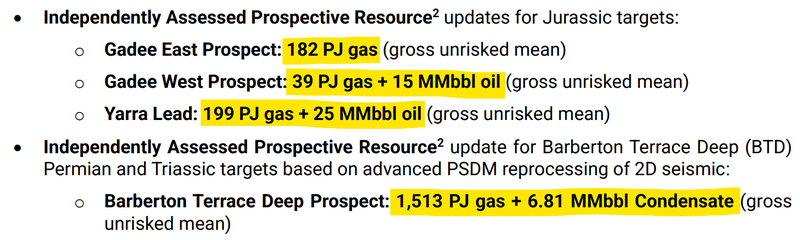
MNE’s targets add up to ~2.3 Tcf of gas and ~93 million barrels of oil (mean prospective, unrisked) across four prospects and two leads.
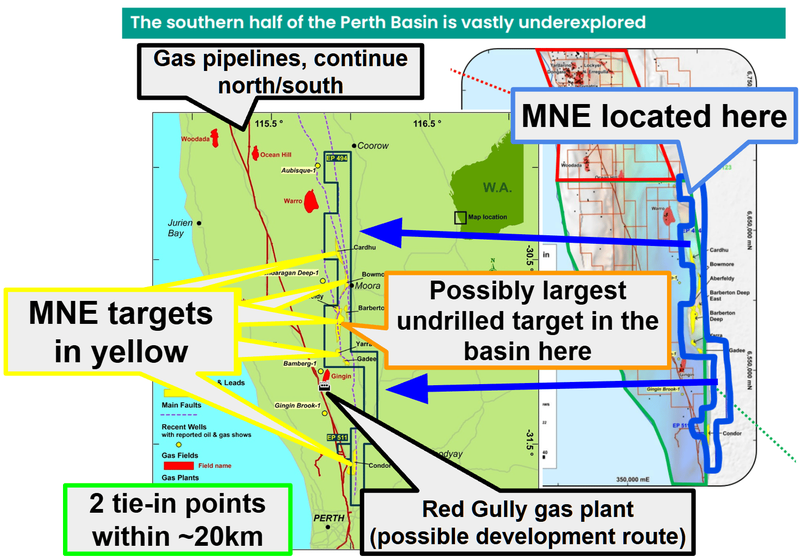
MNE’s biggest target is the ~1.4 Tcf Barberton Terrace Deep prospect which MNE says is possibly the largest undrilled gas target in the whole basin.
What is the macro theme?
Oil & gas is back on the market's radar after a couple of years in the sin bin.
Small cap O&G explorers are active again and the market is willing to re-rate companies that are progressing assets.
The supply shock out of the Middle East has put energy security back on the national agenda - which we think makes assets that are able to supply gas domestically attractive again.
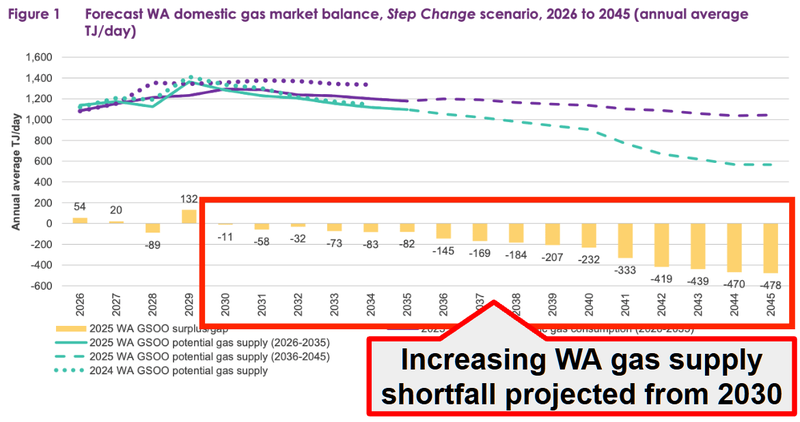
In WA the Australian Energy Market Operator forecasts a shortfall in 2028 and then gaps every year from 2030.
MNE is the only pure-play ASX small cap currently listed and trading with undrilled Perth Basin targets, sitting next to existing gas plants and pipelines.
Our Big Bet for MNE
"MNE makes a gas discovery, re-rates to a $250M+ market cap through a takeover, farm-in or development funding deal at multiples of our Initial Entry Price."
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is a lot of work to be done, many risks involved - just some of which we list in our MNE Investment Memo. Success will require a significant amount of luck. There is no guarantee that our Big Bet will ever come true.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
Why did we invest in MNE?
ASX investors have made money in Perth Basin oil and gas
The ASX knows the Perth Basin really well AND has seen small caps have success with oil and gas there.
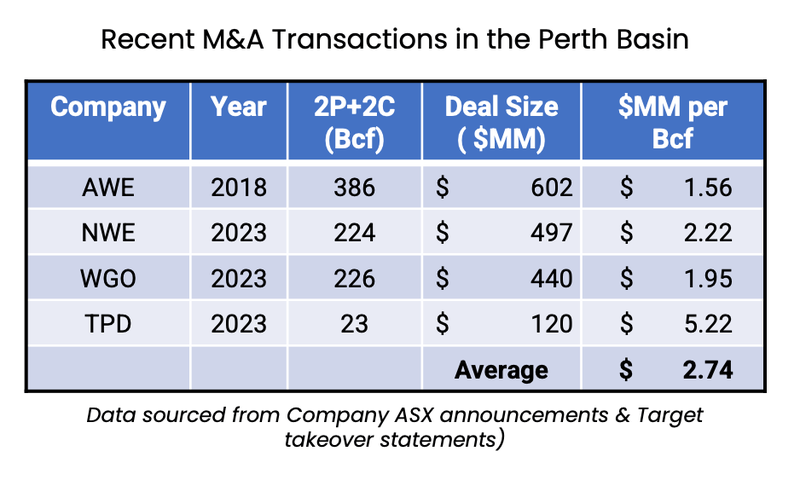
AWE whose discovery in 2014 opened up the Perth Basin was taken over for A$602M.
Warrego for A$440M, Norwest for ~A$497M, Talon for A$142M.
Then Hancock came in and paid Mineral Resources ~$780M cash for its projects.
That's over $2.4BN of takeovers and asset sales since 2018.
MNE is the only pure-play small cap Perth Basin explorer left on the ASX
There is almost no other way to get pre-discovery leverage to the Perth Basin, listed and currently trading on the ASX anymore.
The smallest company besides MNE is ~$357M Strike Energy.
The rest of the players are all multi-billion dollar companies - Beach, MinRes, Mitsui and Hancock.
MNE has a market cap of $22.6M at 14c following today’s raise.
MNE has “possibly the largest undrilled structure” in the Perth Basin - based on 2D and 3D seismic data
MNE has a total of over ~2.3 Tcf of mean prospective gas and ~93 million barrels of oil - all 100% owned, across four prospects and two leads. (source)
(prospective resource = undrilled and unrisked based on 2D/3D seismic data)
MNE also holds what it says is possibly the largest undrilled gas target in the Perth Basin - Barberton Terrace Deep.
That single target alone has a mean prospective resource of ~1.4Tcf of gas and a company-estimated 29% chance of success. (source)
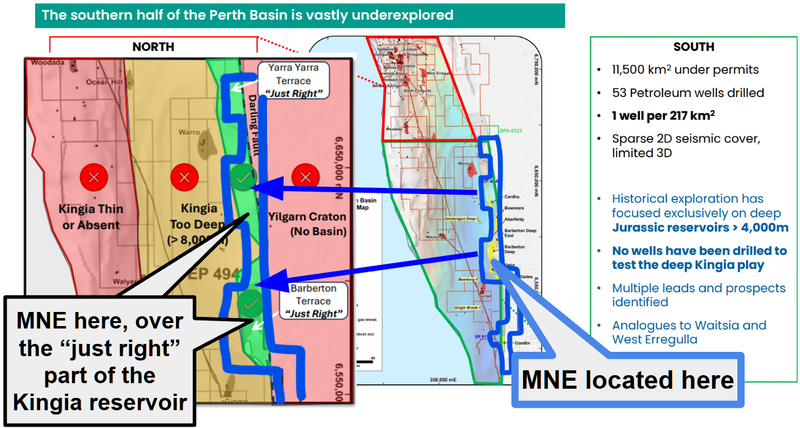
MNE’s targets sit in the same “Kingia reservoir” that delivered the big discoveries in the Northern part of the basin
The “Kingia sandstone” is the reservoir behind every big Perth Basin discovery since 2014.
(Waitsia - AWE which was taken over for $602M, West Erregulla - Warrego taken over for $440M and Lockyer Deep - Norwest Energy taken over for $497M.
Nobody has ever drilled a well to test the Kingia in the southern half of the basin. (source)
MNE's giant 1.4Tcf Barberton Terrace Deep prospect is interpreted to sit inside the Kingia... (source)
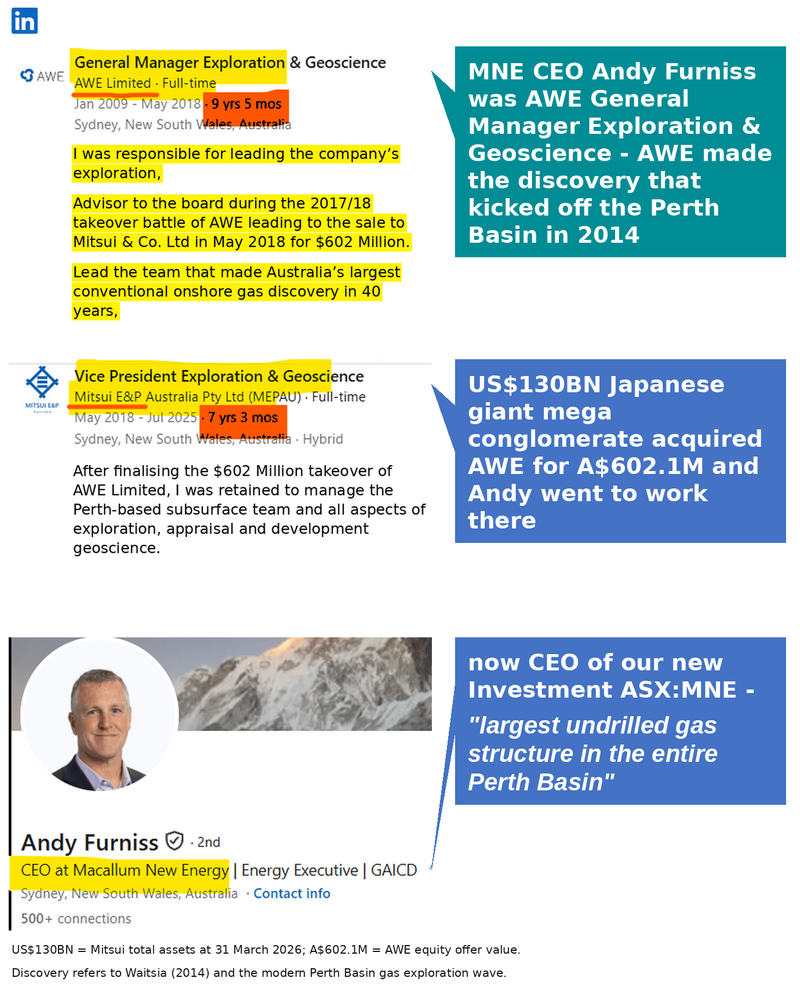
MNE’s CEO led the team that made AWE’s discovery in 2014
MNE’s CEO Andy Furniss was AWE's General Manager of Exploration & Geoscience from 2009 to 2018.
His team discovered the Waitsia field in 2014 - which eventually led to AWE’s $602M takeover in 2018.
He was an advisor to the AWE board through the 2017/18 three-way takeover battle, then spent seven years as VP Exploration at Mitsui E&P - the company that won.
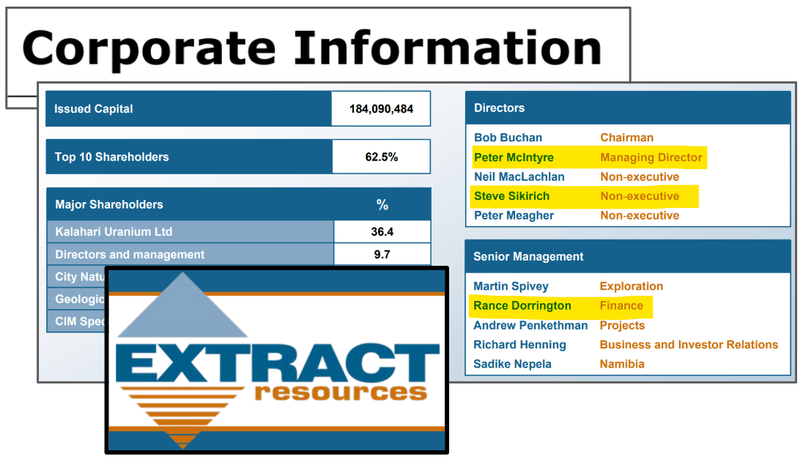
MNE is backed by the guys who built up and sold $2.18BN Extract Resources
MNE's top three holders are “Macallum Group”, the McIntyre family and the Sikirich family. (who between them hold ~29% of the company) (source)
They are the same crew that built Extract Resources - the uranium explorer that discovered the third-largest primary uranium deposit in the world at the time.
AND got taken over for A$2.18BN in 2012.
Peter McIntyre (McIntyre family) was Extract’s Managing Director (source), Steve Sikirich (Sikirich family) was on the Extract board (source) And Rance Dorrington - now an MNE director - was Extract's CFO and Company Secretary. (source)
After Extract, McIntyre, Sikirich and Dorrington set up Macallum Group.
We are backing them to re-run that Extract playbook again - but this time for gas in WA.
MNE has three deep-pocketed neighbours who are active in the basin
We think that IF MNE makes a discovery there are plenty of neighbours who may be interested in whatever is found.
$8.7BN MinRes holds 100% of every permit on MNE's western boundary, has a rig back in the basin, and owns the idle Red Gully plant (which is idle right now) 20km from MNE's targets. (source)
Hancock has paid ~$1.3BN cash for Perth Basin gas since 2023 and wants to build an $850M gas plant. (source)
Mitsui and $2.1BN Beach own the Waitsia plant - whose LNG export permit runs out at the end of 2028, after which it may look for domestic gas to backfill its plant. (source)
$22.6M market cap, a tight shareholder register with leverage to a re-rate
The top 20 shareholders of MNE hold ~71% of the stock (before today’s raise).
About ~34% (after today’s raise) of the shares are escrowed until February 2028 - past the planned drilling window. (source)
We also like that the big holders - Macallum Group’s 18.9 million performance rights only vest if MNE books a resource or drills a well AND the stock holds above 20c. (source)
MNE after today’s capital raise will only have ~161.6M shares on issue too so there aren’t that many shares on issue here.
What do we expect MNE to deliver?
Objective #1: Lock in funding for first well
We want to see MNE fund its first well by bringing in a farm-in partner to finance drilling on its project. Ideally MNE retains >50% of the project post-funding.
Milestones
Farm-out process begins (Data room opened - October 2026)
Offers received from interested parties
Farm-in partner secured, funding up to two wells
(bonus) Alternative funding deal
Objective #2: Well planning and approvals
We want to see MNE lock in its first drill target, receive approvals and start ordering long lead items for its first well in H2-2027.
Milestones
Land access signed for the first Barberton Terrace Deep well (~1.4 TCF target)
Final investment decision on the first well (targeted Q1 2027)
Regulatory approvals received for well locations
Long lead drilling items ordered and received (targeted Q2 2027)
Objective #3: Drill the first exploration well
We want to see MNE drill its first exploration wells in the second half of 2027.
Milestones
First well spudded
Second well spudded
Objective #4: (BONUS): Make a discovery
This is the big unknown success case where (with a lot of luck) MNE makes a discovery. IF this happens, then we would turn our attention to commercialising whatever MNE finds (if it finds anything commercially viable of course).
What could go wrong?
Farm-out risk
MNE is relying on a farm-out partner to fund most of the cost of drilling. There is no guarantee that MNE will be able to find a partner, or attract a farm-in partner on terms that are in line with MNE’s market valuation. Without a farm-in partner secured, the 2027 drilling timeline could also slip.
Funding and dilution risk
MNE is a pre-revenue explorer and IF a farm-out deal can’t be signed, MNE will need to come back to the capital markets to finance working capital AND/OR exploration. IF the farm-in takes longer than expected, MNE may be forced to raise cash to fund the company while it waits for a deal to get done too.
Exploration risk
Oil and gas exploration overall fails much more often than it succeeds. Even though MNE’s own estimated chance of discovery is 29% at Barberton Terrace Deep, 40% at Gadee East and 25% at Aberfeldy, these still imply that each well is more likely to come up bare or uneconomical than not.
Resource risk
MNE’s resources are prospective and unrisked, so they are just estimates of what might be there. Even with a discovery, the volumes could end up being a lot smaller than those mean estimates. MNE has itself said the strong seismic signal at Gadee East may have come from water-filled sands rather than gas, and only drilling a well here will be able to tell the difference.
Commercial risk
Even if a discovery is declared, a discovery doesn’t always result in a commercially viable project. The deeper Kingia gas at Barberton Terrace Deep sits at more than 4,000m, so MNE would need to show strong flow rates to make it worth developing.
Gas price and policy risk
WA’s gas reservation rules are designed to keep local gas prices low, currently at ~A$6/GJ in the spot market earlier this year versus over A$20/GJ seen for Asian LNG. Also, onshore Perth Basin gas can’t be exported after 2030.
There is also a federal government new gas reservation scheme in discussion - which is a big unknown, and could change the incentives negatively for any new exploration in the basin.
Delay risk
MNE still needs to obtain the usual regulatory approvals, land access and drilling equipment for these intended wells. Delays at any stage of these, or on the farm-out process, would likely push drilling back from the current forecast second half of 2027.
Other risks
Like any junior oil and gas exploration company, MNE carries significant risk, here we aim to identify a few more risks.
Targeting deep reservoirs below 4,000 metres requires specialised deep-drilling rigs and contractor equipment that can be difficult to secure in Western Australia. Any shortage of suitable rigs or cost inflation across oilfield services could delay timelines or inflate well budgets significantly.
Commercialising a discovery relies on securing access to third-party infrastructure such as Mineral Resources' Red Gully plant or nearby transmission pipelines. If MNE cannot reach favourable terms for processing capacity or pipeline access with regional majors, monetising a viable gas field could take longer and cost considerably more.
MNE also relies heavily on the specific geological track record of CEO Andy Furniss and the founding Macallum leadership team. The unexpected loss of key personnel could disrupt ongoing farm-out negotiations and slow operational momentum on the ground.
With approximately 71% of shares held by the top 20 and ~34% under escrow until 2028, the company has a relatively low free float. This limited daily trading liquidity can lead to sharp share price volatility and make it harder to enter or exit positions smoothly.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
What is our investment plan?
We are long-term holders and intend to hold the majority of our position for 3 to 5 years, through the farm-out, drilling and any discovery related milestones.
We will apply our standard de-risking strategy:
We may look to sell up to 20% of our holding if the company delivers on its key objectives and/or the share price materially re-rates, in accordance with our trading and hold policy disclosure.
Disclosure: Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 4,103,571 MNE Shares at the time of publishing this Investment Memo. Some shares disclosed are subject to shareholder approval. The Company has agreed to be engaged by MNE to share our commentary on the progress of our Investment in MNE over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.

 Farm-out process begins (Data room opened - October 2026)
 Offers received from interested parties