MNE: Microsoft’s Bill Gates and Anthropic looking for gas in Western Australia to power their AI datacentres?
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 4,103,571 MNE Shares at the time of publishing this article. Some shares disclosed are subject to shareholder approval. The Company has agreed to be engaged by MNE to share our commentary on the progress of our Investment in MNE over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
What does our Investment Macallum New Energy (ASX:MNE) have to do with Anthropic’s IPO?
And rumours in recent weeks of AI datacentre hyperscalers like Anthropic, Microsoft, Google and Amazon sniffing around Western Australia?
Yesterday I was reviewing the just released Anthropic IPO prospectus (maker of Claude AI) - arguably the biggest IPO in history following the SpaceX IPO earlier this year.
The risks section talks a lot about potential gas shortages.
So one of the biggest and most important companies ever, set to IPO with a US trillion dollar plus valuation, is dependent on secure gas supply to power its AI data centres.
NOT having the gas is a big risk...
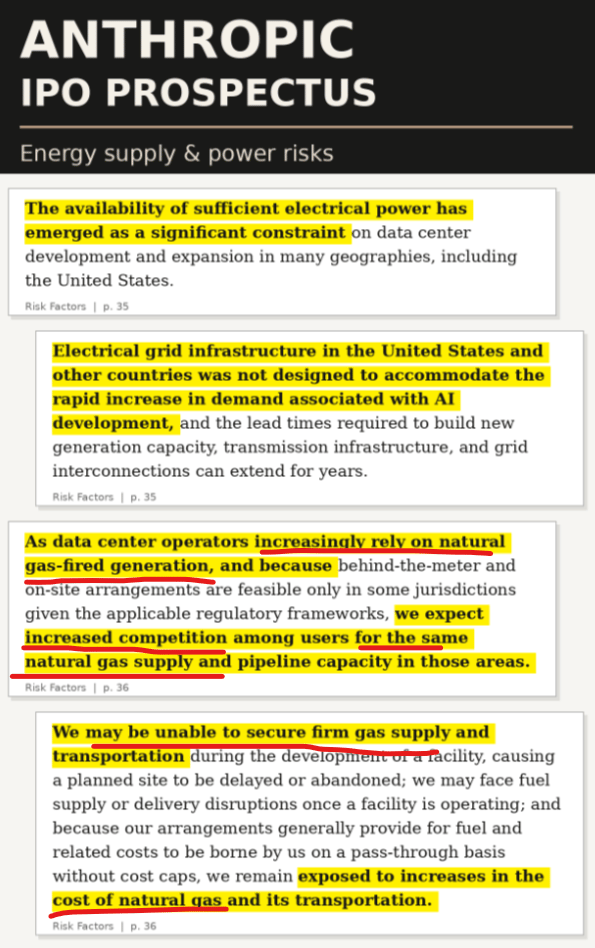
(Anthropic Prospectus - just search for the word “gas”)
SpaceX - another US trillion dollar plus mega company, is also doing a massive and rapid data centre build out.
SpaceX shared similar gas supply risks in their own IPO prospectus a few months ago:
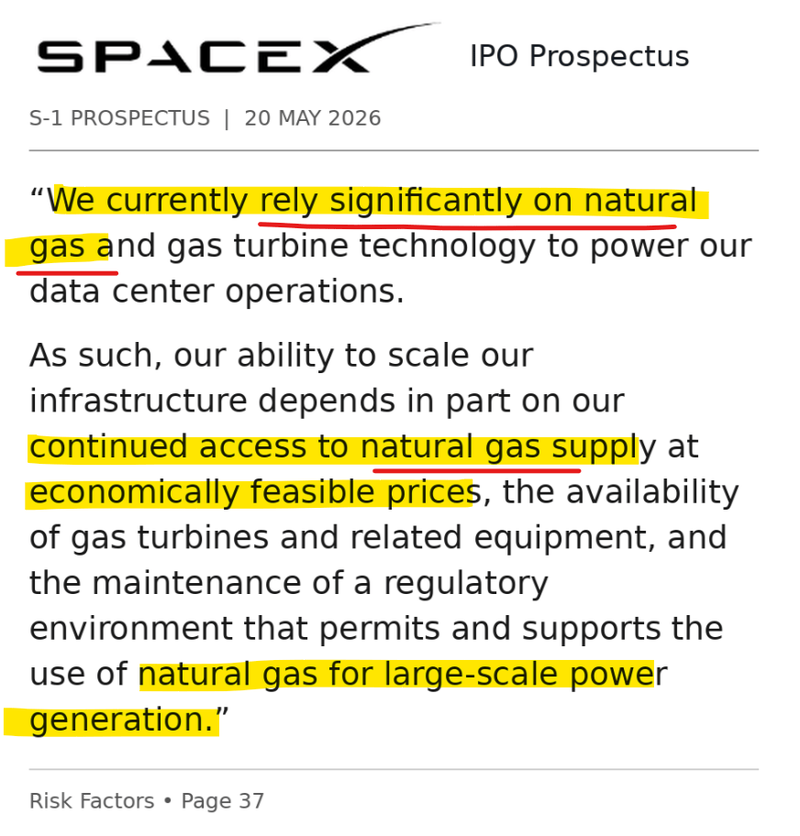
(SpaceX Prospectus - again, just search for the word “gas”)
Data centres are what makes AI happen.
AI workloads require massive computational power, specialised hardware, and continuous infrastructure that standard computers cannot handle - hence the big data centre build out happening across the planet.
(ever lazily put something in ChatGPT or Claude when you could have just as easily googled it? Yep, you are burning much more energy...)
All this means we are going to need a lot of data centres... and a lot of power to keep them running.
Natural gas power supplied 26% of all data-centre electricity globally and over 40% in the US.
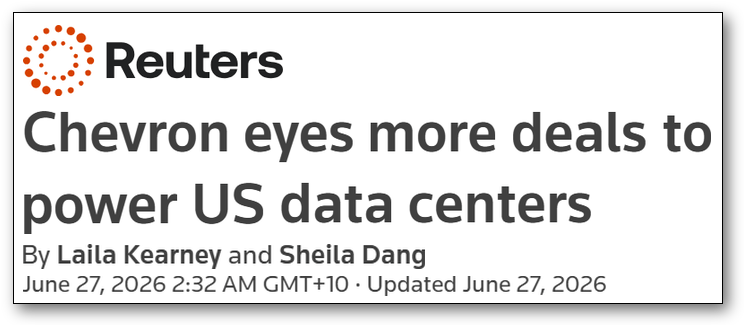
Four months ago, $607BN energy supermajor Chevron did a deal with $5 trillion tech monster Microsoft to build a gas powered generator for its “AI campus” in Texas, USA.
A bet by Microsoft to power its data centre with gas AND a bet by Chevron’s gas division on data centres.
Here is what Chevron’s CEO said when interviewed about the deal at the time:
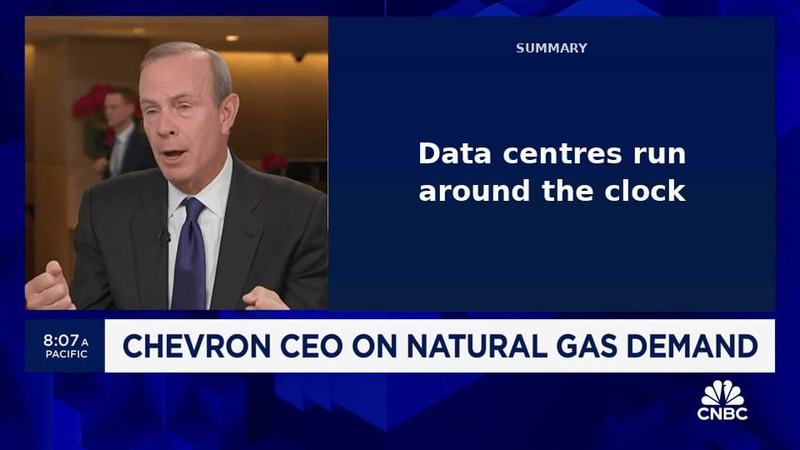
(source)
And here is what was reported after that deal:
(source)
Australian media has been reporting over the last few weeks that AI data centres could be coming to Western Australia... and need gas power.
...with names thrown around like Anthropic, Microsoft, Amazon and Google (all our sources are below)
Our Investment MNE holds 100% of “the largest undrilled gas structure in the entire Perth Basin”, and wants to drill test it for a discovery next year.
MNE is the only pure-play ASX small cap currently listed and trading with undrilled Perth Basin targets, sitting next to existing gas plants and pipelines.
(right in the mix of where this WA AI datacenter power supply talk is all happening)
Remember the "mystery client" that was “driving massive data centre electricity demand” in Western Australia from our first MNE note?
The one behind plans for WA's biggest ever gas-fired power station, reportedly to feed a data centre?
With speculation it could be Google, Microsoft or Amazon?
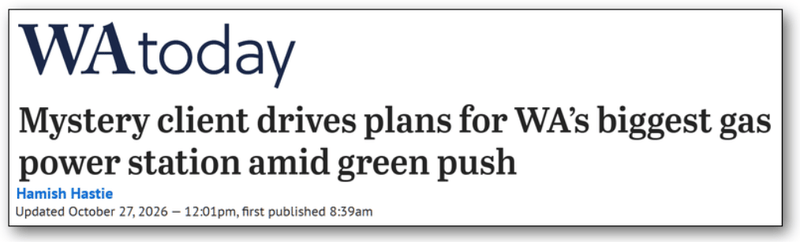
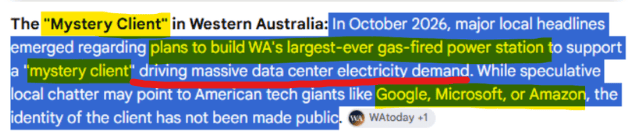
(source - the second box is the google AI summary)
That plant will need a lot of gas... which WA doesn’t necessarily have - the Australian Energy Market Operator was already forecasting WA gas shortfalls starting in 2028 and 2030 and getting worse every year through to 2045. (source)
Just google “WA datacentre rumours”:
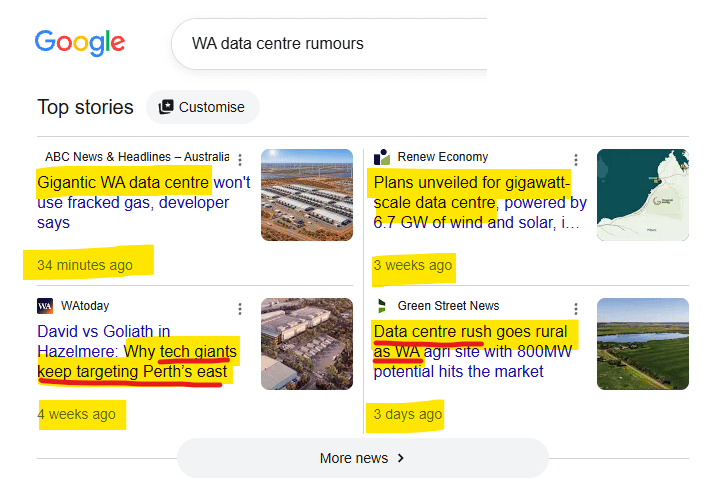
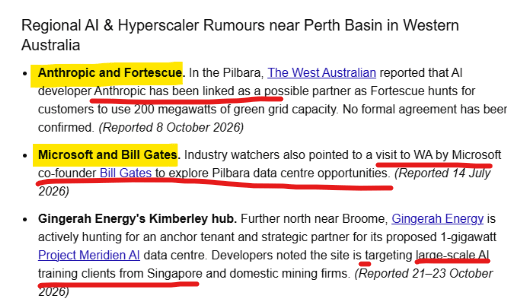
(sources: google: The West, AFR, w.media)
The Australian Energy Market Operator was already forecasting WA gas shortfalls starting in 2028 and 2030, and getting worse every year through to 2045. (source)
IF those data centres get built, then WA is going to need a lot more gas than current forecasts...
Energy supply and natural gas supply is why we just Invested in MNE.
And the big drilling event (or events?) next year.
MNE holds 100% of what it calls "possibly the largest undrilled Permian gas prospect in the Perth Basin".
(again - right in the mix of where this WA AI datacenter power supply talk is all happening)
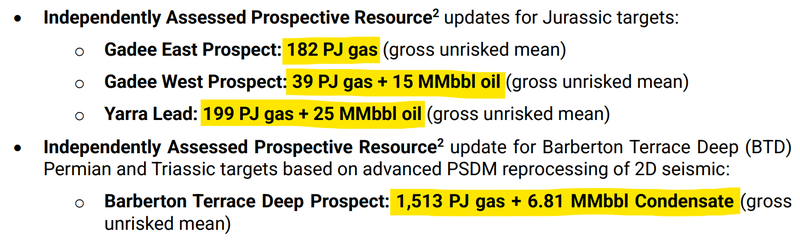
All up, MNE currently has ~2.3 Tcf of gas and ~93 million barrels of oil, undrilled targets, across four prospects. (source)
The single biggest is ~1.4 Tcf - Barberton Terrace Deep target.
MNE’s plan is to drill one (or two) of those targets next year - JUST ahead of that 2028 projected shortage.
MNE currently has a “data-room open” looking for a farm-in partner for the project.
(A farm-in partner is when a bigger oil & gas company pays for all or part of the drilling in return for a share in the project)
Guidance is for a deal to be done in Q1 next year with the farm-out process to run through to the end of this year.
MNE’s goal is to drill up to two wells in H2 of 2027. (source)
🚨 THEN THIS MORNING:
MNE confirmed that well planning had started for THREE possible exploration wells (previously we understood it to be one, possibly two):
- Barberton Terrace Deep (~1.4 Tcf target),
- Gadee East (~170 Bcf target), and
- Aberfeldy (~52.6 million barrels oil + ~50bcf gas)
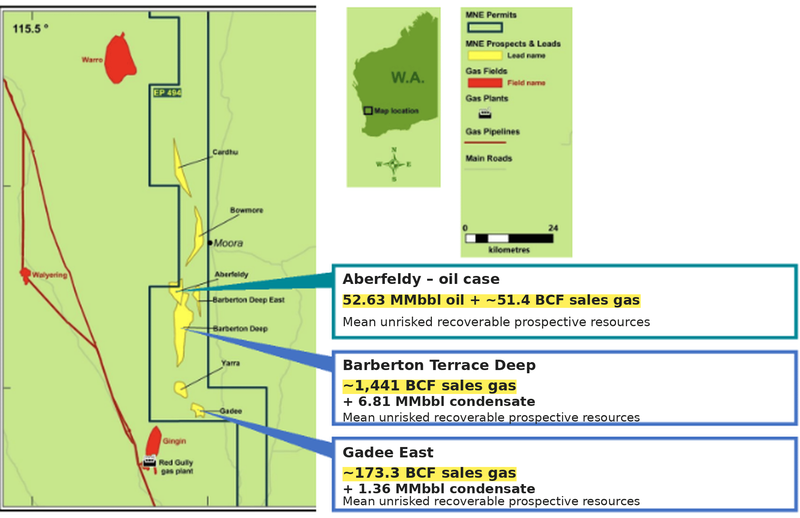
(source)
A discovery across any of those could be company making for the $16.5M capped MNE.
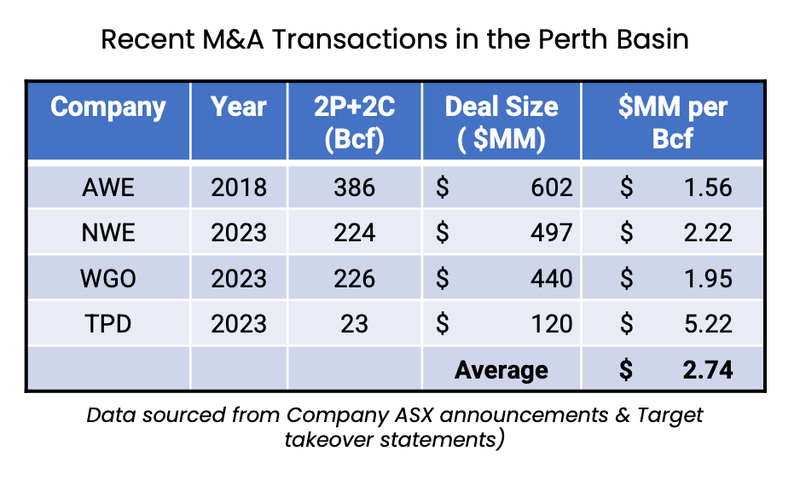
Rule of thumb, any discovery made during the last exploration rush in the Perth Basin was taken over for an average of ~A$2.74M per bcf.
Even on the smallest named Gadee target, IF (and that’s a big IF) discovered, that would be ~$460M+...
No guarantees of course - gas exploration is risky.
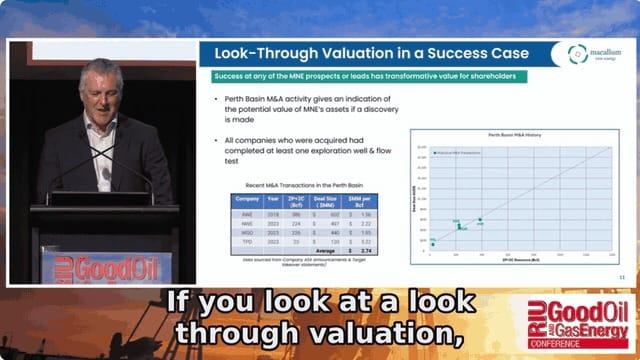
(watch it in full here: MNE investor presentation from September)
Aside from the big energy thematic driving demand for gas, we are Invested in MNE to hopefully see it repeat previous Perth Basin successes - like Norwest Energy which ran from 0.3c to ~7c on its discovery - a gain of over ~2,200% - and was taken out by MinRes for ~$497M. (source)
Or like AWE’s Waitsia discovery in 2014 which started the rush into the Perth Basin (that was taken over for ~$602M). (source)
(the past performance of AWE and Norwest is not an indicator of the future performance of MNE)
Fun Fact: The group MNE engaged to do its well design and planning was the same group who was involved in both the discoveries mentioned above.
(source)
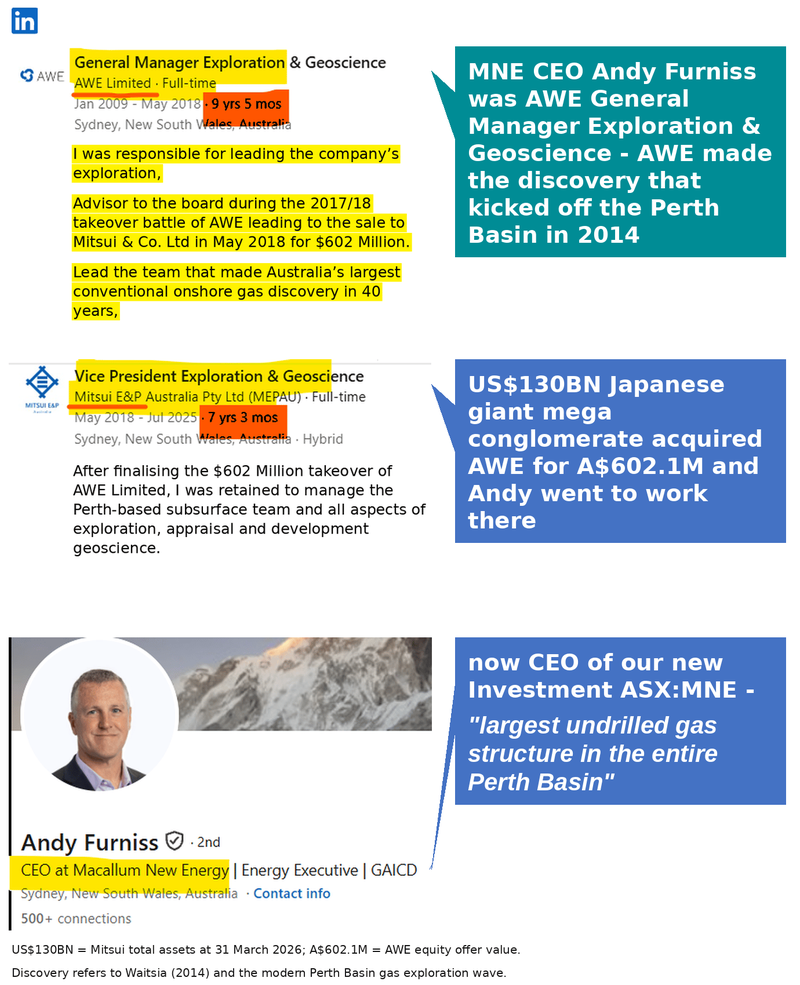
Oh and MNE’s CEO Andy Furniss was the General Manager of Exploration at AWE from 2009 to 2018.
Andy was with AWE all the way through to the eventual $602M takeover.
And then he spent ~7 years as Vice President of Exploration at the company that bought AWE - the Japanese giant Mitsui.
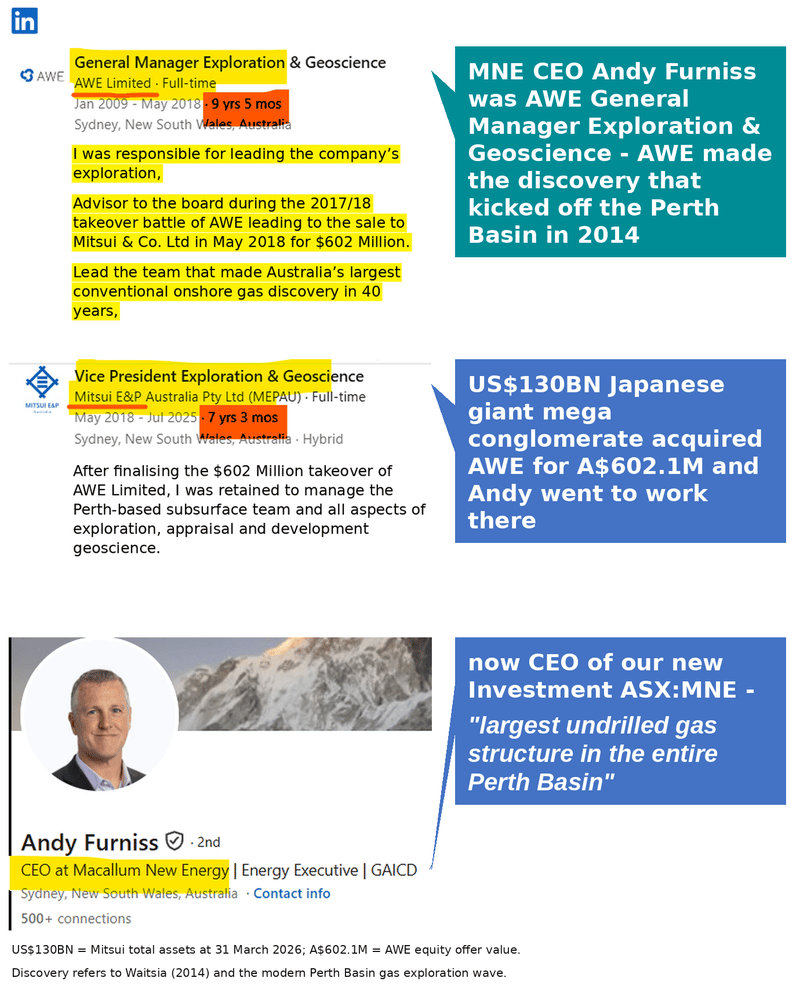
(source - Andy’s LinkedIn profile)
So with MNE, we are Invested in a company with:
- ~2.3 Tcf of gas and ~93 million barrels of oil in undrilled targets - all 100% owned, all in the Perth Basin. (source)
- The exploration manager behind the discovery that opened up the basin - now running MNE, and backed by the same crew that sold Extract for ~A$2.2BN.
We also like MNE’s capital structure too
We mentioned in our initiation note that we’d been following MNE for a couple of years, watching it move from being a private company to an ASX listing in February this year.
What’s surprised us the most is how well MNE’s valuation has held up in an otherwise terrible market.
MNE’s share price is slightly below its 20c IPO - which in today’s market is a solid position to be in.
The thing we liked the most was how well MNE’s share price has held up from the last 14c cap raise.
All of that stock (excluding the stock being allocated to directors) was issued on the 3rd of November, YET it looks like those new guys and existing holders are happy to hold onto their stock.
A refreshing sight... and yet another sign, MNE has managed to build a register of longer term holders who are here for the drilling event next year.
(as opposed to people wanting a 5-10% quick win)
MNE’s top 20 held ~71% of the company’s stock (pre raise) and ~34% of the register (after the last raise) is escrowed until February 2028.
But the main reason we like MNE’s register is MNE's top three holders - Macallum Group, the McIntyre family and the Sikirich family.
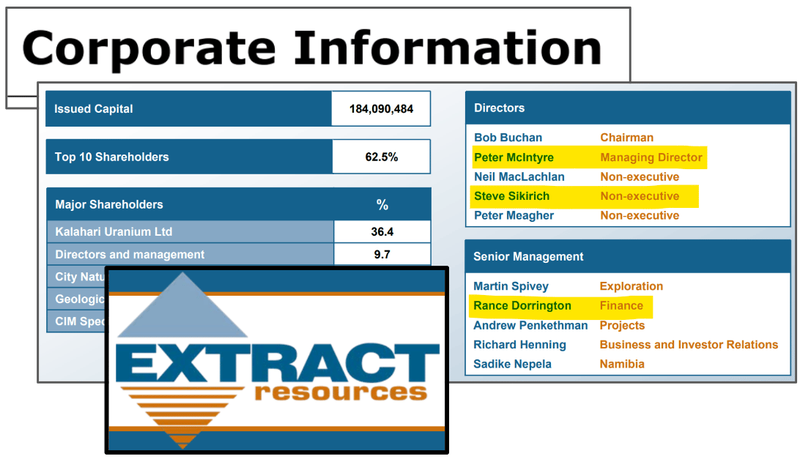
They are the same crew that built Extract Resources - the uranium explorer that discovered the third-largest primary uranium deposit in the world at the time.
AND got taken over for A$2.18BN in 2012.
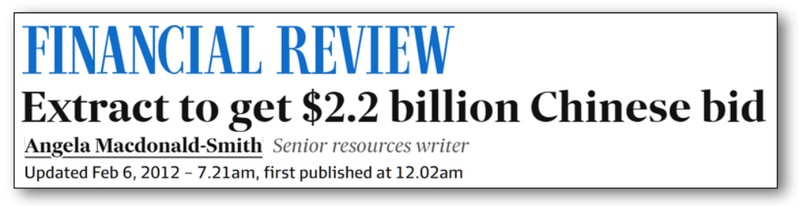
(source)
(The ex-Extract guys between them held ~29% of MNE pre raise) (source)
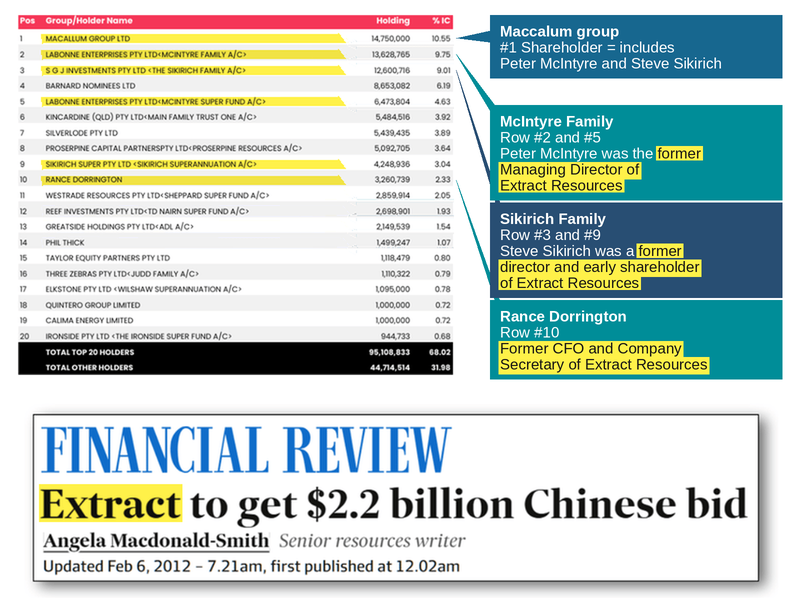
(source - thanks to the wayback machine for this)
We are backing them to (WE HOPE) re-run that Extract playbook again - but this time for gas in WA.
No guarantees of course - we will need some “drilling luck” here too - as we would with any explorer.
Why MNE now?
Below are some of the key gas discoveries, JVs, M&A and new production that happened in the Perth Basin since AWE made that gas discovery in ~2014:
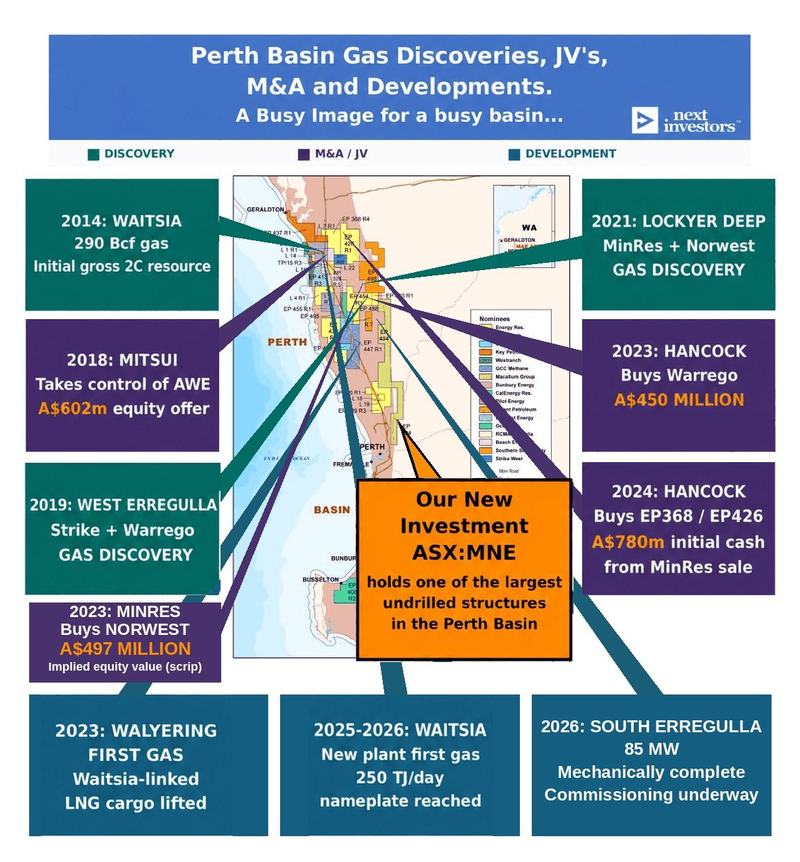
The exploration rush started in 2014 after the AWE Waitsia discovery.
Then between 2021 and today, we saw the Perth Basin go through a consolidation (M&A) and development phase.
The majors are now building those early discoveries - the 2014 AWE discovery is about to start producing from its stage 2 expansion...
All of that M&A meant there were very few ASX listed small caps exploring in the Perth Basin anymore.
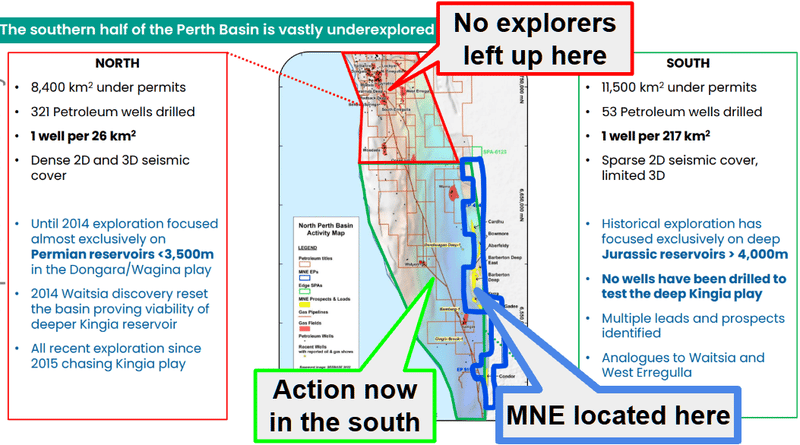
We think that the next wave of exploration will be in the south of the basin.
Which can be drilled with all of the lived experiences drilling out the northern part of the basin.
For example the deeper “Kingia Reservoir” which was responsible for the Perth Basin opening discovery by AWE.
(yes - AWE that MNE’s CEO was exploration manager at)
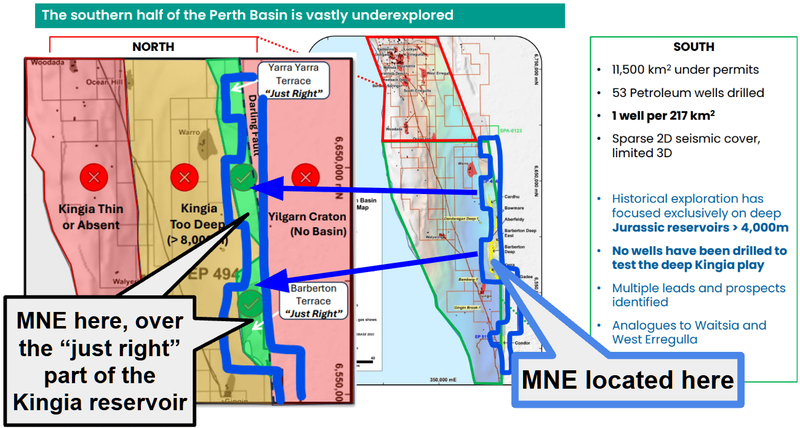
That Kingia reservoir has never been drilled in the southern part of the Perth Basin:
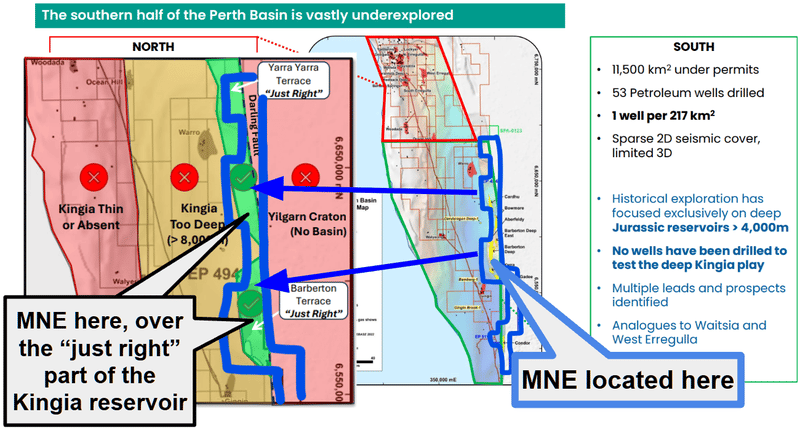
We also like that MNE’s targets all sit at similar depths to those discoveries in the north (at ~4,200-4,800m).
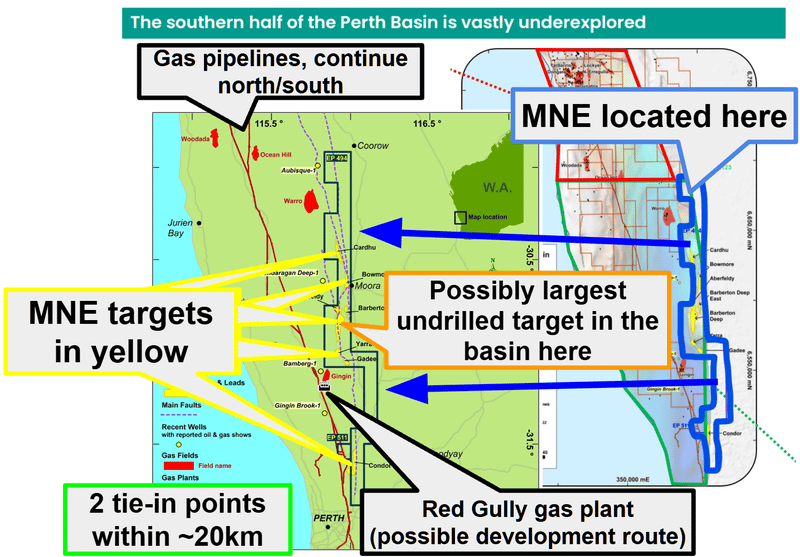
Another reason we like MNE's project is mostly because of where it sits relative to existing gas plants that are going to need gas to fill them in the 2030s...
AND IF a discovery is made - MNE has infrastructure ready to go ~20km away owned by $9.9BN Mineral Resources.
Which Mineral Resources say is “ready to be brought back into production in the near-term” - IF someone finds gas in the southern Perth Basin. (source)
10 reasons why we Invested in MNE:
These are all from our initiation note which we sent out on the 28th of October here: Our New Investment is Macallum New Energy (ASX: MNE)
Given that is a few weeks old now, we have included “updates” where necessary below:
1. ASX investors have made money in Perth Basin oil and gas
The ASX knows the Perth Basin really well AND has seen small caps have success with oil and gas there.
AWE whose discovery in 2014 opened up the Perth Basin was taken over for A$602M.
Warrego for A$440M, Norwest for ~A$497M, Talon for A$142M.
Then Hancock came in and paid Mineral Resources ~$780M cash for its projects.
That's over $2.4BN of takeovers and asset sales since 2018.
(source)
2. MNE is the only pure-play small cap Perth Basin explorer left on the ASX
There is almost no other way to get pre-discovery leverage to the Perth Basin, listed and currently trading on the ASX anymore.
The smallest company besides MNE is ~$357M Strike Energy.
The rest of the players are all multi-billion dollar companies - Beach, MinRes, Mitsui and Hancock.
MNE has a market cap of $22.6M at 14c following today’s raise.
🚨 UPDATE:
MNE is capped at $25.7M.
Beach is capped at $2.1BN.
MinRes is capped at $9.9BN.
Mitsui is capped at $131BN
Hancock is Australia’s biggest private company.
3. MNE has “possibly the largest undrilled structure” in the Perth Basin - based on 2D and 3D seismic data
MNE has a total of over ~2.3 Tcf of mean prospective gas and ~93 million barrels of oil - all 100% owned, across four prospects and two leads. (source)
(prospective resource = undrilled and unrisked based on 2D/3D seismic data)
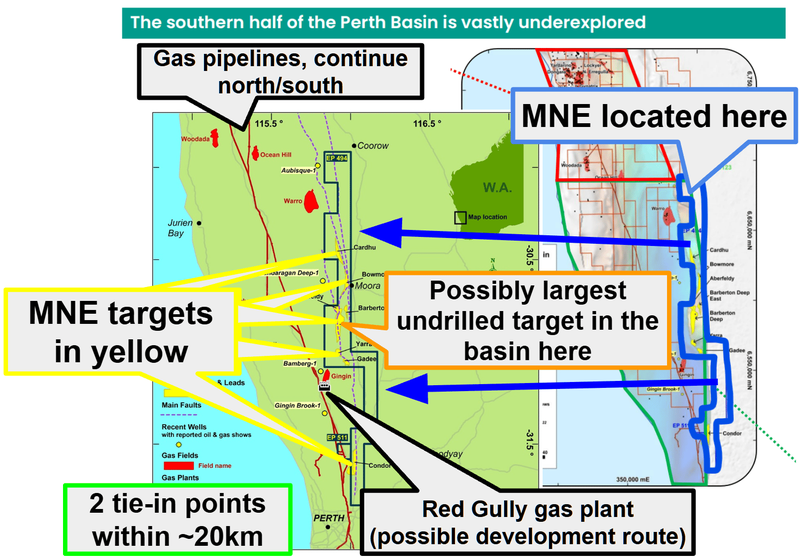
MNE also holds what it says is possibly the largest undrilled gas target in the Perth Basin - Barberton Terrace Deep.
That single target alone has a mean prospective resource of ~1.4Tcf of gas and a company-estimated 29% chance of success. (source)
(source)
4. MNE’s targets sit in the same “Kingia reservoir” that delivered the big discoveries in the northern part of the basin
The “Kingia sandstone” is the reservoir behind every big Perth Basin discovery since 2014.
(Waitsia - AWE which was taken over for $602M, West Erregulla - Warrego taken over for $440M and Lockyer Deep - Norwest Energy taken over for $497M.)
Nobody has ever drilled a well to test the Kingia in the southern half of the basin. (source)
MNE's giant 1.4Tcf Barberton Terrace Deep prospect is interpreted to sit inside the Kingia... (source)
5. MNE’s CEO led the team that made AWE’s discovery in 2014
MNE’s CEO Andy Furniss was AWE's General Manager of Exploration & Geoscience from 2009 to 2018.
His team discovered the Waitsia field in 2014 - which eventually led to AWE’s $602M takeover in 2018.
He was an advisor to the AWE board through the 2017/18 three-way takeover battle, then spent seven years as VP Exploration at Mitsui E&P - the company that won.
Now he is back in the Perth Basin running MNE...
(source - Andy’s LinkedIn profile)
6. MNE is backed by the guys who built up and sold $2.18BN Extract Resources
MNE's top three holders are “Macallum Group”, the McIntyre family and the Sikirich family. (who between them hold ~29% of the company) (source)
They are the same crew that built Extract Resources - the uranium explorer that discovered the third-largest primary uranium deposit in the world at the time.
AND got taken over for A$2.18BN in 2012.
Peter McIntyre (McIntyre family) was Extract’s Managing Director (source), Steve Sikirich (Sikirich family) was on the Extract board (source) And Rance Dorrington - now an MNE director - was Extract's CFO and Company Secretary. (source)
After Extract, McIntyre, Sikirich and Dorrington set up Macallum Group.
We are backing them to re-run that Extract playbook again - but this time for gas in WA.
(source - thanks to the wayback machine for this)
7. MNE’s project is close to existing gas plants and pipelines
MNE’s targets sit within ~20km of pipeline tie-in points, and underused gas plants such as Red Gully are nearby.
So a discovery could be brought to market quickly (and relatively cheaply).
8. WA needs new gas supply
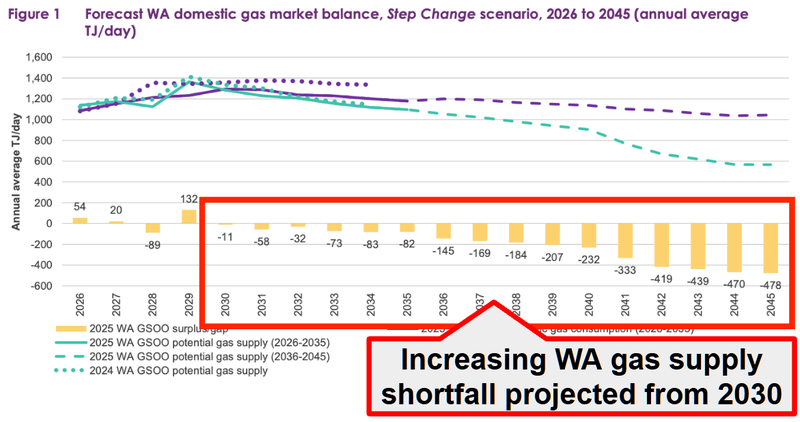
The Australian Energy Market Operator is forecasting WA gas shortfalls in 2028 and 2030.
Then projecting a shortfall of supply that gets worse every year through to 2045.
(That is before we even consider any data centre driven demand - if the stuff from this article comes to fruition: Mystery client drives plans for WA's biggest gas power - then the shortfall could be even worse).
IF MNE can execute its timelines and drill a well (and make a discovery) in 2027 as per its latest preso.
Then the discovery could be ready for development just as the market starts looking around for potential new supply options...
(source)
🚨 UPDATE:
WA's October spot gas prices are up ~18% on September. (source)
9. MNE has three deep-pocketed neighbours who are active in the basin
We think that IF MNE makes a discovery there are plenty of neighbours who may be interested in whatever is found.
$8.7BN MinRes holds 100% of every permit on MNE's western boundary, has a rig back in the basin, and owns the Red Gully plant (which is idle right now) 20km from MNE's targets. (source)
Hancock has paid ~$1.3BN cash for Perth Basin gas since 2023 and wants to build an $850M gas plant. (source)
Mitsui and $2.1BN Beach own the Waitsia plant - whose LNG export permit runs out at the end of 2028, after which it may look for domestic gas to backfill its plant. (source)
10. $22.6M market cap, a tight shareholder register with leverage to a re-rate
The top 20 shareholders of MNE hold ~71% of the stock (before today’s raise).
About ~34% (after today’s raise) of the shares are escrowed until February 2028 - past the planned drilling window. (source)
We also like that the big holders - Macallum Group’s 18.9 million performance rights only vest if MNE books a resource or drills a well AND the stock holds above 20c. (source)
MNE after today’s capital raise will only have ~161.6M shares on issue too so there aren’t that many shares on issue here.
Ultimately we are hoping a combination of the above reasons helps deliver our Big Bet, which is as follows:
Our MNE Big Bet:
"MNE makes a gas discovery, re-rates to a $250M+ market cap through a takeover, farm-in or development funding deal at multiples of our Initial Entry Price."
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including exploration risk, commodity price risk and market risk - just some of which we list in our MNE Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What we want to see MNE do next
🔄 Lock in funding for first well
We want to see MNE fund its first well by bringing in a farm-in partner to finance drilling on its project. Ideally MNE retains >50% of the project post-funding.
Here are the milestones we are tracking:
- ✅ Farm-out process begins (Data room opened - October 2026)
- 🔲 Offers received from interested parties
- 🔲 Farm-in partner secured, funding up to two wells
- 🔲 (bonus) Alternative funding deal
🔄 Well planning and approvals
We want to see MNE lock in its first drill target, receive approvals and start ordering long lead items for its first well in H2-2027.
Here are the milestones we are tracking:
- ✅ Land access signed for the first Barberton Terrace Deep well (~1.4 TCF target)
- 🔄 Well planning commenced - Aztech appointed, three wells being designed (new - today)
- 🔲 Final investment decision on the first well (targeted Q1 2027)
- 🔲 Regulatory approvals received for well locations
- 🔲 Long lead drilling items ordered and received (targeted Q2 2027)
What could go wrong?
The single biggest risk right now is without a doubt "farm-out risk".
MNE’s data room is open and the process runs to the end of the year, but there is no guarantee a deal gets done.
If the process drags into 2027 the H2 2027 drilling timeline can slip with it.
Farm-out risk
MNE is relying on a farm-out partner to fund most of the cost of drilling. There is no guarantee that MNE will be able to find a partner, or attract a farm-in partner on terms that are in line with MNE’s market valuation. Without a farm-in partner secured, the 2027 drilling timeline could also slip.
Source: “What could go wrong” - MNE Investment Memo 28 October 2026
Other risks
Like any junior oil and gas exploration company, MNE carries significant risk, here we aim to identify a few more risks.
While MNE has started well planning on three prospects, the final choice of well will only be made once a farm-in partner is signed.
The AWE, Norwest and Warrego takeovers we reference were for companies that had already drilled and flow tested their discoveries. MNE's targets are undrilled, so those deal values only become a relevant comparison if MNE makes and proves up a discovery.
MNE has started its Environmental Plan and other approvals for all three locations, and has signed land access for BTD-1. Any delay in approvals, or in land access for the Gadee East and Aberfeldy locations, could hold back drilling.
The data centre gas demand we reference, including the WA power station reported by WAtoday, is not linked to MNE. Those projects may not go ahead, or may source their gas from existing suppliers.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our MNE Investment Memo
In our MNE Investment Memo, you can find the following:
- What does MNE do?
- The macro theme for MNE
- Our MNE Big Bet
- What we want to see MNE achieve
- Why we are Invested in MNE
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.