Western Australia gas explorers win with Federal gas scheme carve out announced.
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 4,103,571 MNE Shares at the time of publishing this article. Some shares disclosed are subject to shareholder approval. The Company has agreed to be engaged by MNE to share our commentary on the progress of our Investment in MNE over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
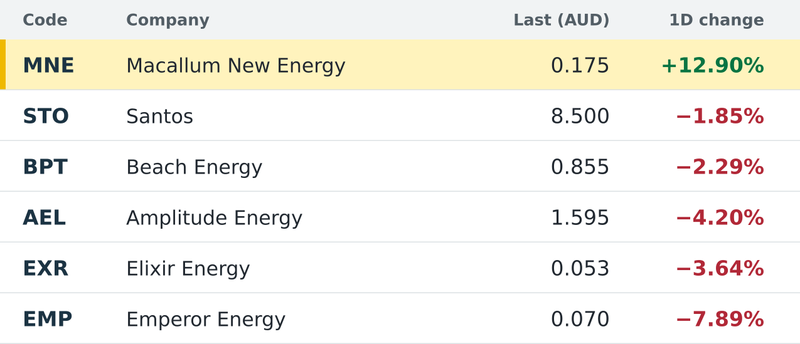
Why was our Investment Macallum New Energy (ASX:MNE) up 12.9% yesterday?
(on one of the worst ASX trading sessions we have seen this year)
We think it is because of this:
The Australian federal government just proposed a “carve out” for WA from the “gas reservation scheme” being proposed for the national gas market:
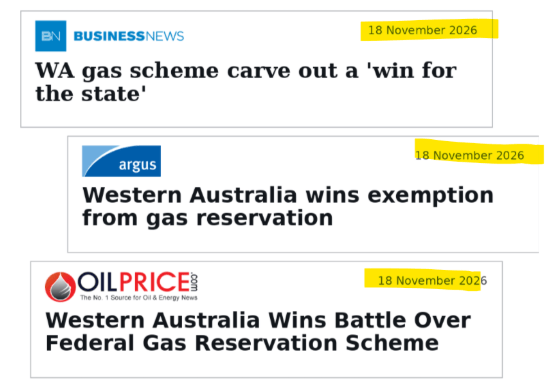
Avoiding inclusion in this scheme is great for WA gas explorers like MNE.
Still included in the scheme are the eastern states gas explorers... who don’t get the carve out.
After that news came out, we saw anything with east coast gas exposure get whacked - and our Investment, MNE, traded up:
(As always, the past performance is not an indicator of future performance)
Here’s what the CEO of another WA gas company said about the news:
Shelley Robertson, chief executive at Strike Energy said: “fantastic.”
“It’s such a significant win for Western Australia and for the future of WA gas,” she said. “What it means for us as a small growing company like Strike Energy [is] that we can see the way forward in how we develop our future gas projects.”
Great news for MNE too.
(this is one bit of macro news we couldn’t predict or rely on, and was totally out of the company’s control - just got lucky here, rare bit of luck these days - we’ll take it)
Why is being excluded from the gas reservation scheme good for WA gas explorers?
Because the gas reservation scheme has been a sort of dark cloud above the Australian domestic gas industry for almost a year now.
What exactly is the ‘gas reservation scheme’?
- The Federal government is considering a law that FORCES LNG exporters to supply 20% of their gas production into the domestic market.
- Regardless of whether or not there is demand for that gas.
This was supposed to be the federal government's way of avoiding a gas supply shortage on the east coast in future years - by FORCING the LNG exporters to sell to the domestic market.
The implications of that scheme would have been gas being dumped into the domestic market at any cost - SO as not to risk LNG export quotas (where they are able to fetch higher prices).
So yes, gas prices would crater BUT potentially at the cost of an investment freeze into new domestic supply (because prices would be so low from the LNG dumping).
Unless you are able to sell into international markets (LNG) - it would make little sense to invest in bringing new supply online.
WA getting a carve out means MNE is de-risked for us from a regulatory perspective.
This was one of the major risks we flagged in our MNE Investment Memo:
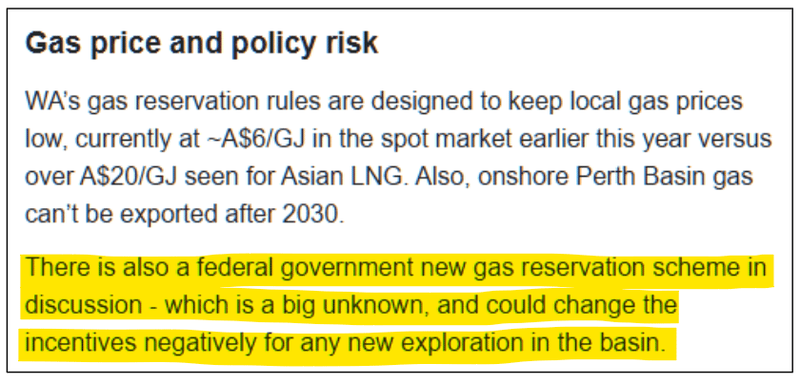
(source - Our MNE Investment Memo)
Assuming the federal government's proposal goes ahead - risk avoided = great.
(especially in this market - the last thing small caps need right now is added regulatory risk)
The big positive is that now MNE can market its project to potential farm-out partners with a lot less uncertainty around the regulatory environment in WA.
MNE’s project just became more attractive to potential partners for four reasons:
- WA domestic gas prices won't get smashed as a consequence of the reservation scheme on the east coast. (risk avoided - capital hates risk and uncertainty)
- Institutional investors that may have been waiting for clarity on how the reservation scheme will be applied to WA - now they can mentally de-risk this.
- Any major gas company with exposure to the domestic east coast gas market will now be rethinking their asset portfolio compositions.
- And whatever capital was reserved for investment into east coast supply... COULD start looking at opportunities in other gas projects inside Australia...
Maybe someone like ~$2BN Beach Energy who has been relatively trigger happy doing deals with juniors.
Beach recently agreed to a farm-in on Elixir Energy’s project in Queensland in a deal worth up to $205M ($25M cash plus a $180M carry). (source)
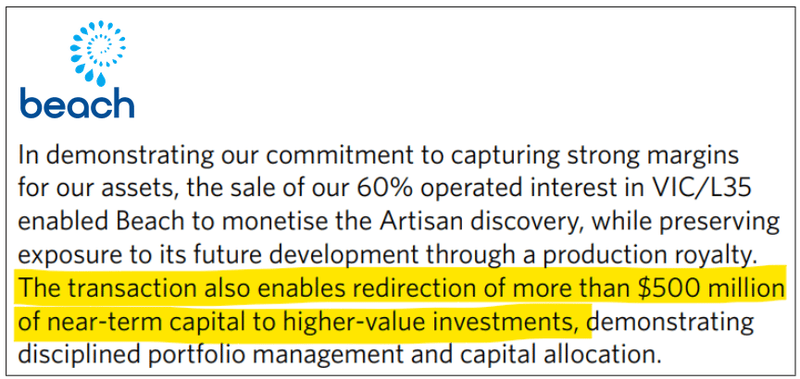
AND it divested east coast gas assets in the Otway Basin saying:
“The transaction also enables redirection of more than $500 million of near-term capital to higher-value investments”
($500M buys you a lot of onshore wells...)
(source)
FUN FACT:
Beach owns 50% of the project (Waitsia) that MNE’s current CEO Andy Furniss discovered when he was exploration manager at AWE over 10 years ago... (more on that story in a second)
Or someone like Hancock Energy (Gina Rinehart's energy company), which has poured ~$1.3BN into the Perth Basin for gas since 2023 and wants to build an $850M gas plant. (source)
Lucky for them...
MNE has a data-room open and is looking for a farm-in partner right now...
Why we think the bigger players will like MNE’s prospects
MNE holds 100% of what it calls "possibly the largest undrilled Permian gas prospect in the Perth Basin".
All up, MNE currently has ~2.3 Tcf of gas and ~93 million barrels of oil, undrilled targets, across four prospects. (source)
The single biggest is ~1.4 Tcf - Barberton Terrace Deep target.
MNE’s plan is to drill one (or two) of those targets next year - JUST ahead of that 2028 projected shortage.
MNE currently has a “data-room open” looking for a farm-in partner for the project.
(A farm-in partner is when a bigger oil & gas company pays for all or part of the drilling in return for a share in the project)
Guidance is for a deal to be done next quarter with the farm-out process to run through to the end of this year.
MNE’s goal is to then drill up to two wells in H2 of 2027. (source)
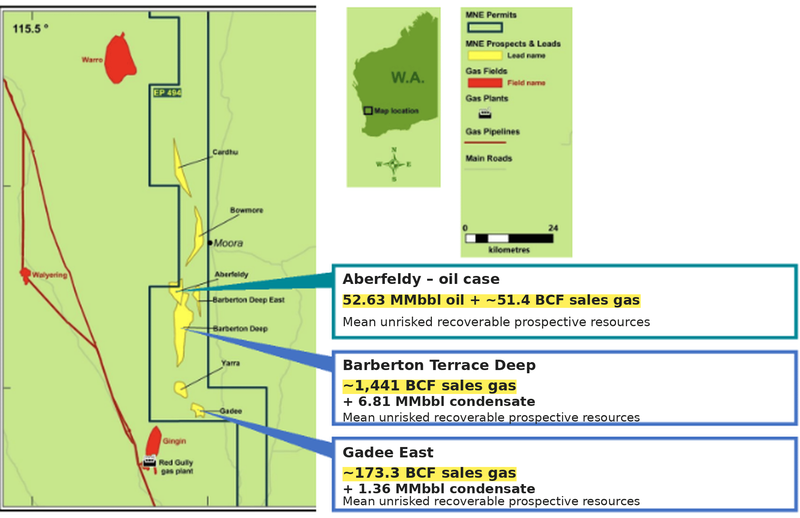
MNE confirmed that well planning had started for THREE possible exploration wells (previously we understood it to be one, possibly two):
- Barberton Terrace Deep (~1.4 Tcf target),
- Gadee East (~170 Bcf target), and
- Aberfeldy (~52.6 million barrels oil + ~50bcf gas)
(source)
A discovery across any of those could be company making for the $28M capped MNE.
Rule of thumb, any discovery made during the last exploration rush in the Perth Basin was taken over for an average of ~A$2.74M per bcf.
Even on the smallest named Gadee target, IF (and that’s a big IF) discovered, that would be ~$460M+...
That’s just an idea of the size of the potential prize - there’s no guarantee that MNE can make a discovery and commercialise it - gas exploration is risky.
(watch it in full here: MNE investor presentation from September)
We are Invested in MNE to hopefully see it repeat previous Perth Basin successes - like Norwest Energy which ran from 0.3c to ~7c on its discovery - a gain of over ~2,200% - and was taken out by MinRes for ~$497M. (source)
Or like AWE’s Waitsia discovery in 2014 which started the rush into the Perth Basin (that was taken over for ~$602M). (source)
(the past performance of AWE and Norwest is not an indicator of the future performance of MNE)
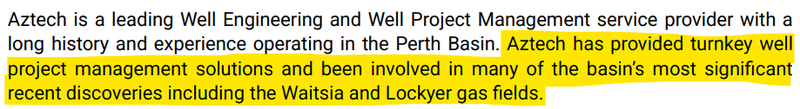
The group MNE has engaged to deliver its well design and planning was the same group who was involved in both the discoveries mentioned above.
(source)
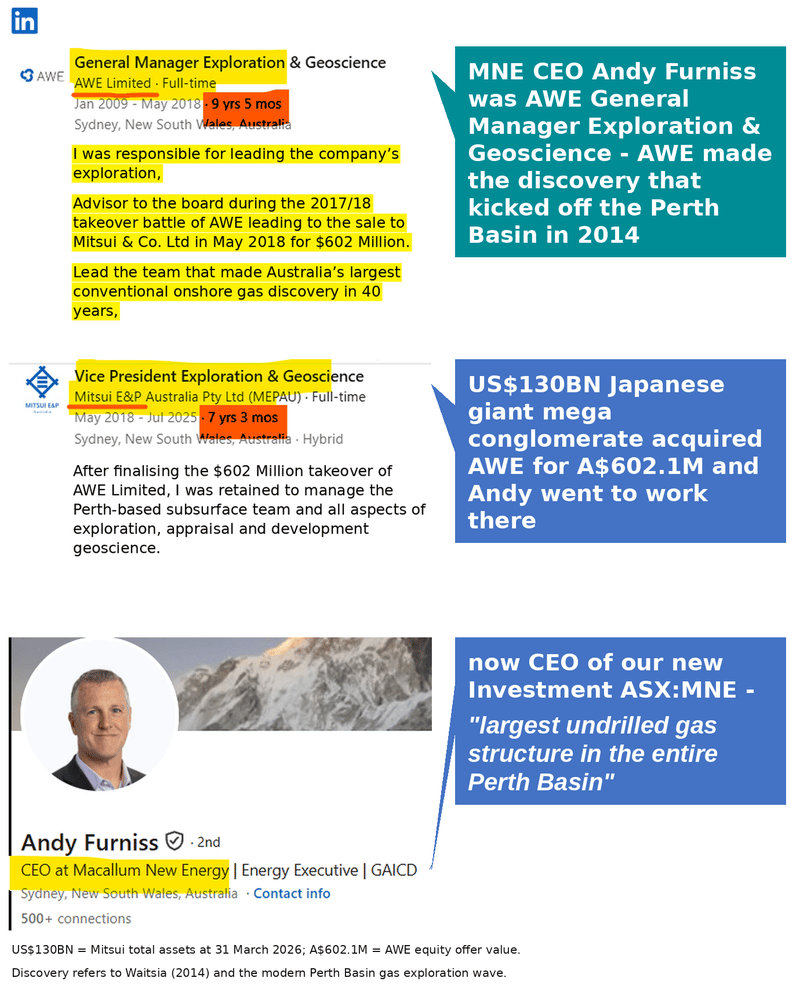
And as mentioned earlier, MNE’s CEO Andy Furniss was the General Manager of Exploration at AWE from 2009 to 2018.
Andy was with AWE all the way through to the eventual $602M takeover.
And then he spent ~7 years as Vice President of Exploration at the company that bought AWE - the Japanese giant Mitsui.
(source - Andy’s LinkedIn profile)
So with MNE, we are Invested in a company with:
- ~2.3 Tcf of gas and ~93 million barrels of oil (independently assessed, mean unrisked prospective) in undrilled targets - all 100% owned, all in the Perth Basin. (source)
- The exploration manager behind the discovery that opened up the basin - now running MNE, and backed by the same crew that sold Extract for ~A$2.2BN.
We also like MNE’s capital structure - one of the most important elements of a small cap investment
We mentioned in our initiation note that we’d been following MNE for a couple of years, watching it move from being a private company to an ASX listing in February this year.
What’s surprised us the most is how well MNE’s valuation has held up in an otherwise terrible market.
MNE’s share price is slightly below its 20c IPO - which in today’s market is a solid position to be in.
The thing we liked the most was how well MNE’s share price has held up from the recent 14c capital raise.
All of that stock (excluding the stock being allocated to directors) was issued on the 3rd of November, YET it looks like those new guys and existing holders are happy to hold onto their stock.
A refreshing sight... and yet another sign, MNE has managed to build a register of longer term holders who are here for the drilling event next year.
(as opposed to people wanting a 5-10% quick win)
MNE’s top 20 held ~71% of the company’s stock (pre raise) and ~34% of the register (after the last raise) is escrowed until February 2028.
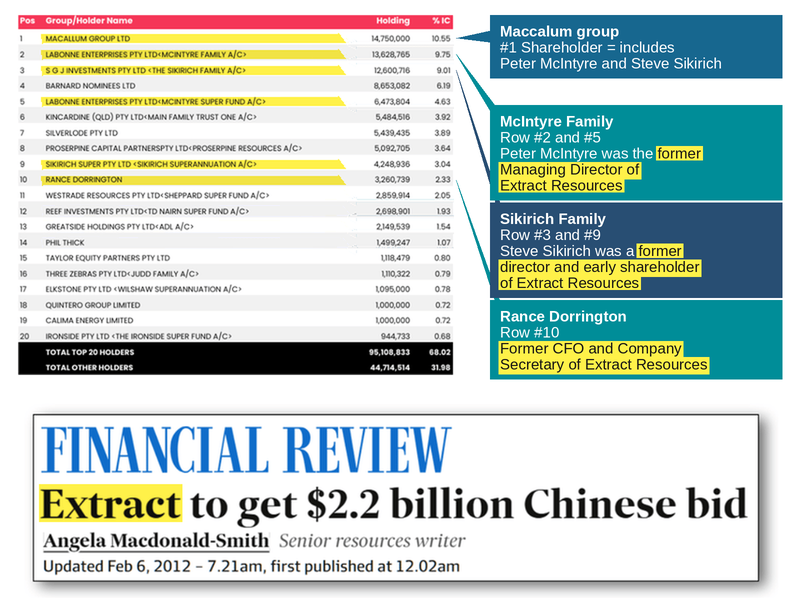
But the main reason we like MNE’s register is MNE's top three holders - Macallum Group, the McIntyre family and the Sikirich family.
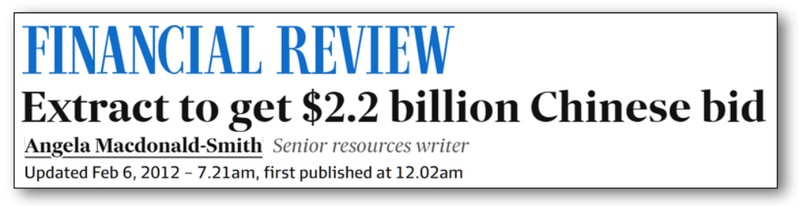
They are the same crew that built Extract Resources - the uranium explorer that discovered the third-largest primary uranium deposit in the world at the time.
AND got taken over for A$2.18BN in 2012.
(source)
(The ex-Extract guys between them held ~29% of MNE pre raise) (source)
(source - thanks to the wayback machine for this)
We are backing them to (WE HOPE) re-run that Extract playbook again - but this time for gas in WA.
No guarantees of course - we will need some “drilling luck” here too - as we would with any explorer.
Why MNE now?
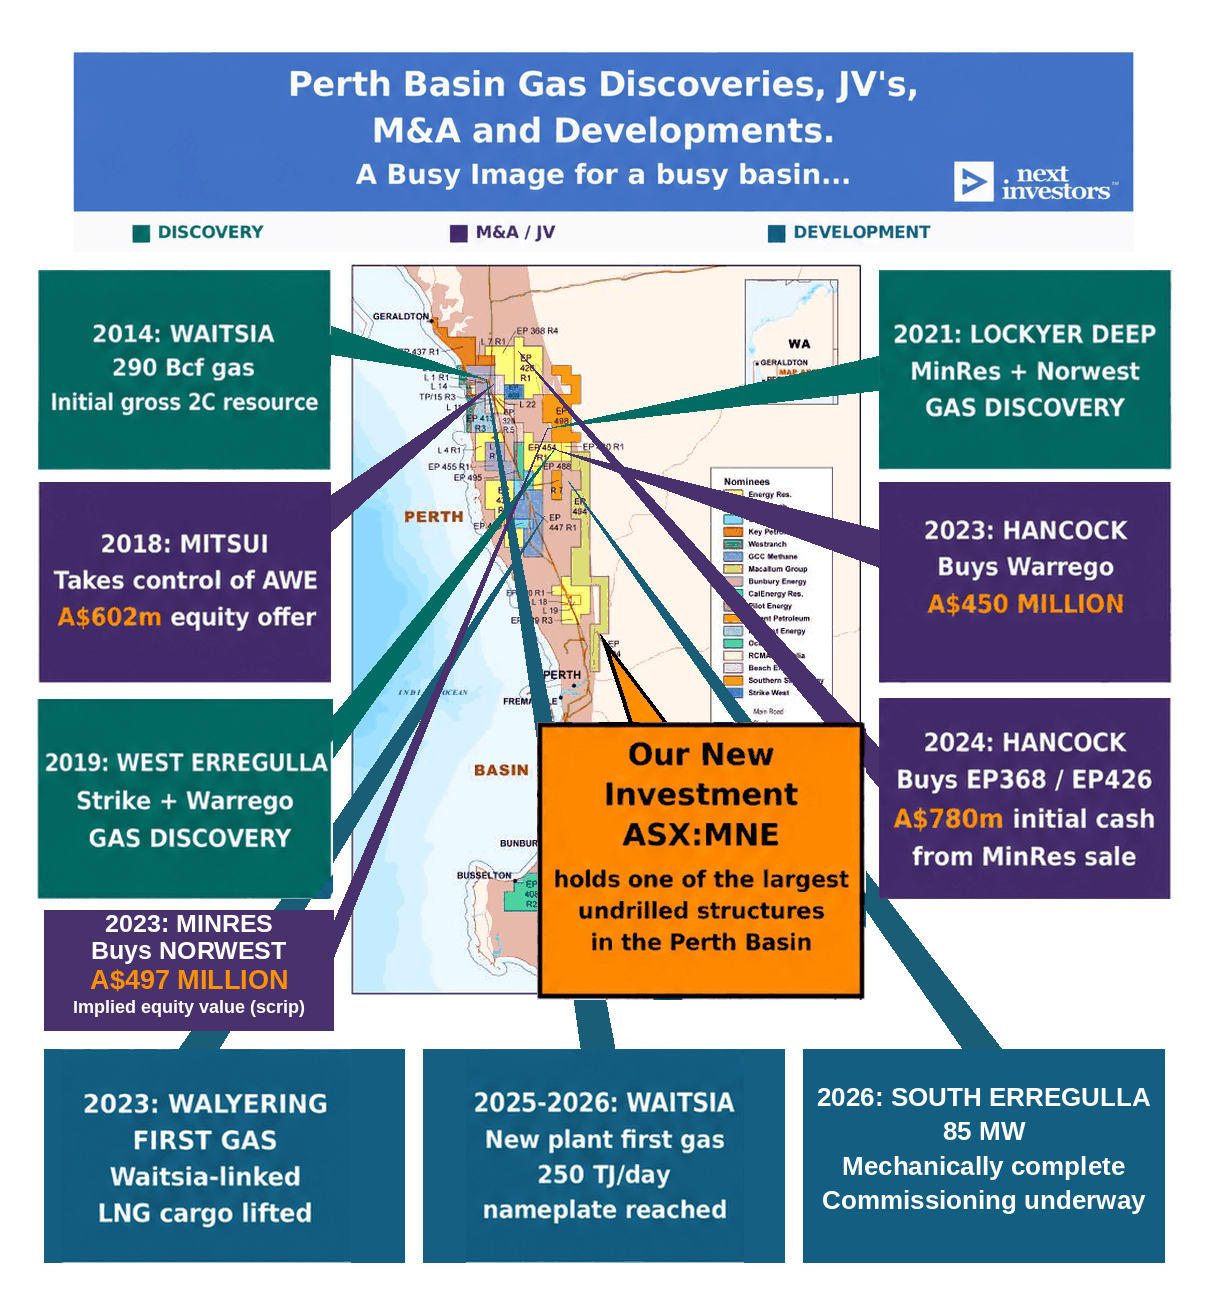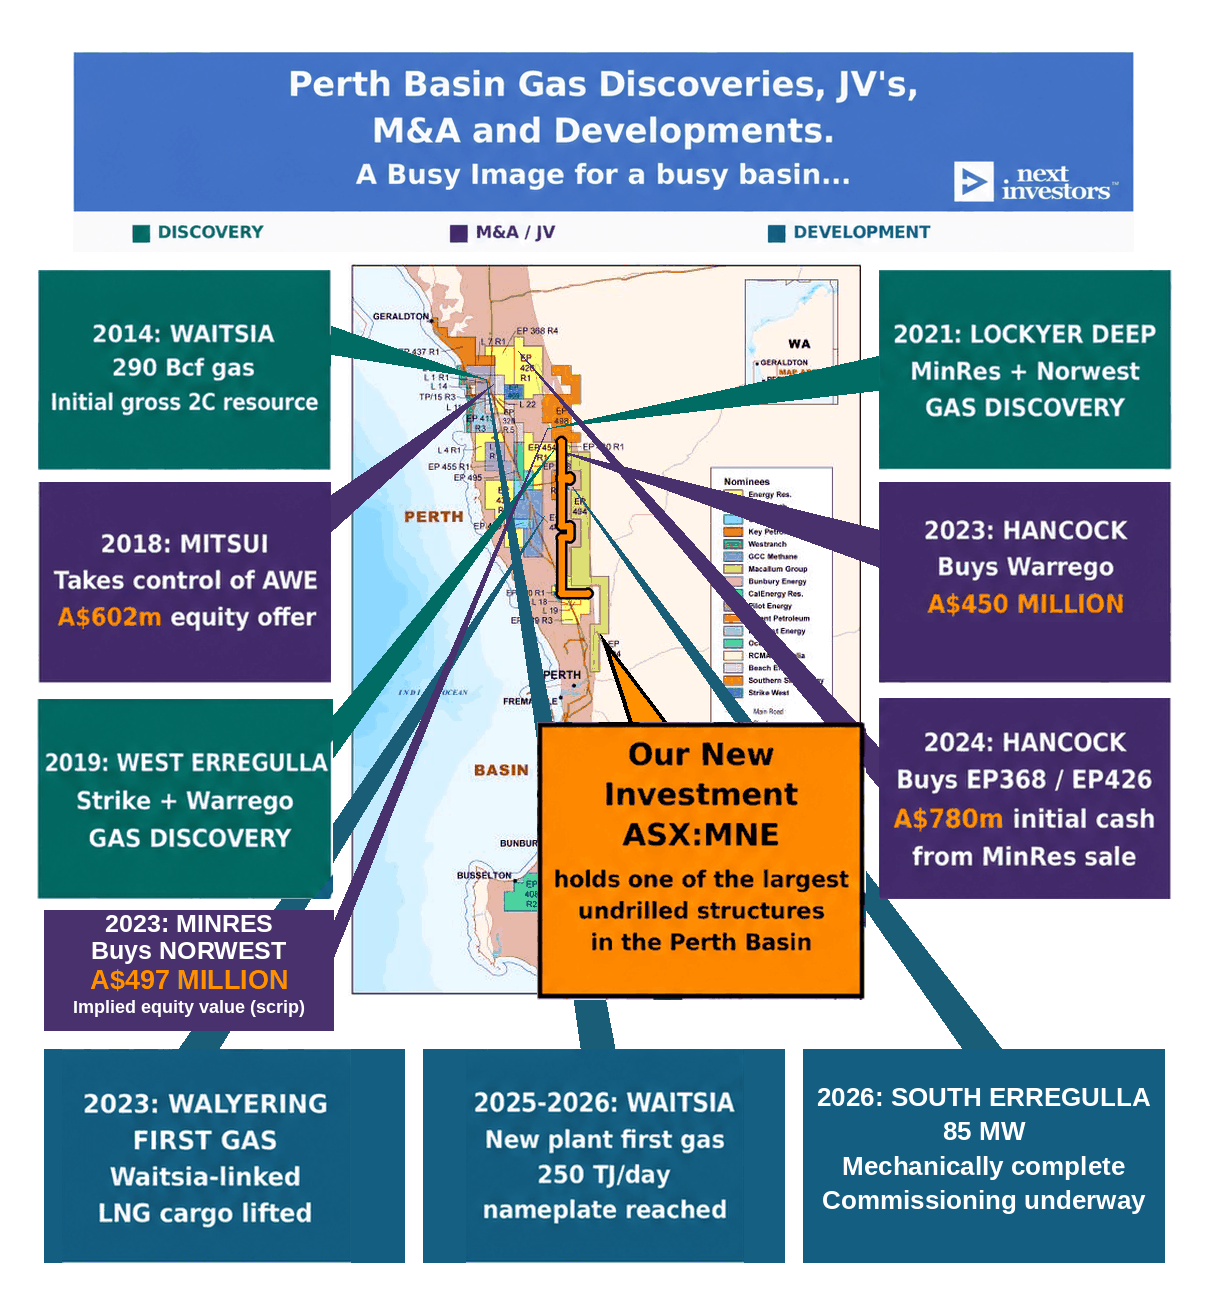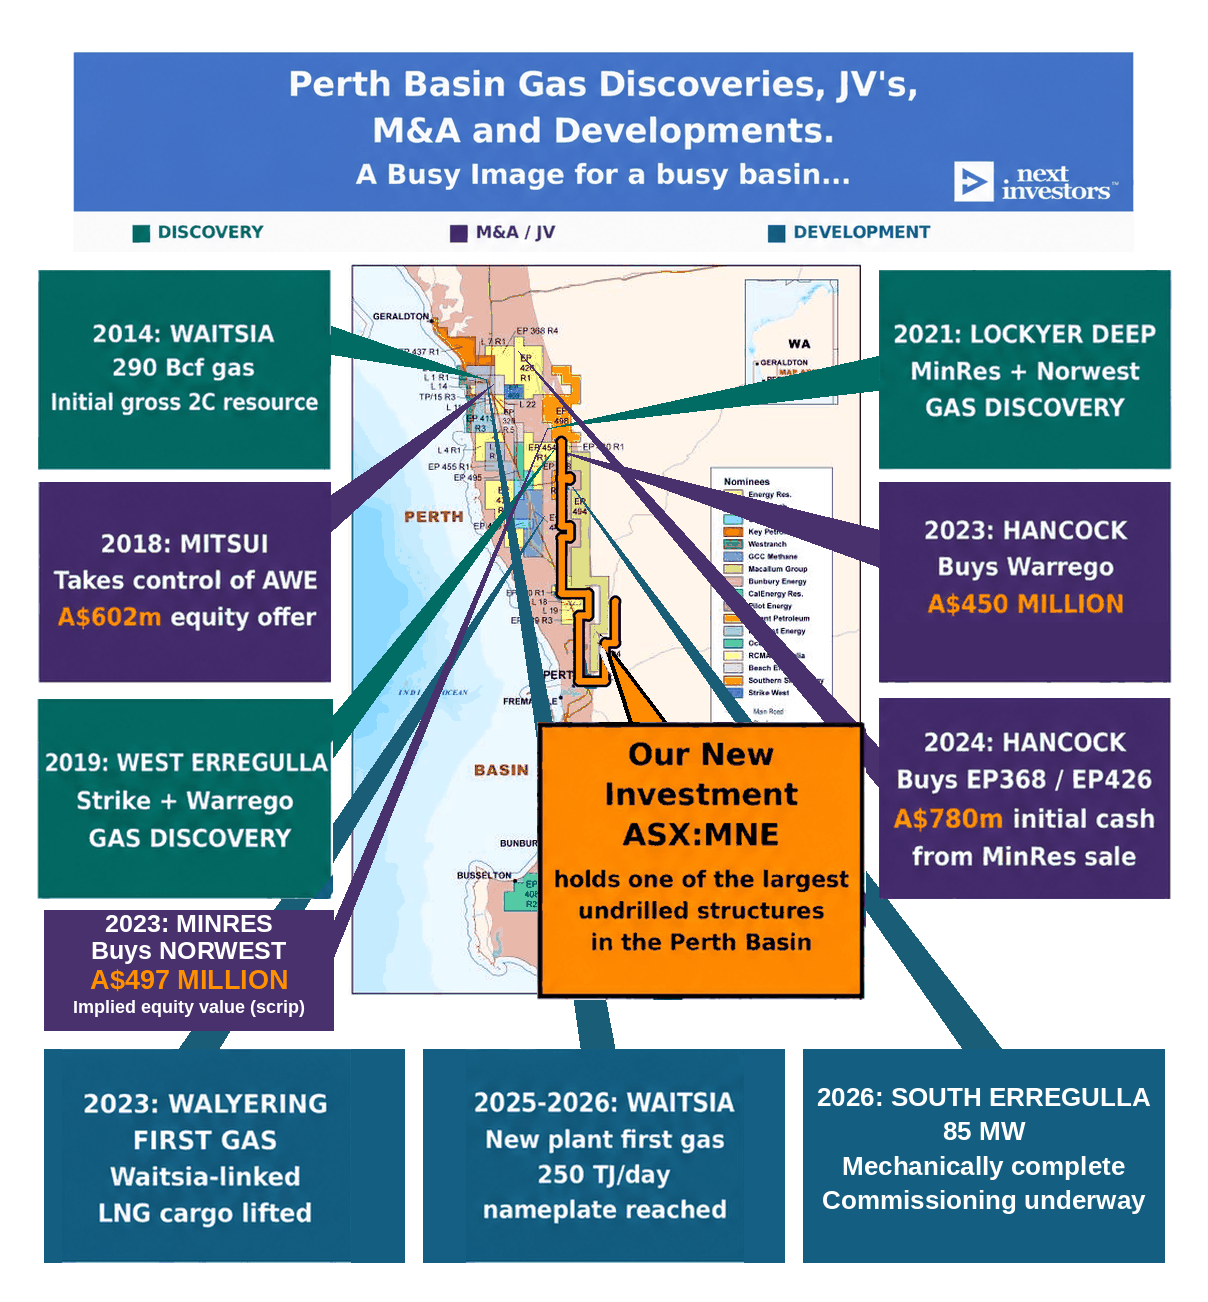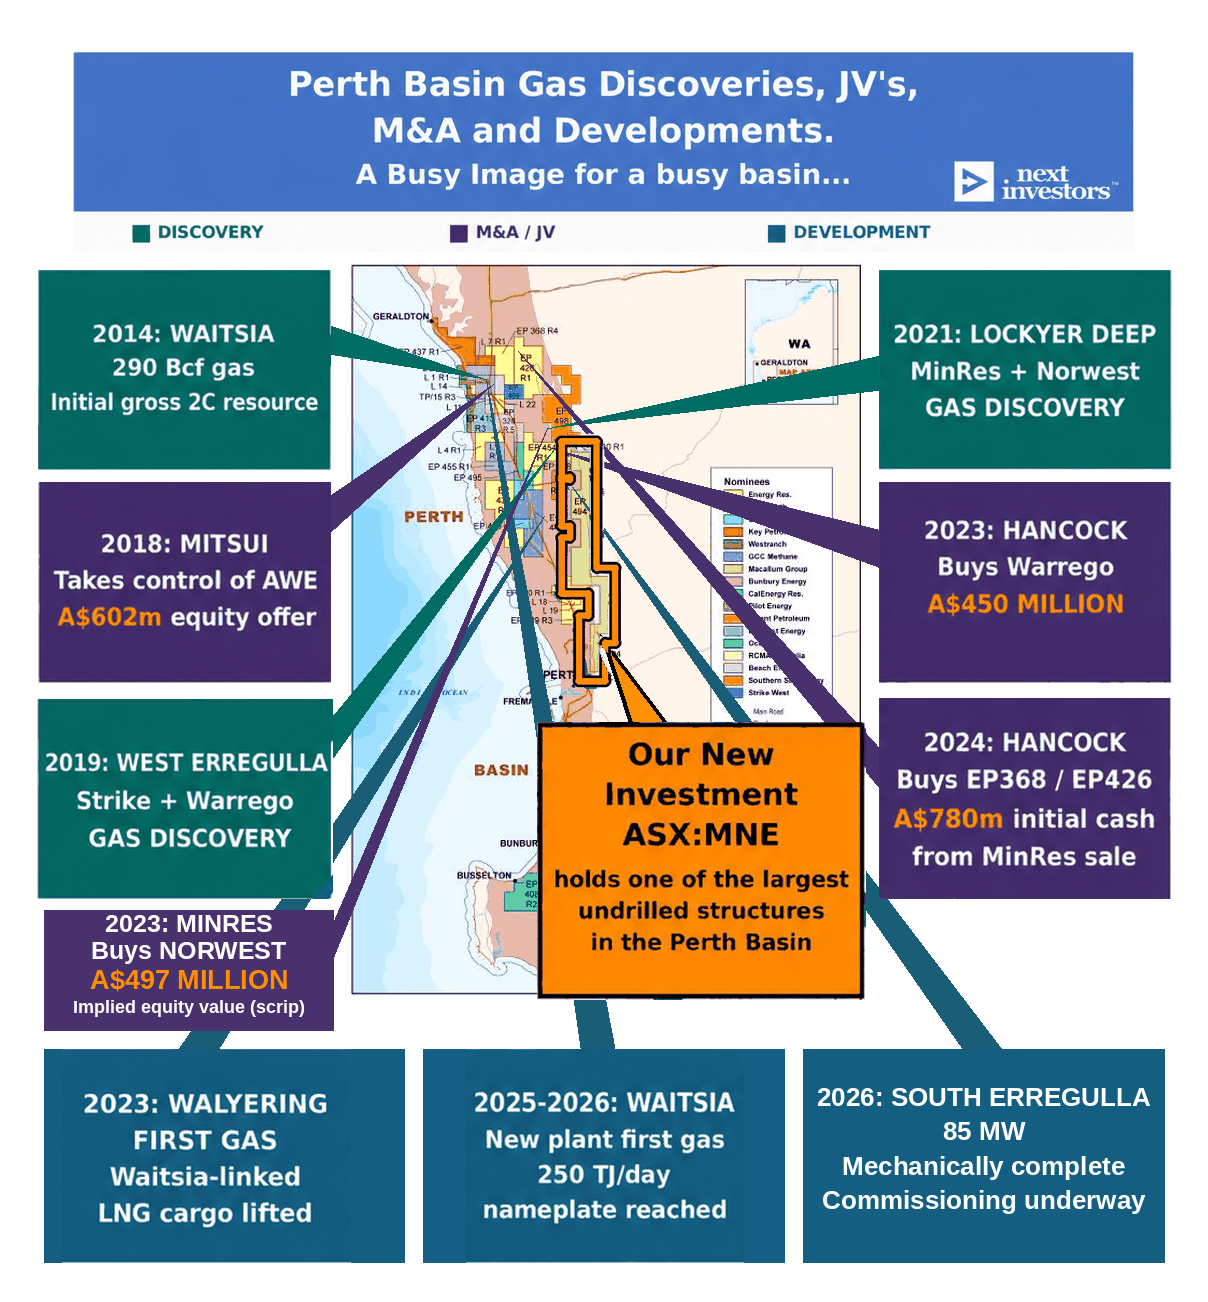
Below are some of the key gas discoveries, JVs, M&A and new production that happened in the Perth Basin since AWE made that gas discovery in ~2014:
(Perth Basin in Western Australia... this week news came out of WA avoiding the Australian gas reservation scheme and the negative impacts that come with it for gas projects)
The exploration rush started in 2014 after the AWE Waitsia discovery.
Then between 2021 and today, we saw the Perth Basin go through a consolidation (M&A) and development phase.
The majors are now building those early discoveries - the 2014 AWE discovery is about to start producing from its stage 2 expansion.
All of that M&A meant there were very few ASX listed small caps exploring in the Perth Basin anymore.
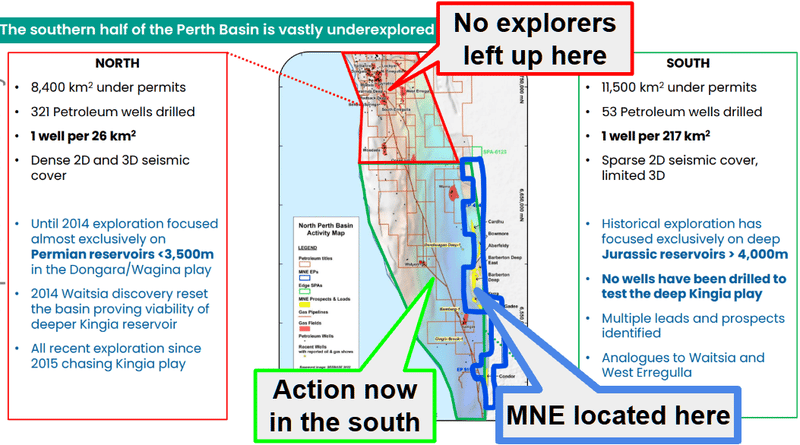
We think that the next wave of exploration will be in the south of the basin - which is where MNE’s assets happen to sit.
And which can be drilled with all of the lived experiences drilling out the northern part of the basin.
For example the deeper “Kingia Reservoir” which was responsible for the Perth Basin opening discovery by AWE.
(yes - AWE that MNE’s CEO was exploration manager at)
The Kingia Reservoir has never been drill tested in the southern part of the Perth Basin:
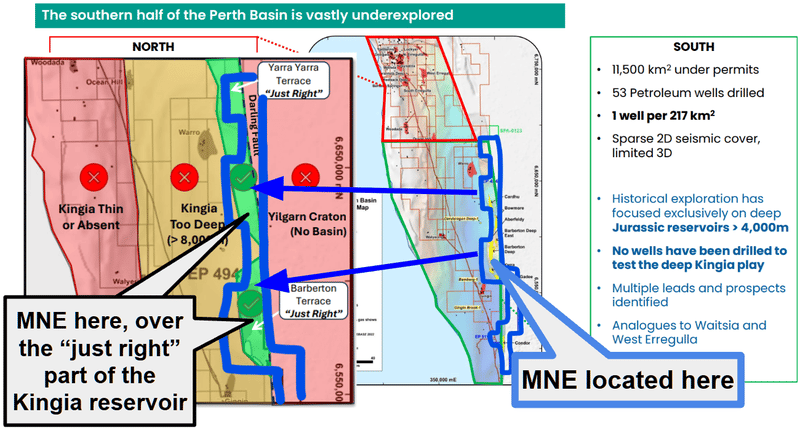
We also like that MNE’s targets all sit at similar depths to those discoveries in the north (at ~4,200-4,800m).
Another reason we like MNE's project is mostly because of where it sits relative to existing gas plants that are going to need gas to fill them in the 2030s...
AND IF a discovery is made - MNE has infrastructure ready to go ~20km away owned by $9.9BN Mineral Resources.
Which Mineral Resources say is “ready to be brought back into production in the near-term” - IF someone finds gas in the southern Perth Basin. (source)
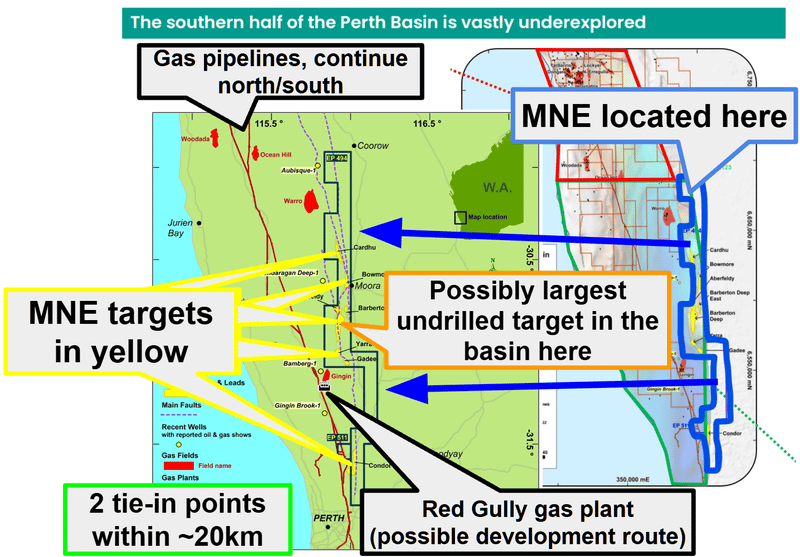
Ultimately we are hoping a combination of the above reasons helps deliver our Big Bet, which is as follows:
Our MNE Big Bet:
"MNE makes a gas discovery, re-rates to a $250M+ market cap through a takeover, farm-in or development funding deal at multiples of our Initial Entry Price."
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including exploration risk, commodity price risk and market risk - just some of which we list in our MNE Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
Macallum New Energy
What we want to see MNE do next
🔄 Lock in funding for first well
We want to see MNE fund its first well by bringing in a farm-in partner to finance drilling on its project. Ideally MNE retains >50% of the project post-funding.
Here are the milestones we are tracking:
- ✅ Farm-out process begins (Data room opened - October 2026)
- 🔲 Offers received from interested parties
- 🔲 Farm-in partner secured, funding up to two wells
- 🔲 (bonus) Alternative funding deal
🔄 Well planning and approvals
We want to see MNE lock in its first drill target, receive approvals and start ordering long lead items for its first well in H2-2027.
Here are the milestones we are tracking:
- ✅ Land access signed for the first Barberton Terrace Deep well (~1.4 TCF target)
- 🔄 Well planning commenced - Aztech appointed, three wells being designed (from last week)
- 🔲 Final investment decision on the first well (targeted Q1 2027)
- 🔲 Regulatory approvals received for well locations
- 🔲 Long lead drilling items ordered and received (targeted Q2 2027)
What could go wrong?
The single biggest risk right now is without a doubt "farm-out risk".
MNE’s data room is open and the process runs to the end of the year, but there is no guarantee a deal gets done.
If the process drags into 2027 the H2 2027 drilling timeline can slip with it.
Farm-out risk
MNE is relying on a farm-out partner to fund most of the cost of drilling. There is no guarantee that MNE will be able to find a partner, or attract a farm-in partner on terms that are in line with MNE’s market valuation. Without a farm-in partner secured, the 2027 drilling timeline could also slip.
Source: “What could go wrong” - MNE Investment Memo 28 October 2026
Other risks
Like any junior oil and gas exploration company, MNE carries significant risk, here we aim to identify a few more risks.
While the federal government and WA have agreed to an amendment that would permanently set WA's obligation under the national gas reservation scheme to zero, the bill is still before the Senate and the carve-out is not yet law. If the amendment is changed or the bill stalls, the policy uncertainty we flagged in our Investment Memo could return.
Even with WA outside the national scheme, WA's own reservation policy still applies, and onshore Perth Basin gas cannot be exported after 2030. Local prices could stay well below export prices, which may limit the value a farm-in partner places on any discovery.
Although MNE's data room is open, a farm-in partner may value EP 494 below what the market currently implies. A deal on weaker terms could leave MNE with a smaller share of any discovery than shareholders expect.
While MNE has committed to drilling in H2 2027, its EP 494 permit is up for renewal in November 2027 and the well commitment runs to November 2028. Any slip in funding or approvals could put pressure on those permit conditions.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our MNE Investment Memo
In our MNE Investment Memo, you can find the following:
- What does MNE do?
- The macro theme for MNE
- Our MNE Big Bet
- What we want to see MNE achieve
- Why we are Invested in MNE
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.