HAR: Gold up 2%, nice day for a high grade hit
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 6,852,143 HAR Shares at the time of publishing this article. The Company has been engaged by HAR to share our commentary on the progress of our Investment in HAR over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
OK, time for some relief?
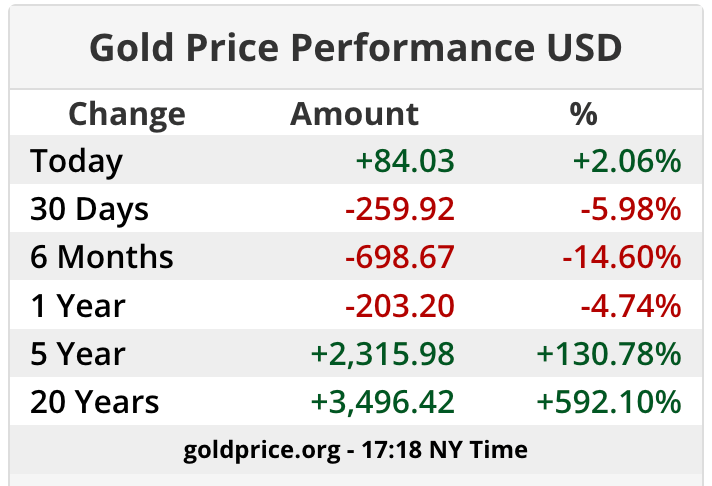
Gold is up 2% overnight...
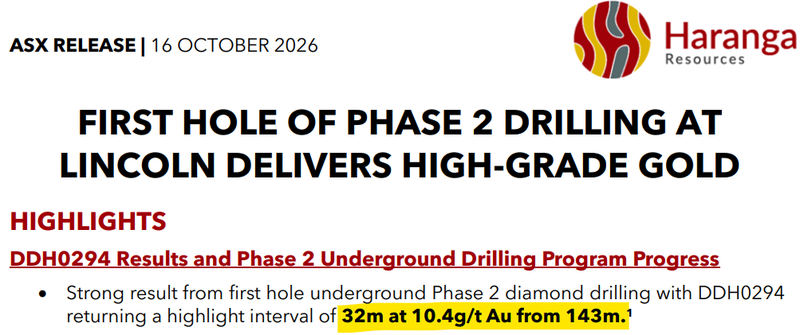
So this morning when our Investment Haranga Resources (ASX:HAR) puts out a high grade drill result like this:
32m at 10.4 g/tonne from 143m...
(source)
Our expectation is that it should trade fairly strongly off the back of the news.
In a bull market, that sort of high grade drill result would be an excellent result for any gold small cap with a market cap of $24M like HAR.
But it's been a fairly horrible few weeks for gold stocks... so let’s see how the market reacts this morning.
If we take a step back and look at the bigger picture:
Gold is up ~131% from where it was 5 years ago.
At the current gold prices, big producers are all putting out record cashflow numbers.
But for various reasons, sentiment isn’t great amongst the ASX small cap investors.
And so it’s brought down gold small cap share prices - we think unfairly.
The past performance of the gold price is not an indicator of the future performance of the gold price.
We think gold stocks with a pathway to production AND a big defined resource that have been sold down over the last few months COULD end up doing the best IF gold prices rip from here.
Which is pretty much what HAR is, and why we like it right now.
No guarantees of course, the ASX small cap gods can be cruel and unforgiving - as we have seen in recent weeks.
HAR owns 100% of a 402k ounce at 5.1g/t JORC resource estimate gold project in California’s Mother Lode region.
This is where the original Californian gold rush of the 1840s happened.
HAR’s project also comes with a relatively modern processing plant - built by the previous owners of the project back in 2013.
HAR says the project and its associated infrastructure cost ~$90M to build over the years.
Who knows what that is worth in today’s money.
HAR is currently capped at $24M, had $6.3M cash at 30 June 2026 meaning it trades with an Enterprise Value of roughly $18M.
(The September quarterly report will land in the next 2 weeks, so we will see an updated cash balance then.)
We think the market is missing two things with HAR:
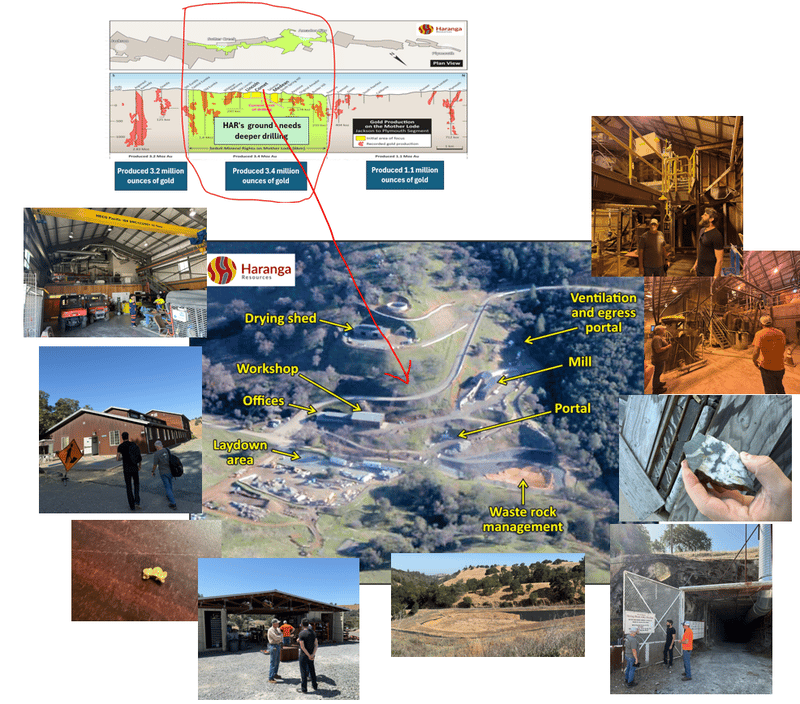
- Its infrastructure is in relatively good shape (only built in 2013 - check out the photos below) and puts HAR ahead of any other mid caps trying to develop a JORC resource... HAR just needs to put together a resource it's confident in, refurb/update the plant and start producing gold.
- HAR’s resource can get a lot bigger than the 402k ounces it sits at today.
The first point is fairly obvious to see, HAR currently has:
- A fully built and operational site office
- A fully built, stocked and staffed workshop
- A built and permitted 315,000 tpa gold processing plant
- A 880m decline (the tunnel to the gold)
- A laydown yard
(source - our site visit)
But the second point - how big the resource could get - can be easy to overlook.
As mentioned earlier, HAR’s current JORC resource estimate is for 402k ounces at an average gold grade of 5.1g/t.
So it's of decent size - and it's high grade.
BUT we think HAR can realistically push that resource estimate to over 1M ounces over the coming months - the psychological size where ASX investors really start re-rating small cap goldies.
As it stands, HAR has:
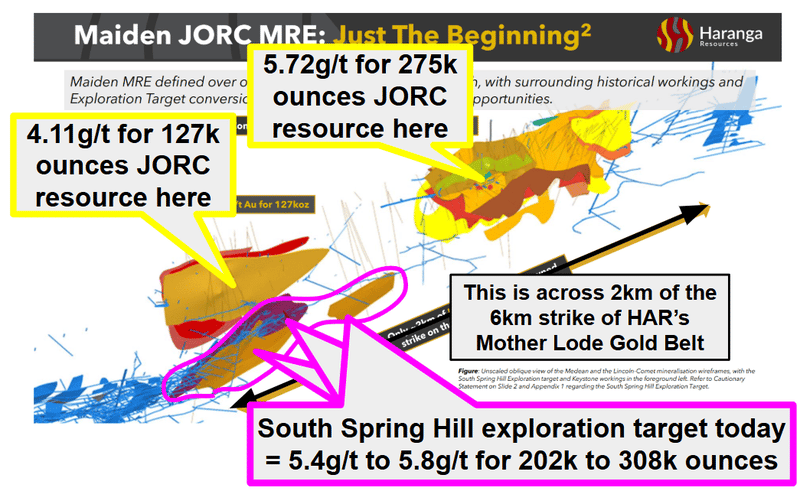
- 402k ounce gold JORC resource estimate at Lincoln/Comet and Medean.
- A ~308k ounce exploration target at the "South Spring Hill" target, and,
- Multiple exploration targets expected between now and the end of the year (more on those in a second)
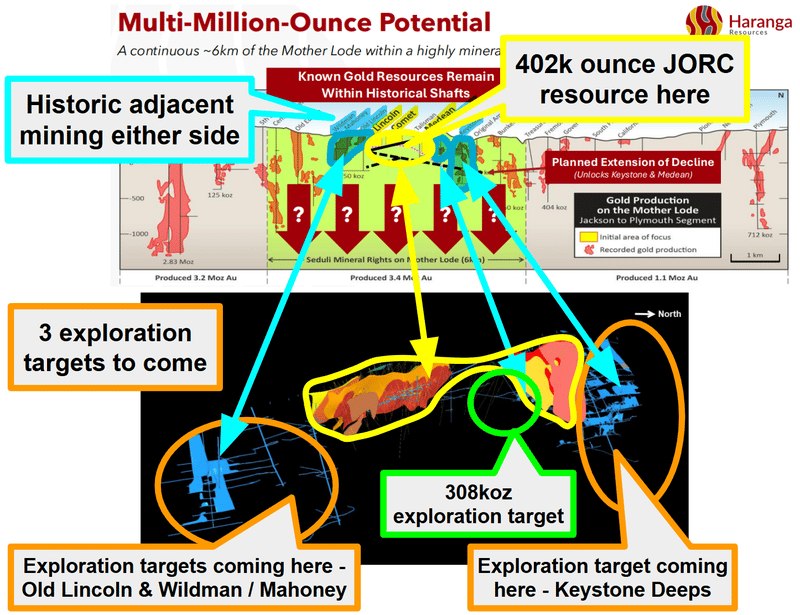
We think a quick easy win for HAR could be converting that exploration target into a JORC resource estimate - and that would get HAR to almost 700K ounces alone in resources:
(HAR says it can convert that exploration target into a JORC resource WITHOUT any new drilling, by re-assaying old core - so we could see that before the end of the year). (source)
(source)
How does HAR get to and pass 1M ounces?
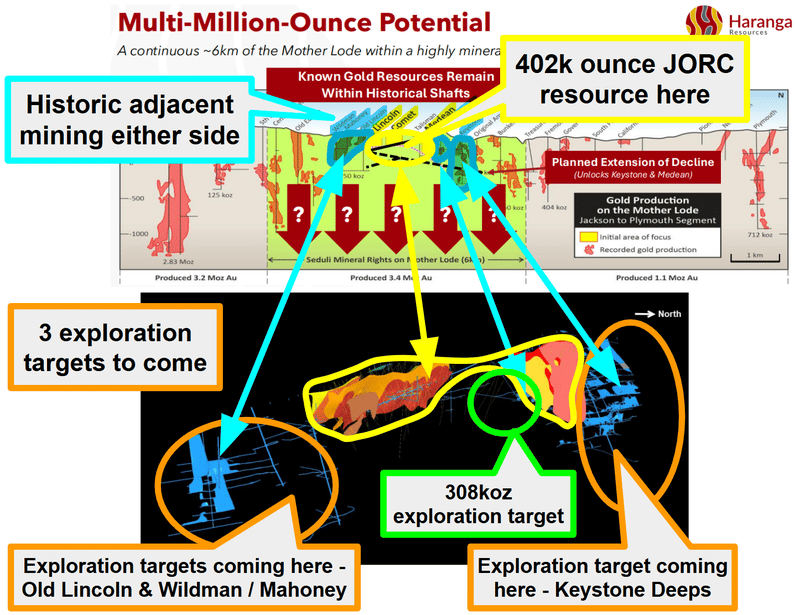
HAR also mentioned in a recent announcement that it was working on an exploration target across three of its other targets - expected to land before the end of the year.
- Old Lincoln
- Wildman / Mahoney
- Keystone Deeps
All three sit on the same 6km strike as the current resource.
All three have historical workings, historical drilling, and historical sampling data.
A few hundred thousand ounces across each of those, then converting to JORC resource estimates, and HAR COULD see its total JORC resource estimate across its assets go past that psychologically important 1M ounce level fairly quickly.
No guarantees of course, we are speculating on a future that may not eventuate.
Then there is the unknown, untouched exploration upside at depth.
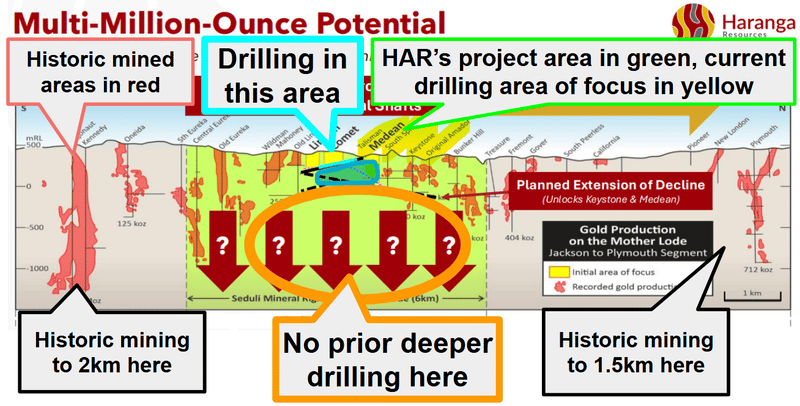
Some gold mines in the area were operated down to ~2km depths before they shut down.
The reason they shut down had nothing to do with running out of gold.
They shut down in the 1940s when the US government redirected mining manpower to the WW2 war effort.
On top of that, the gold price collapsed after the war, the mines never restarted, and the area had essentially been forgotten.
So the mining didn't stop because the gold ran out.
HAR’s resource today is defined across ~2km of strike and only down to depths of ~150m.
HAR still has over 6km of strike to test and over 1,000m at depth - if those old mines are anything to go by.
This image gives a sense of the exploration upside on the project:
(source)
We think the big moonshot exploration upside will come when HAR really starts going for it with drilling at depth.
HAR is currently drilling at the project, but this current program isn’t about going deeper - so we still have that to look forward to at some point over the coming months.
In the short term, over the next ~3-4 months we want to see HAR convert its old targets into exploration targets, its exploration targets into JORC resources and its JORC resource estimates into even bigger JORC resource estimates.
Which we hope is enough to spell out clearly to the market how HAR gets to that “multi-million ounce” potential it keeps talking about.
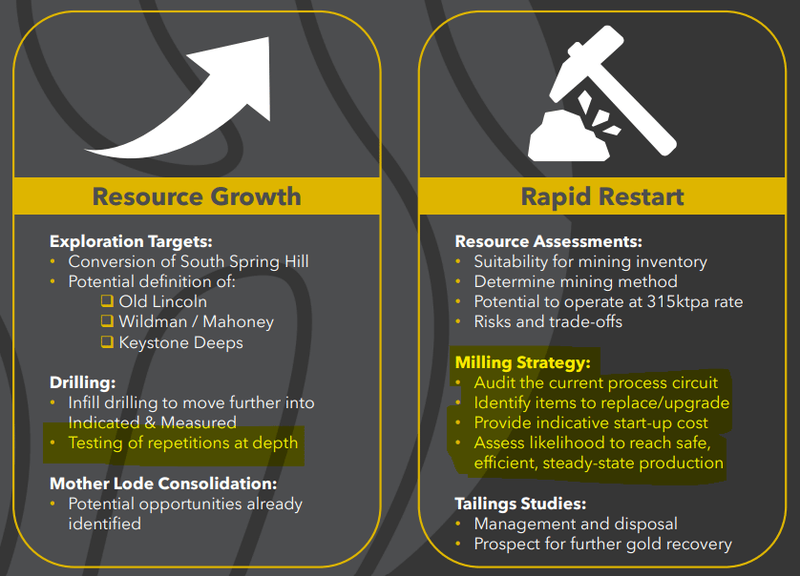
Ultimately, we like that HAR has optionality with how it moves its project forward.
HAR could do one of two things:
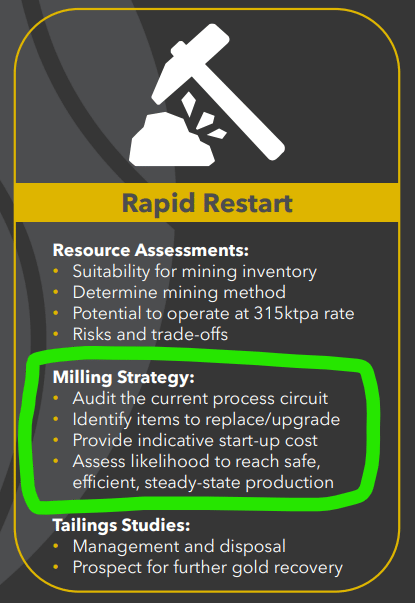
1. Decide to rapidly re-start gold production on its existing resources - HAR has previously said it would look to identify replacement/upgrades that it can then use to provide “indicative costs to start-up” the project. (source)
- AND
2. Grow the resources - going after the multi-million ounce potential here.
Or do both?
(source)
We would take either... or both at the same time.
It might depend on general gold sentiment and how much the market is prepared to fund HAR’s development.
Quick side note:
HAR’s new CEO (Patrick Mutz) seems to know a thing or two about building a mine. He was previously MD and CEO of Image Resources, where he took the company from advanced exploration to a producing mine in WA.
Patrick was behind securing a A$75M debt and equity funding piece to build that mine “on time and on budget”.
Image's market cap went from ~$15M to a high of ~$275M during that period. (source)
(the past performance of Image is not an indicator of the future performance of HAR.)
See more of our take on HAR’s new CEO here.
Hopefully Patrick, can do something similar with HAR, helping achieve our Big Bet as follows:
Our HAR Big Bet:
“HAR re-rates to a market cap greater than $200M by making new gold discoveries in California and progressing towards production or is acquired at a multiple of our initial entry price”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our HAR Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
How HAR stacks up against its ASX peers
We think HAR’s JORC resource estimate right now is strong enough to justify a larger market cap - especially relative to its ASX peers.
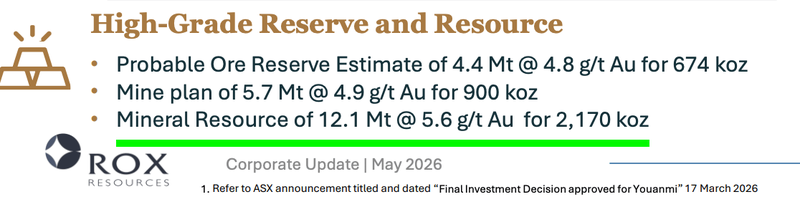
One comparison the market could draw is Rox Resources’ whose project has a 2.195M ounce gold JORC resource estimate with an average grade of 5.6g/t gold.
(source)
Rox’s market cap right now is ~$815M.
The company has a $350M debt facility in place to build all of the infrastructure needed to produce gold on its project and ~$150M in cash (~$90M drawn). (source)
So Rox’s enterprise value is somewhere around ~$1BN assuming a full debt drawdown (Enterprise Value = market cap minus cash, plus debt).
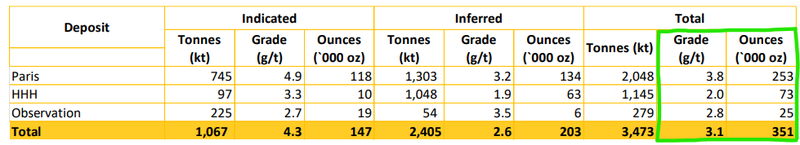
Another one is ASX listed Torque Metals which has a 351k ounce gold resource estimate with an average gold grade of ~3.1g/t gold.
(source)
Torque is currently capped at $132M and says it will have ~$32.7M cash in the bank following the raise earlier this month. (source)
So Torque’s enterprise value is ~$100M.
HAR’s current market cap is $24M with $6.3M cash in the bank at 30 June 2026.
That gives HAR an enterprise value of ~A$18M.
Here is how HAR compares to those two other companies on an EV/ounce basis:
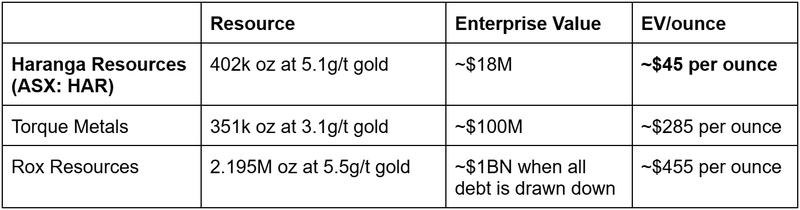
Note these are very rough calculations - Rox could end up needing more cash, or finish building their mine below budget, in which case the debt won't be needed.
A big part of Torque’s resource is open-pittable which could mean lower costs relative to HAR.
Let's not forget - HAR’s project also comes with:
- ~A$90M of historical capital infrastructure investment built by previous owners
- A 100% owned and permitted 315,000tpa gold processing plant (last operated in 2022)
- An 880m underground decline
- Offices, workshop, and laydown yard
- AND a Conditional Use Permit that allows production of gold
Of course, HAR will have to spend some cash getting its processing plant and infrastructure back into good standing too - that’s what those ‘Rapid Restart studies’ underway are all about. (source)
We have been to site - here is what we saw
We were on site with HAR’s team in June last year (check the full note here) - here is a quick overview of everything we saw:
- HAR’s fully built and operational site office
- HAR’s fully built, stocked and staffed workshop
- HAR’s built and permitted 315,000 tpa gold processing plant
- HAR’s 880m decline (the tunnel to the gold)
- The laydown yard, and our meeting with locals that know the project well
- The historic mines in the area (that have produced ~7.7 million ounces of gold in the past)
- The old mining town that surrounds HAR’s project
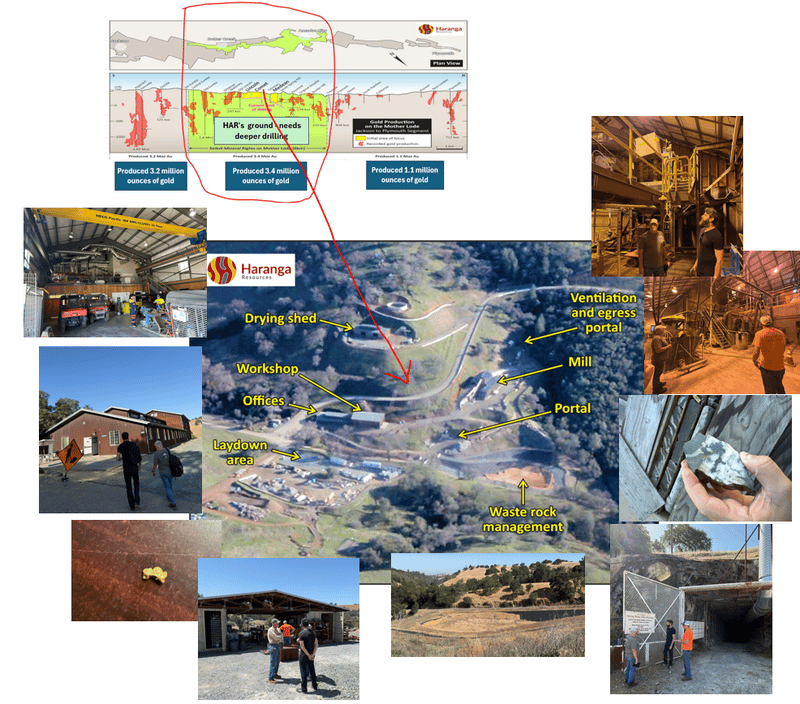
(source - our full write up and pics from a site visit last year, see that here)
What's Next for HAR?
🔄 Phase 2 underground drilling at US asset (currently underway)
HAR is now more than halfway through its second phase of drilling.
The main thing we want to see from the rest of this program is the continuity of mineralisation between the two resources HAR has already defined.
And ideally, HAR is able to convert some of its inferred resources into indicated status so it can be used in feasibility studies.
🔄 3x more exploration targets (H2 CY26)
HAR is working on an exploration target across three of its other targets:
- Old Lincoln
- Wildman / Mahoney
- Keystone Deeps
All three sit on the same 6km strike as the current resource.
All three have historical workings, historical drilling, and historical sampling data.
🔄 Scoping study for a ~315ktpa mining operation
HAR’s prior presentation said it would start identifying items to replace/upgrade and the big one “provide an indicative start-up cost”.
This will be the first time we get a look at any capital costs required to bring the processing plant (and associated project infrastructure) back online.
(source)
What could go wrong?
The near-term risk for HAR is around “exploration risk”
HAR is more than halfway through a drill program on its US project.
There is no guarantee HAR finds anything economic with the rest of this drill program - IF results are below market expectations then HAR’s share price could suffer negatively.
Exploration risk
There is no guarantee that HAR's upcoming drill programs are successful and HAR may fail to find economic gold deposits.
Source: "What could go wrong" - HAR Investment Memo 25 June 2025.
Other risks
Like any small-cap gold exploration and development company, HAR carries significant risk, here we aim to identify a few more risks.
While having an existing processing plant and underground decline is a huge head start, refurbishing infrastructure that has sat idle since 2022 can uncover unexpected maintenance issues. If refurbishment and start-up costs come in higher than expected in the upcoming scoping study, project economics could be dampened.
HAR held $6.3M in cash at 30 June 2026, but running drilling programs alongside engineering studies can burn through capital quickly. HAR being pre-revenue may need to raise further equity or debt down the track, which creates the risk of future shareholder dilution.
Relying on historical workings and legacy data to define exploration targets does not guarantee that those ounces will successfully convert into JORC-compliant resources.
Operating in California also carries environmental and regulatory scrutiny, meaning any amendments or compliance issues regarding existing permits could lead to unexpected development delays.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our HAR Investment Memo
Our Investment Memo provides a short, high-level summary of our reasons for Investing.
We use this memo to track the progress of all our Investments over time.
Click here to read our HAR Investment Memo where you will find:
- What does HAR do?
- The macro theme for HAR
- Our HAR Big Bet
- What we want to see HAR achieve
- Why we are Invested in HAR
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.