AUZ: Why is our scandium Investment running on strong volumes and (almost) no news?
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 2,946,000 AUZ Shares at the time of publishing this article. The Company has been engaged by AUZ to share our commentary on the progress of our Investment in AUZ over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
Why is our Investment Australian Mines (ASX:AUZ)’s share price running on strong volumes and no news?
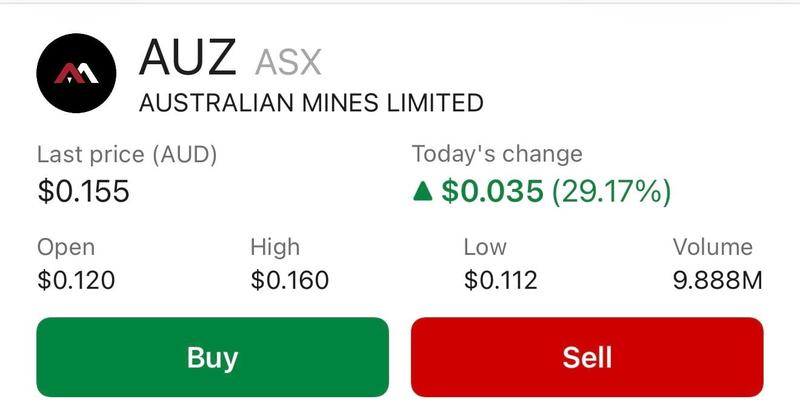
The ASX was wondering the same thing yesterday...
and sent AUZ a “please explain why your share price is going up so much when you haven't released any news” information request.
AUZ’s response was:
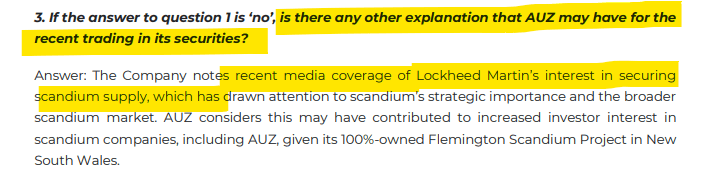
So AUZ reckons it was recent media about $211BN US military contractor LockHeed Martin’s interest in scandium that contributed to its share price run.
AUZ went on to say they have also been hitting a few investor conferences and are changing their name to “First Scandium” - read the full response to the ASX here.
AUZ owns 100% of one of the highest grade scandium assets in the world capable of providing scandium into the west’s supply chains.
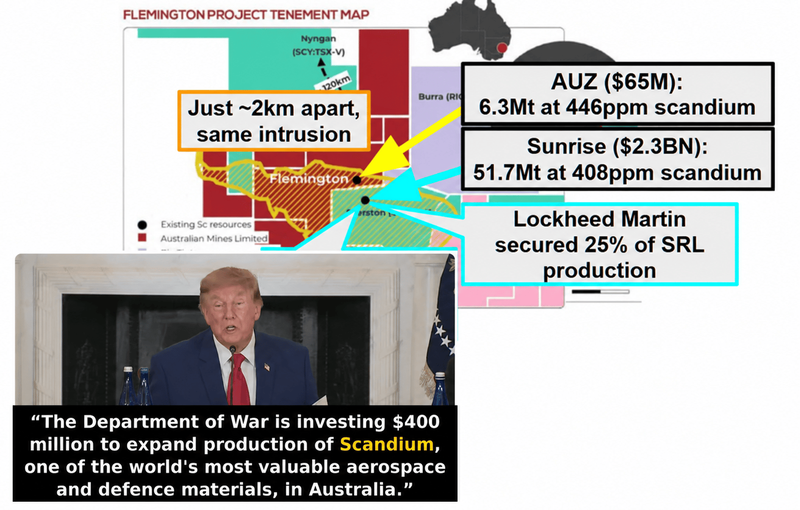
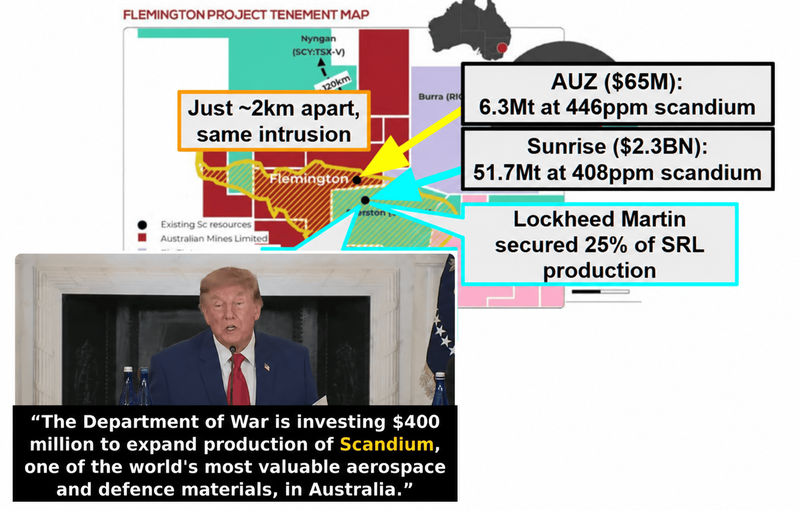
(and it sits next to its next door to $2.3BN Sunrise Energy Metals which received a US$400M commitment from the DoW and a shout out from Trump)
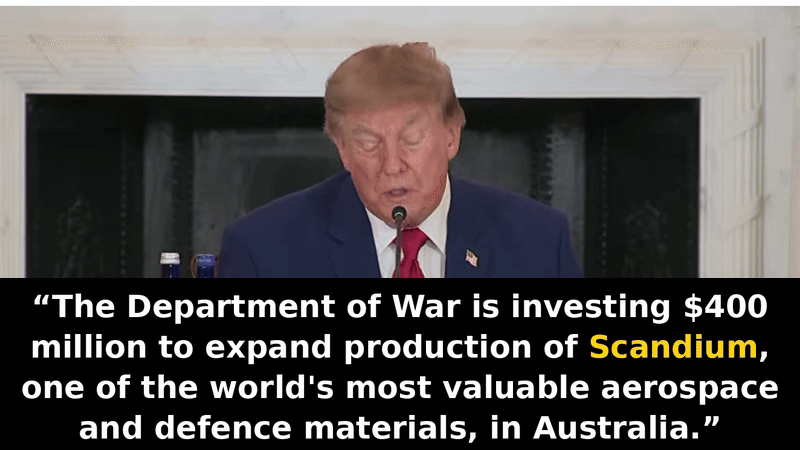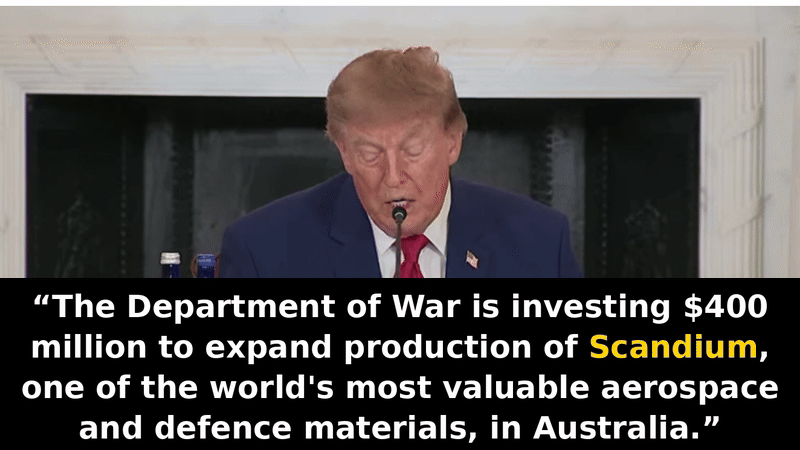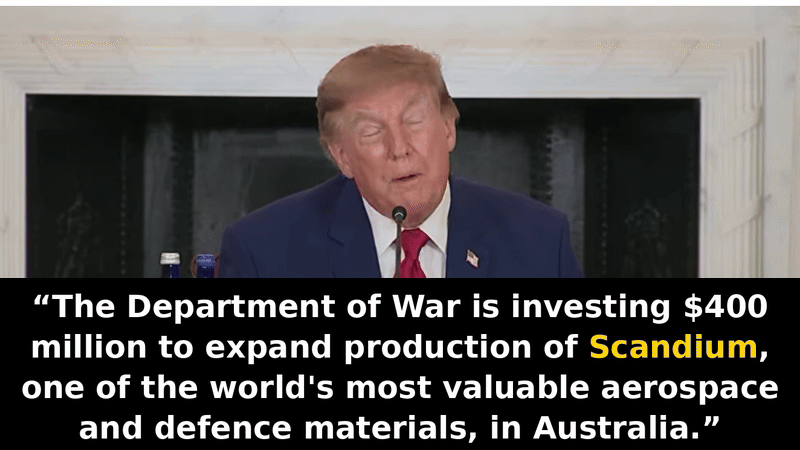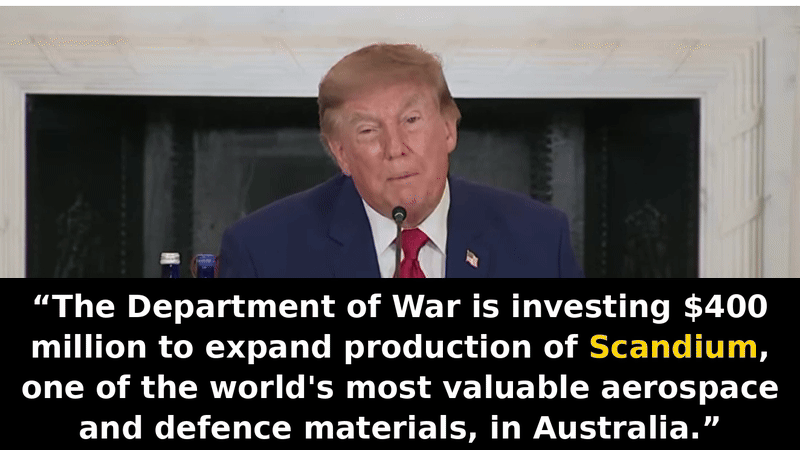
(Here is that Trump shoutout)
Scandium is used in AI data centres and has military applications in fighter jets, missile systems and AI robots.
The scandium media we saw in recent days was around the deal signed between USA defence giant Lockheed Martin and AUZ’s neighbour, the $2.3BN Sunrise Energy Metals:
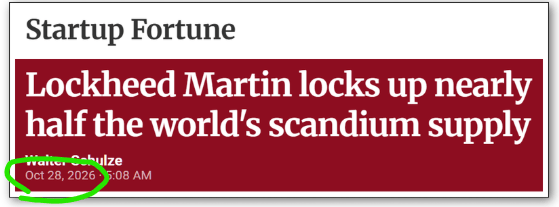
(source)
Lockheed Martin is the world’s largest defence contractor by revenue.
It’s the company that builds F-35 fighter jets and PAC-3 missiles - and it has an offtake option deal with AUZ’s direct neighbour Sunrise.
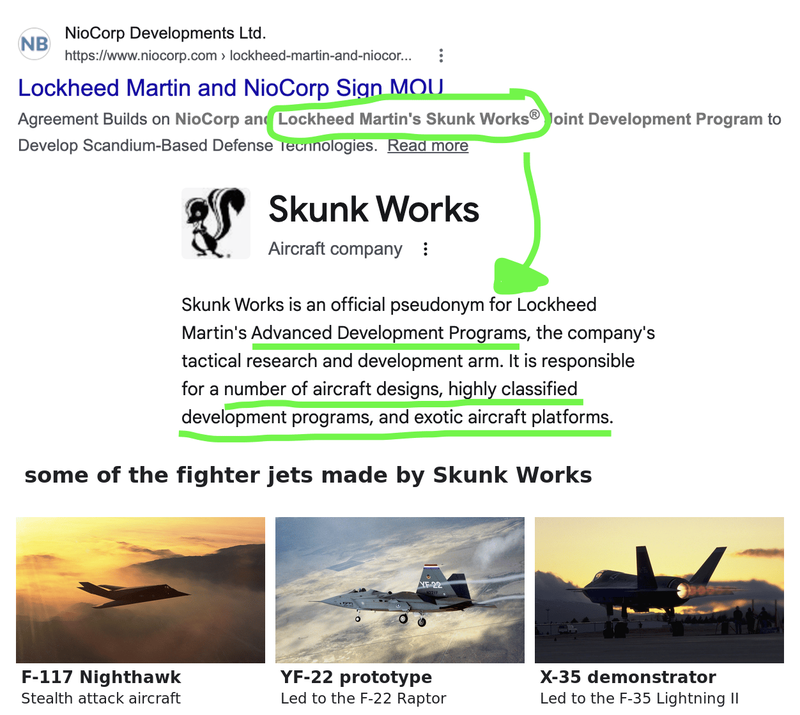
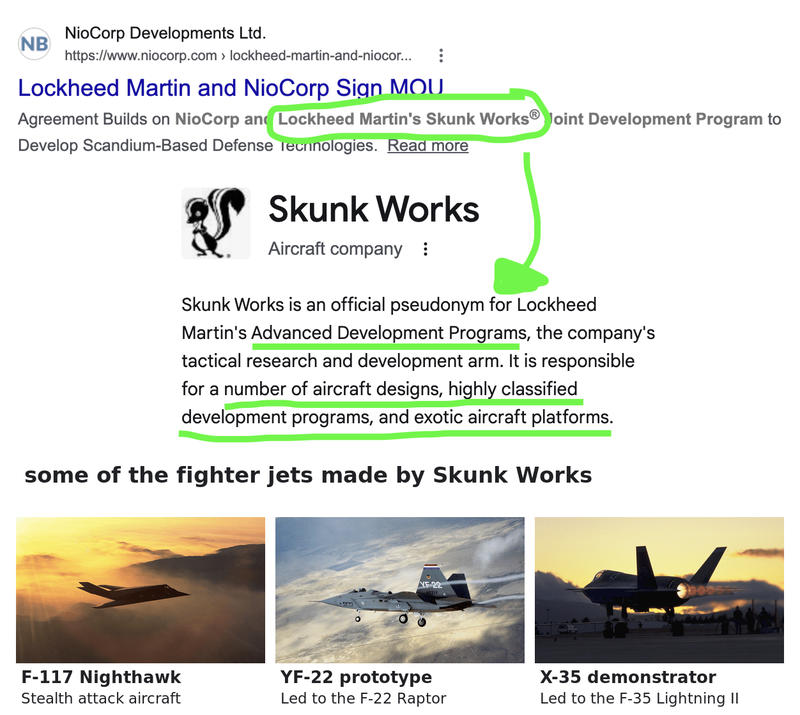
In August, Lockheed Martin did a deal with another scandium company based in the US as part of its “Skunk Works joint development program” (source) being partially funded by a US$10M Department of War grant. (source)
Skunk Works is the Lockheed division that built the U-2, the SR-71 Blackbird and the F-117 stealth fighter - i.e. the “secret-projects” shop.
We have previously written about the AI data centre demand story for the critical metal scandium (more on that later today).
However in parallel, aside from data centres, it looks like Lockheed is cooking something big up in the military space too (akin to what the Soviets did with their military in the 70’s and 80’s)
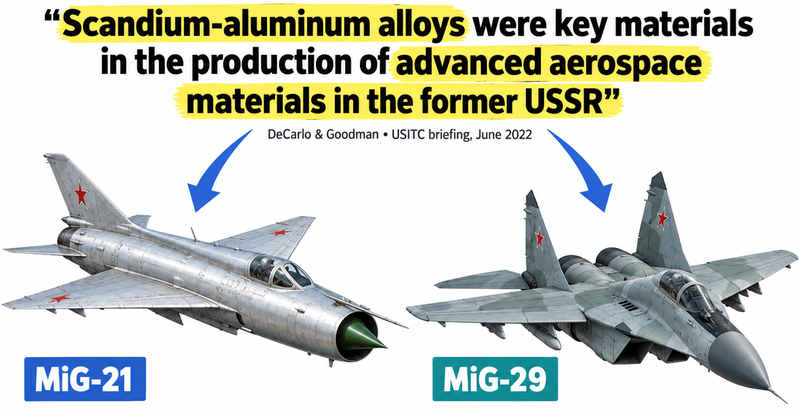
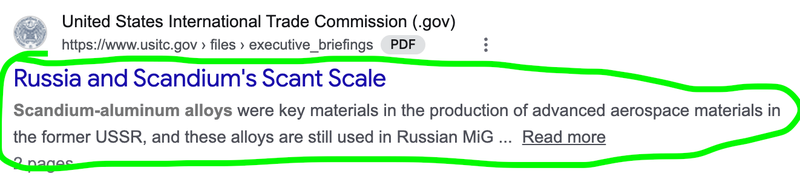
Fun Fact - during the 1980s, Soviet metallurgists started using aluminium-scandium alloys in fighter jets like the MiG-21 and MiG-29, keeping the application classified for years.
(a lot more on this later in today’s note)
We think scandium demand is going to surge - and we may not even know why... yet.
BUT if we look at where the USA is throwing the most money and the most quickly...
THAT is where we start to think about what the public DOESN’T know about supply and projected demand.
(especially for military and advanced weapons uses)
and what DON’T we know about future scandium demand that is causing the US Department of War to throw so much money at it so quickly?
Its secret military stuff - why would they publish what they need all this scandium for?
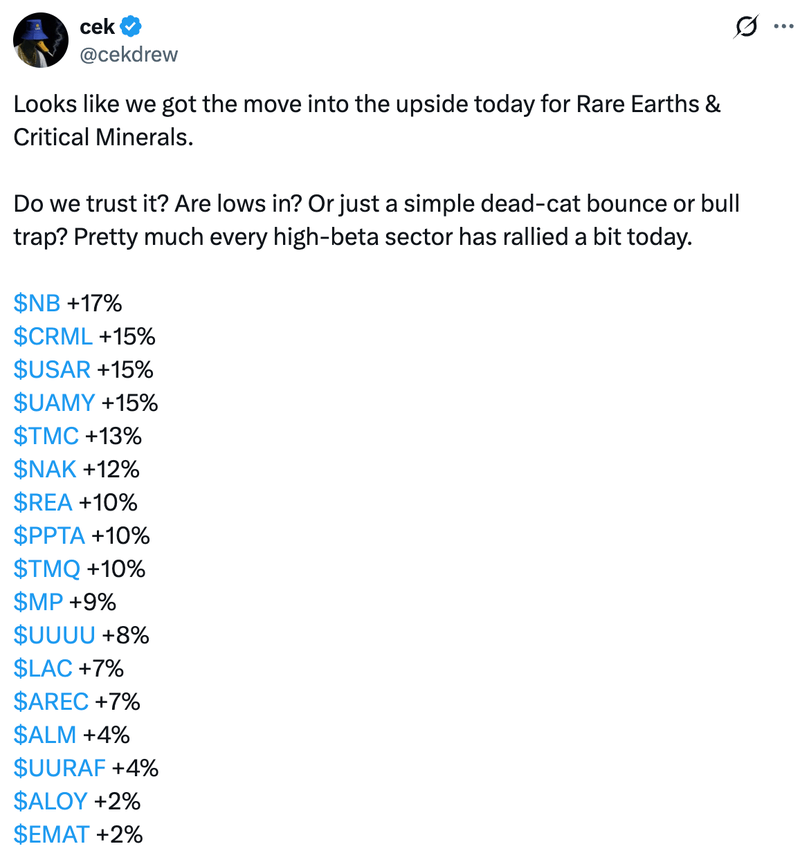
Anyways, we could be overthinking it - AUZ’s share price could have just been responding to the big green day US critical minerals stocks had on Tuesday (after a pretty rough couple of months):
(source)
AUZ owns one of the highest grade scandium deposits in the world
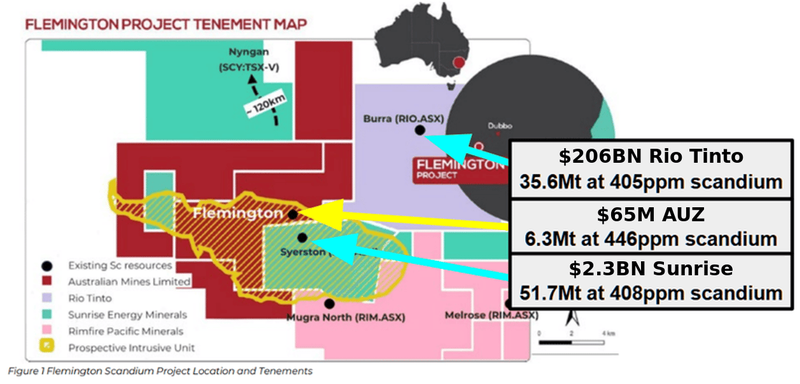
AUZ’s project is one of only three pure-play scandium deposits on the planet with grades above 300ppm.
Of those three, AUZ’s is the highest grade - the other two projects are owned by $206BN Rio Tinto and $2.3BN Sunrise Energy Metals.
AUZ’s current market cap is only $65M.
(source)
Sunrise’s project next door to AUZ has received:
- A US$400M conditional loan commitment from the US Department of War. (source)
- An offtake option deal from defence contractor Lockheed Martin. (source) and
- A shoutout from the US President himself, Donald Trump, at a mining roundtable in the US in August. (source)
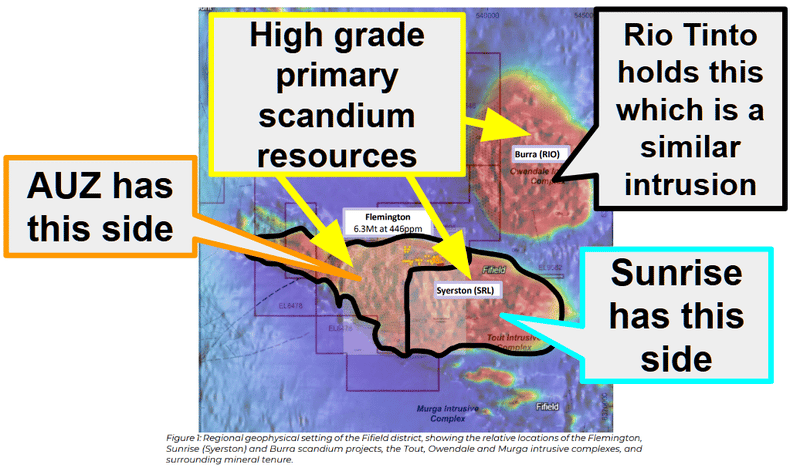
AUZ’s project sits directly on the same geological intrusion that hosts Sunrise’s project:
(source)(source)(source)(source)
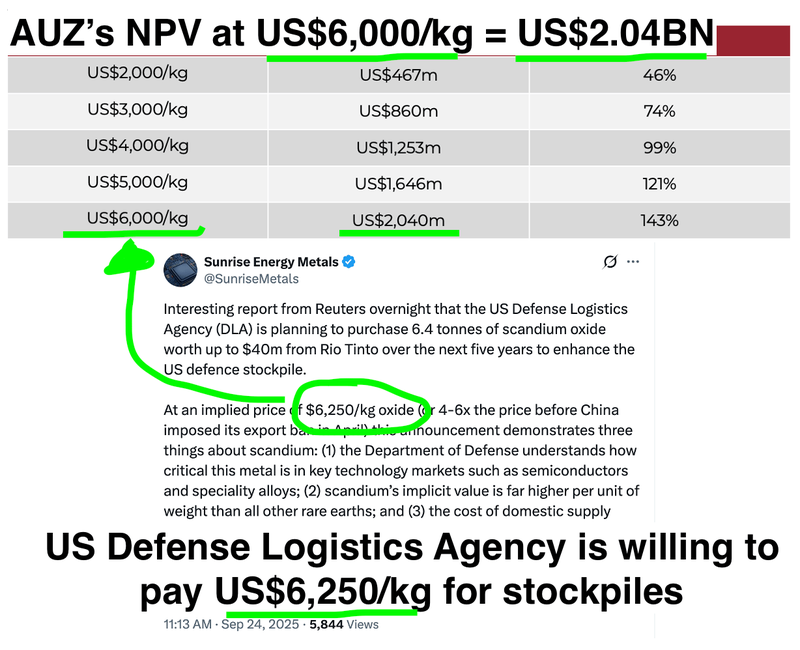
AUZ’s project also has a scoping study showing a US$860M NPV from US$125M of CAPEX at a US$3,000/kg scandium price.
If we use a scandium price of US$6,000/kg, the NPV rises to US$2.04BN.
That price is not unreasonable.
The US Defence Logistics Agency’s planned scandium stockpile purchase from Rio Tinto has an implied ceiling of ~US$6,250/kg. (source)
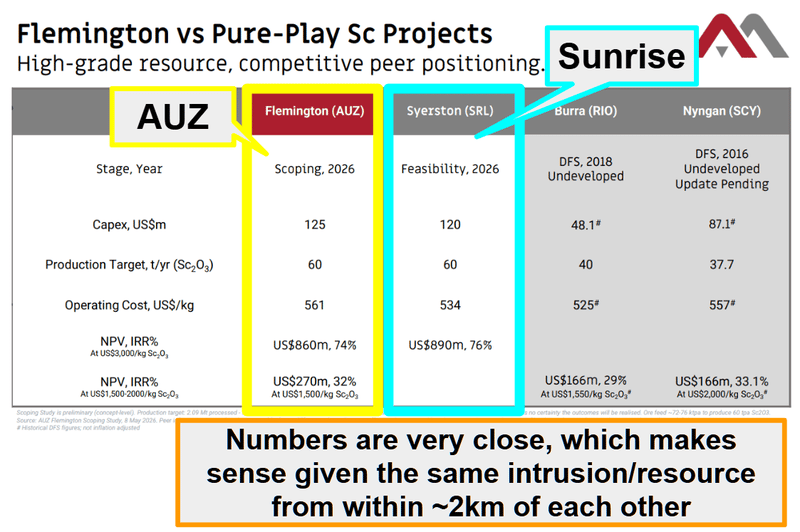
AUZ’s project also has the same planned output as Sunrise’s - ~60 tonnes a year of scandium oxide - from three shallow pits instead of Sunrise’s planned 13.
Right now, Sunrise is capped at ~$2.3BN.
AUZ is capped at ~$65M.
Here is a current side by side comparison of Sunrise and AUZ’s assets:
(source)
We are Invested in AUZ to see it progress its asset - closer to the position Sunrise’s asset is in AND hopefully along the way bridge that valuation gap to Sunrise.
(currently that is a ~35x multiple gap).
Remember AUZ’s asset literally sits on the same geological intrusion as $2.4BN Sunrise’s:
(source)
Naturally it would make a lot of sense if the two companies came together.
BUT we are Invested in AUZ to see it bridge its gap by progressing its own asset.
Currently the main differences between Sunrise and AUZ from an asset perspective are:
- Study stage - Sunrise has a Definitive Feasibility Study and an Ore Reserve.
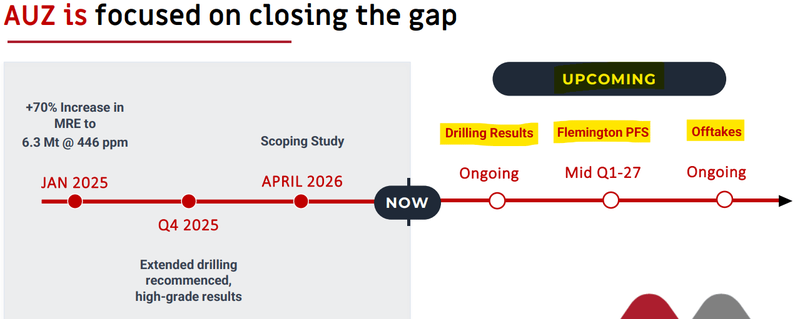
🚨 AUZ has a Scoping Study, with a Pre-Feasibility Study due in mid-Q1 2027. (source)
- Offtake and funding - Sunrise has a conditional US$400M loan commitment from the US government AND an offtake option with defence contractor Lockheed Martin.
🚨 AUZ has offtake discussions “ongoing” and no government funding/support (YET).
- Corporate - Sunrise is re-domiciling to the US and going for a primary NASDAQ listing.
🚨 AUZ is ASX listed for now and is only also listed on the OTCQB (no mainboard US listing YET).
- Size versus grade. Sunrise’s resource is ~8x the tonnage.
🚨 AUZ’s is the higher grade (446ppm vs 408ppm) with a simpler three-pit mine plan versus Sunrise’s 13 planned pits.
- ✅ Scale - Both are planning production of scandium at ~60 tonnes a year - but AUZ’s PFS is also assessing 120 and 180 tonne a year cases. (source)
In September AUZ appointed a specialist PFS team - with the PFS due in mid next quarter (Q1 2027).
Drilling is also “scheduled to commence following receipt of the required exploration activity approval” from the regulator. (source)
We think the PFS will be a big step toward AUZ hopefully closing that valuation gap with Sunrise - especially for anyone looking at which project to support - where being advanced matters.
(source)
But hold on... what actually is scandium and why care now?
Right now a big demand driver for scandium globally is for systems powering AI data centres.
NYSE listed, US$67BN capped, Bloom Energy uses scandium to make solid-oxide fuel cells that give AI data centres on-site power without grid involvement.
Each of those fuel cells is ~10% scandium oxide. (source)
Bloom says it believes it is “the world’s largest consumer of scandium oxide” (source) - and we have seen estimates that it swallows up ~74% of global demand. (source)
Bloom is one of the AI data centre buildout poster boys over in the US - so understandably its share price has been mooning for around two years now too:
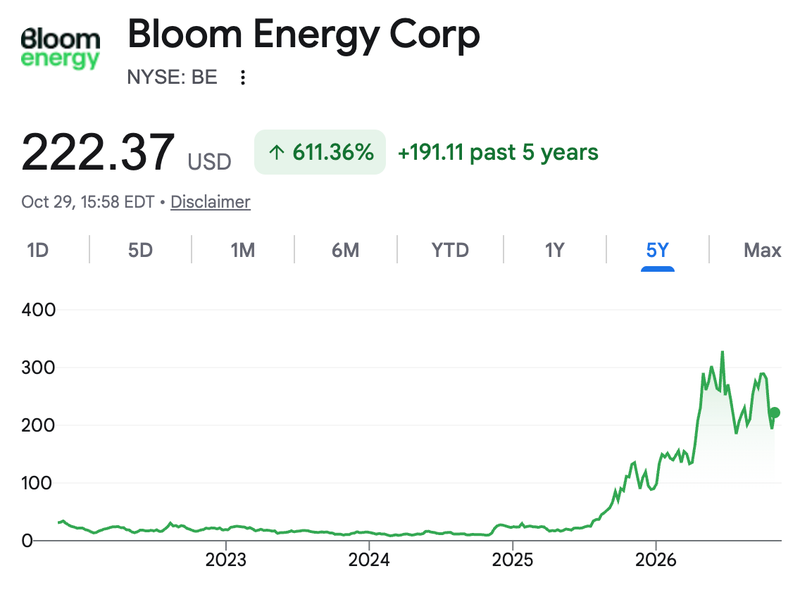
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
A few weeks ago Bloom announced a 702MW fuel cell installation in Wyoming for Google. (source)
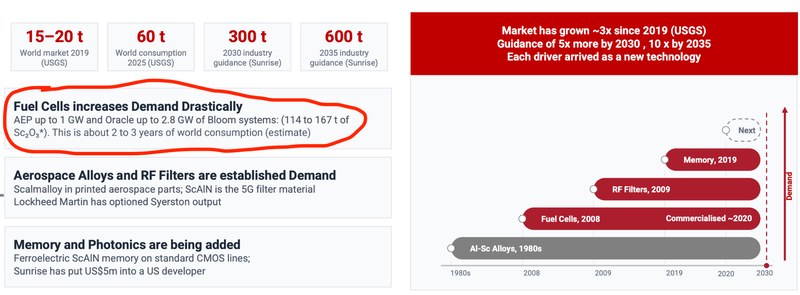
And a few weeks before that, Bloom did deals with Oracle for up to 1GW and up to 2.8GW - which on its own would need ~114 to 167 tonnes of scandium oxide.
For context - the entire world produced ~80 tonnes of scandium oxide last year - SO THAT one deal would take ~2 years of world consumption. (source)
(source)
If Bloom does what it says it will, then the market could become short scandium in a big way very quickly.
See our deep dive on the Bloom bull case here (including coverage of a short report on the stock, Bloom’s response, and why we think scandium project owners win in either scenario):
So what even is scandium and who are NYSE listed Bloom Energy?
That Bloom demand alone could warrant bringing a few scandium mines online.
BUT the real dark horse for demand COULD be from the military industrial complex.
Not just AI data centres - scandium is also needed for military uses - including fighter jets
Scandium is also used to make aluminium stronger, lighter and more weldable. (source)
Fun Fact - during the 1980s, Soviet metallurgists started using aluminium-scandium alloys in fighter jets like the MiG-21 and MiG-29, keeping the application classified for years.
(making the Soviet planes lighter, more fuel efficient, longer range and with higher payload capacity)
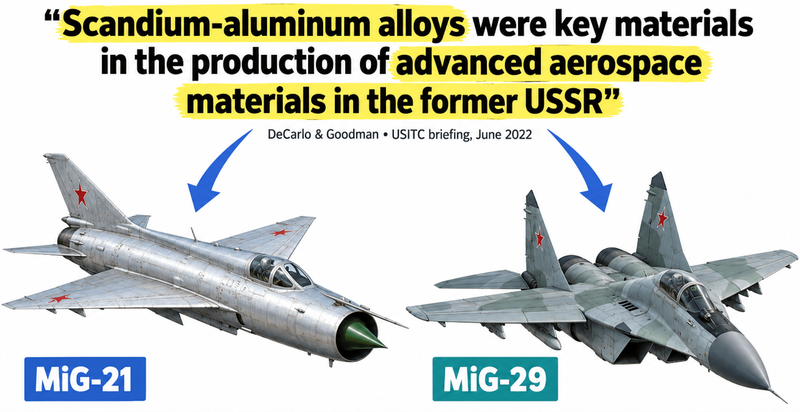
According to the US International Trade Commission, the scandium-alluminium alloys were key parts of the Soviet “advanced aerospace materials” advantage AND are “still used in Russian MiG aircrafts today”.
(source)
Up until now, the West hadn’t really had enough control of its supply chains to go hard on developing military tech using scandium.
But now we have $146BN Lockheed Martin - the world’s largest defence contractor who builds F-35 fighter jets and PAC-3 missiles - looking to lock up supply from two scandium mines:
- October 2025 - Sunrise Energy Metals (AUZ’s neighbour): an option over the first 15 tonnes a year of scandium oxide for five years. (source)
- August 2026 - NioCorp (NASDAQ: NB), Nebraska: a non-binding MOU to buy up to 15 tonnes a year for ten years, as oxide or as finished scandium-aluminium alloy. (source)
What do they know that we don’t?
We think Lockheed wouldn’t be lining up this much supply if it didn’t have an intended use case for it.
There is nothing announced by Lockheed about what they will do with the scandium.
BUT we did notice that the NioCorp deal was on top of Lockheed Martin’s Skunk Works joint development program (source) being partly funded by a US$10M Department of War grant. (source)
WHICH is going to prototype scandium-aluminium alloy components “that will expand the capabilities of modern fighter aircraft.”
Remember, Skunk Works is the Lockheed division that built the U-2, the SR-71 Blackbird and the F-117 stealth fighter - the secret-projects shop.
Looks like they are cooking something big up... and who knows what else Lockheed might get up to when they start to feel comfortable about a secure reliable supply of scandium being at its disposal...
Lockheed is the first to move from the defence contractors - we think more could follow
So Lockheed has done deals with two companies - Sunrise and NioCorp (one in Australia and one in USA).
As far as we can find, no other big defence contractor has done a scandium deal yet.
We think that IF any of the other big defence guys start looking for supply - AUZ’s project could be one they (at the very least) watchlist.
Especially with AUZ’s project being in a part of the world these guys now know and understand (thank you Lockheed and Donald Trump):
(no guarantees of course - AUZ has no offtake, no MOU and no government funding right now)
Ultimately, we are Invested in AUZ for it to achieve our Big Bet as follows:
Our AUZ Big Bet:
"AUZ re-rates to a $500M+ market cap by advancing its scandium project toward a development decision and/or becomes the subject of a corporate transaction (takeover, JV, or US-listing event) at multiples of our Initial Entry Price."
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our AUZ Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What we want to see next from AUZ
🔄 Pre-Feasibility Study for scandium project
We think this could be the next major catalyst for AUZ.
Here are the milestones we are tracking:
✅ PFS formally commenced and fast-tracked (May 2026)
✅ Specialist PFS consultant team appointed (September 2026)
🔄 Metallurgy, geotech, tailings, environment and water studies
🔄 Assessment of the 120tpa and 180tpa scale-up cases
🔲 PFS completed (mid-Q1 2027)
🔲 Drilling to grow its scandium resource
We want to see AUZ drill out and grow its scandium resources - so that the market can start to make stronger comparisons between AUZ and Sunrise’s asset.
Here are the milestones we are tracking:
🔄 Drilling approvals (lodged - drilling to start once received)
🔲 Drilling commences (~50 holes / ~1,250m)
🔲 Drilling results
🔲 Corporate/commercial progress for scandium asset
We also want to see AUZ execute the Sunrise playbook and land some (or all) of the following:
🔄 Offtake / strategic partner discussions
🔲 First offtake, MOU or government-linked funding
🔲 Get interest from US investors OR get listed in the US
🔲 Name change to First Scandium approved (AGM, 24 November)
What could go wrong
The single biggest risk right now is still “Single-customer demand risk”.
The scandium demand story leans heavily on ONE company - Bloom Energy.
Bloom’s share price fell after it released its results last week and a shareholder class action is currently in place (Bloom says it is without merit). (source)
If Bloom’s ramp slows, or if the market stops believing it, scandium stocks would be sold off with it - regardless of what AUZ does.
Source: “What could go wrong” - AUZ Investment Memo 12-Aug-2026
Other risks
Like any early-stage critical minerals development company, AUZ carries significant risk, here we aim to identify a few more risks.
A name change does not change the economics of a project. The re-rate we are hoping for depends on the PFS, drilling, offtake and funding - not the ticker.
The Flemington drilling program is still waiting on NSW regulatory approval. Delays in that approval, or drilling that fails to extend the resource, would push out the timeline for stronger comparisons to Sunrise.
The US-China trade truce deadline in January could cut either way for sentiment. A lapse would likely lift critical minerals stocks on urgency; an extension could take some of the heat out of the thematic in the short term, even though scandium’s own restrictions are unaffected.
AUZ will need further capital to complete the PFS, drill, and advance toward development. With ~$5.2M in the bank at 30 June, future raises are likely and could dilute existing shareholders.
The Lockheed deals we reference are with Sunrise and NioCorp - not AUZ. AUZ has no offtake, MOU or government funding today, and there is no guarantee it secures any.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our AUZ Investment Memo
Our Investment Memo provides a short, high-level summary of our reasons for Investing.
We use this memo to track the progress of all our Investments over time.
Our AUZ Investment Memo covers:
- What does AUZ do?
- The macro theme for AUZ
- Our AUZ Big Bet
- What we want to see AUZ achieve
- Why we are Invested in AUZ
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.