AUZ: Ultra high grade scandium drill hit at Sconi Project (the “other” project)
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 2,946,000 AUZ Shares at the time of publishing this article. The Company has been engaged by AUZ to share our commentary on the progress of our Investment in AUZ over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
An ASX small cap stock.
Going from 10c to 18c in 12 trading days, and trading over $1M+ in volume a day...
In this market?
Without any material newsflow.
Why?
It is a scandium stock...
So we thought it could be running because of recent media reports of $205BN US military contractor Lockheed Martin's interest in the critical mineral scandium. (source)
(Scandium is used in AI data centres and has military applications in fighter jets, missile systems and AI robots.)
But those media reports were from a few weeks ago now - that is an eternity in small cap markets.
Our scandium Investment Australian Mines (ASX:AUZ) has just kept running.
Looking at the chart, it looks like AUZ’s share price is approaching a level where IF it can break free of ~20c, it could really go on a run. No guarantees of course - we can and do get things wrong.
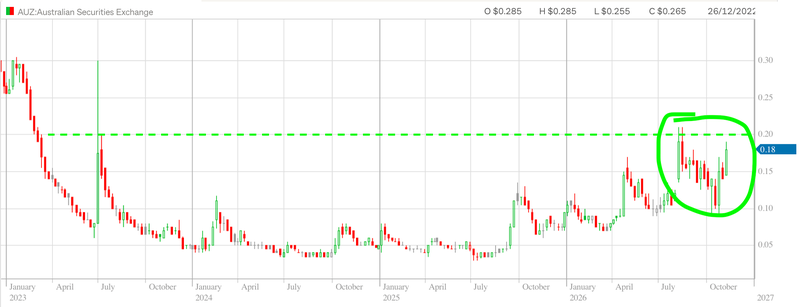
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
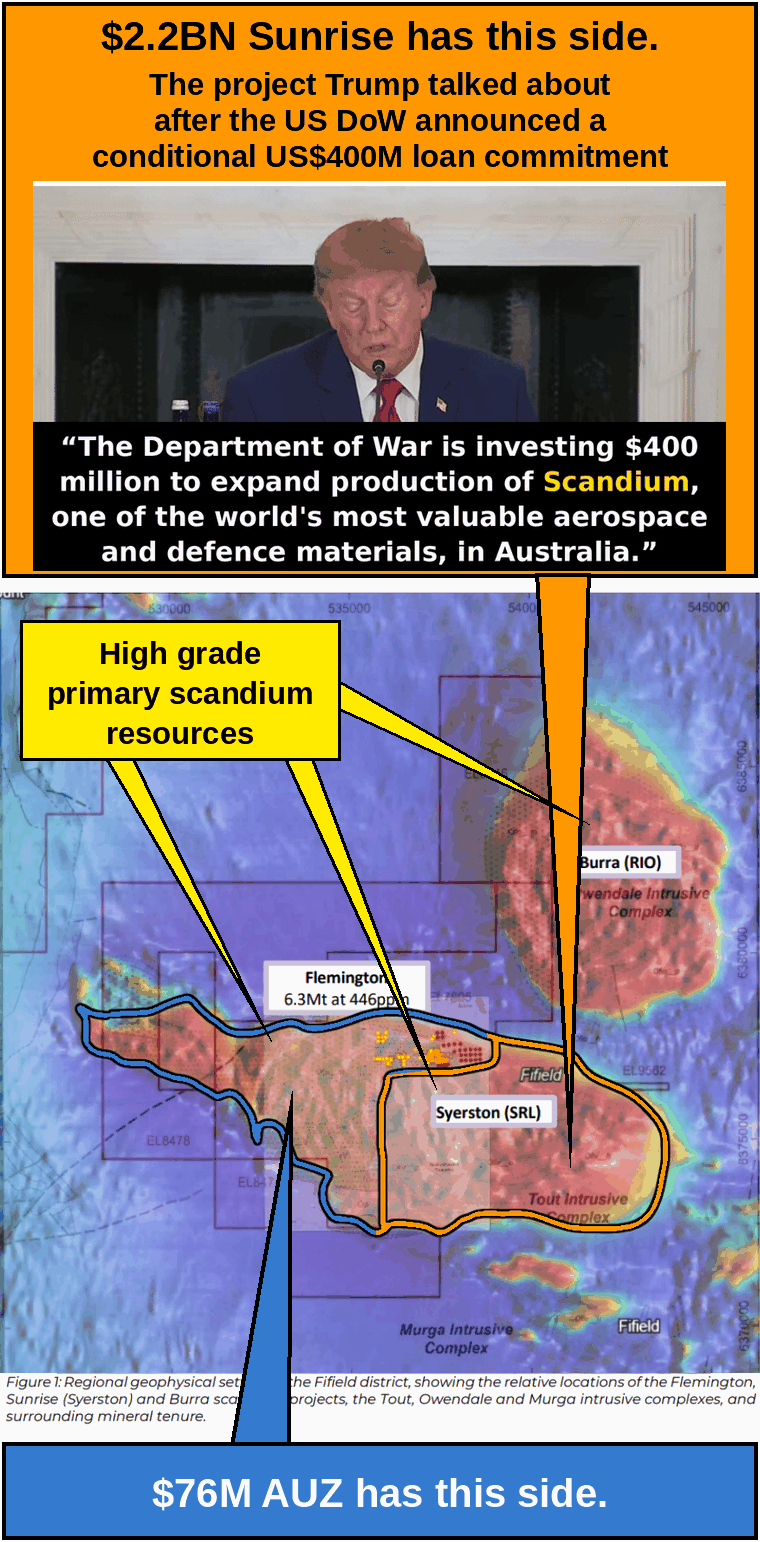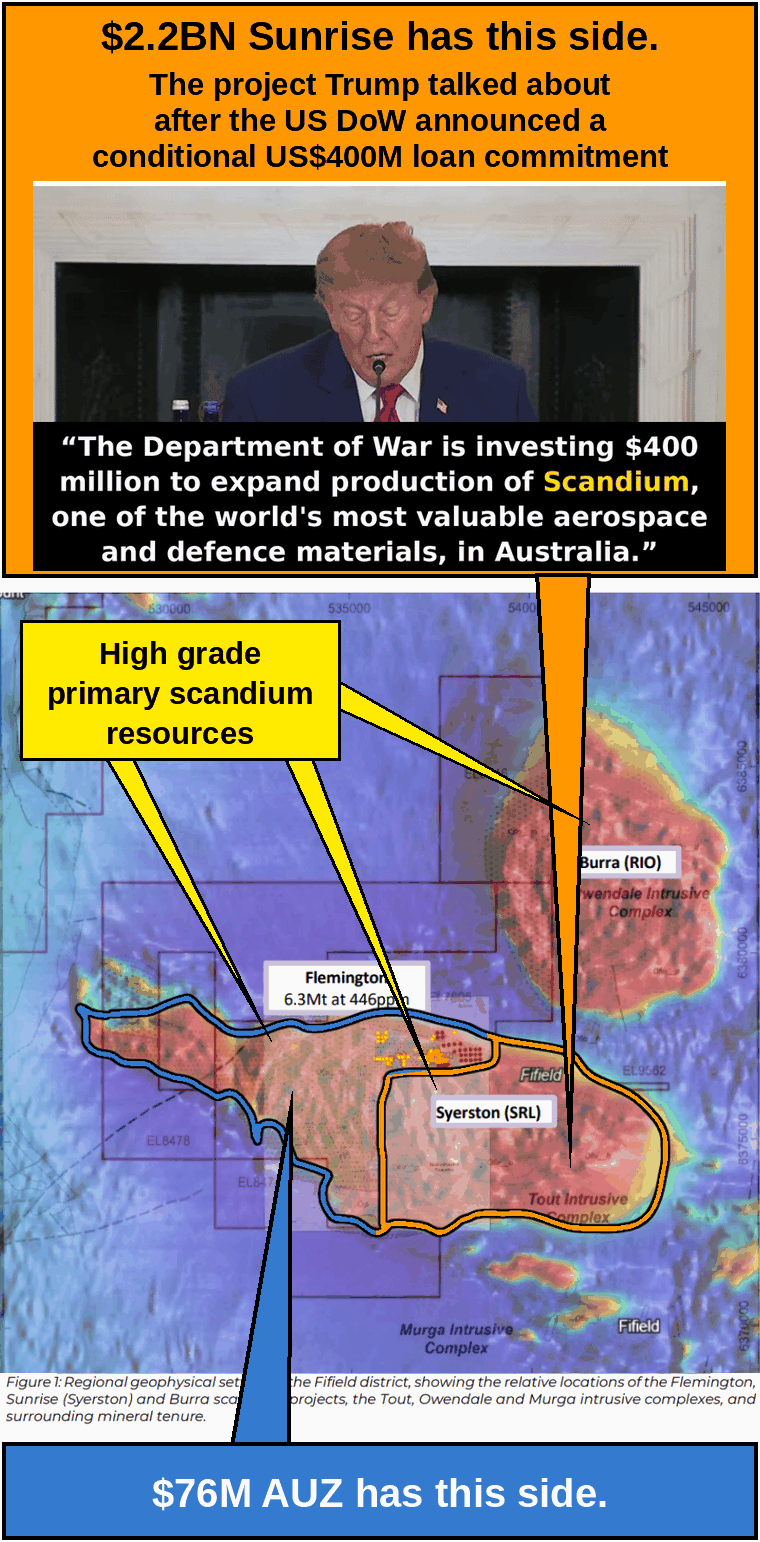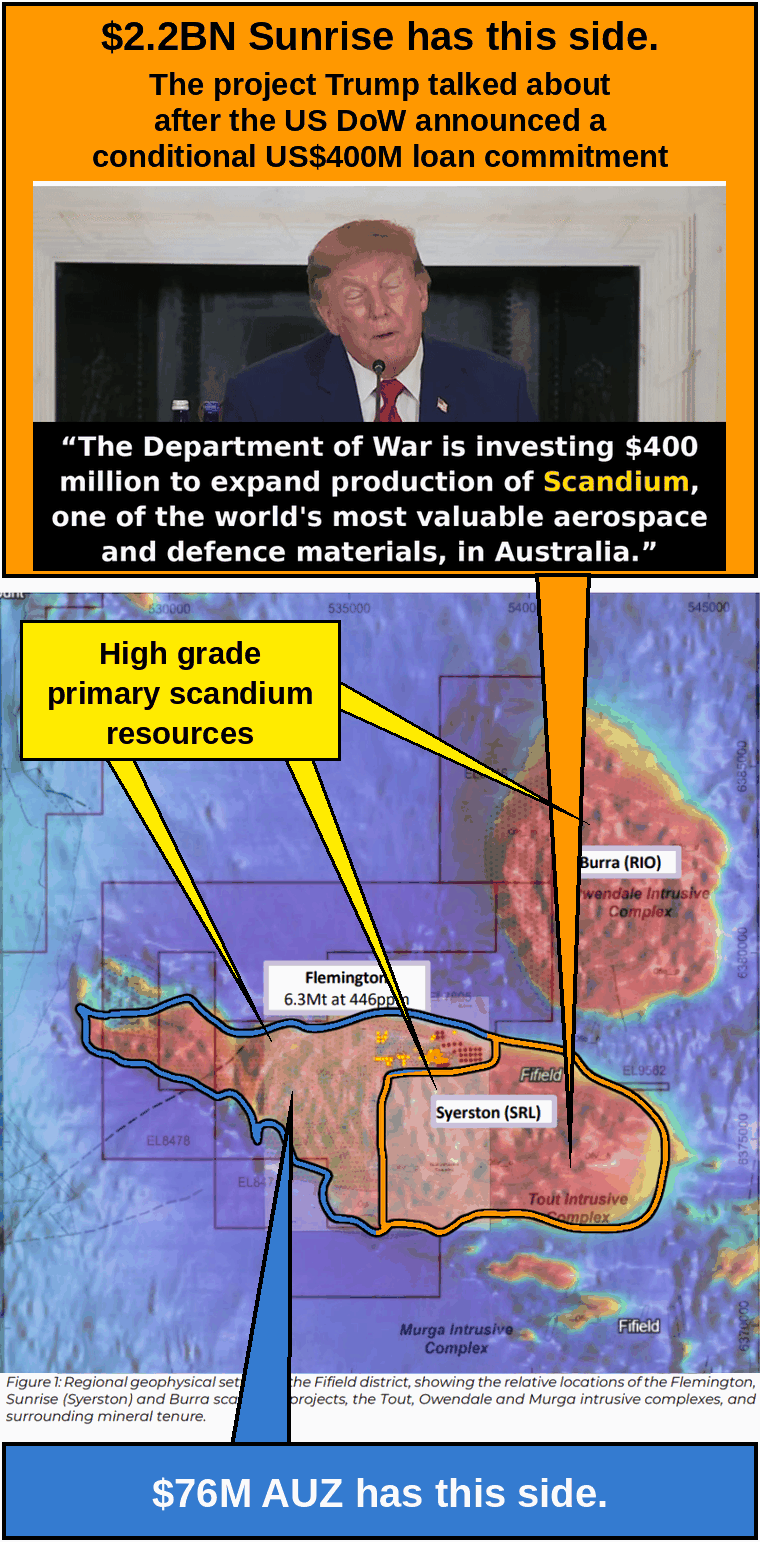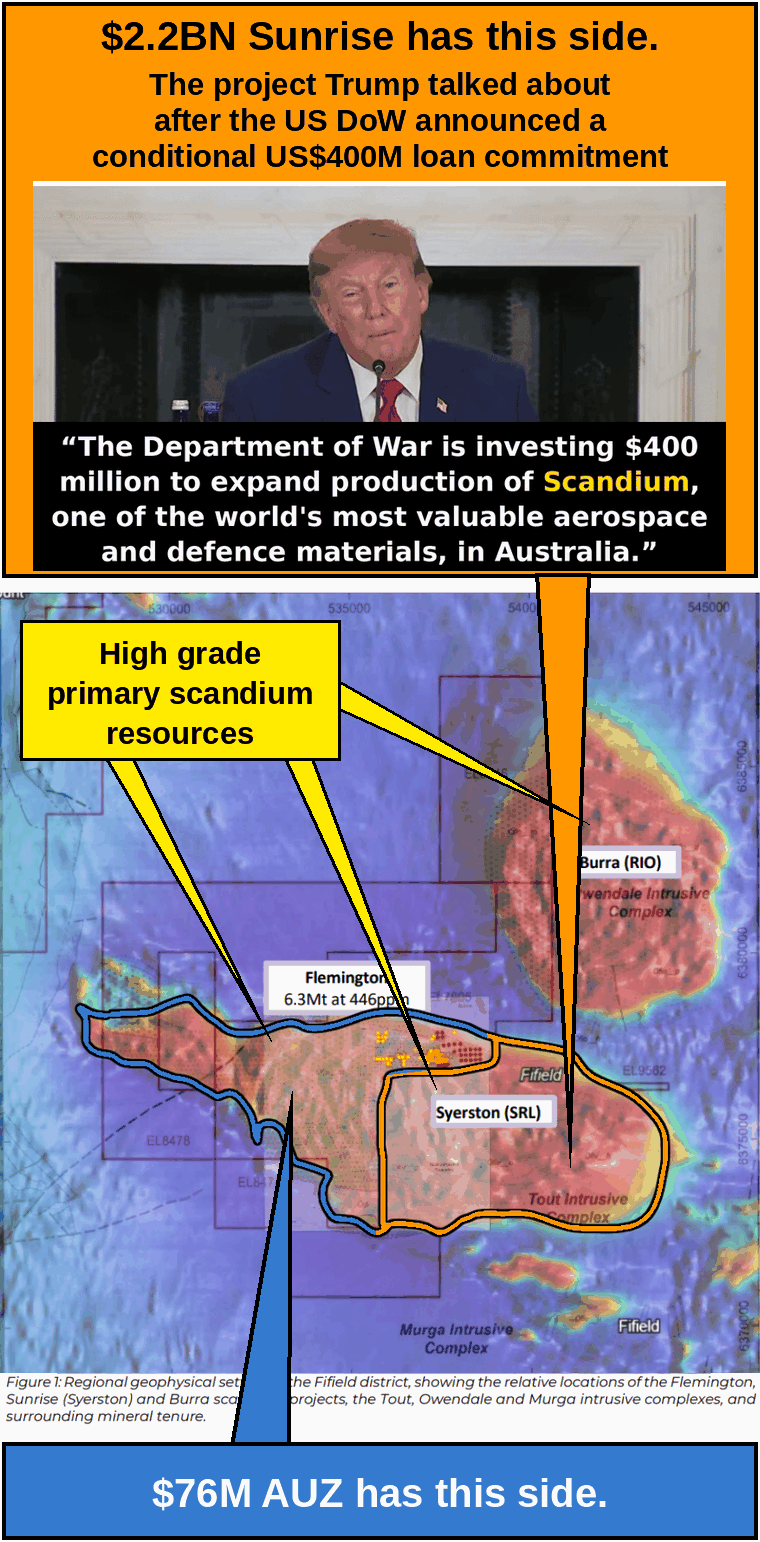
$76M capped AUZ owns 100% of one of the highest grade scandium assets in the world.
AUZ sits directly next door to another scandium developer - the $2.2BN capped Sunrise Energy Metals.
AUZ’s neighbour Sunrise received a conditional US$400M loan commitment from the US Department of War, a shout out from President Trump and an offtake option deal from Lockheed Martin:
(source)
In the last two days, AUZ has:
1. Appointed global asset management outfit Tribeca as corporate adviser - to advise on "capital markets, project finance, offtake arrangements and strategic partnerships". (source)
This is one part of the same global firm that invested $2.7M into AUZ at a premium back in May at 2.8c/share. (source)
Now Tribeca’s capital advisory team has been appointed to help take AUZ to "US and strategic investors". (source)
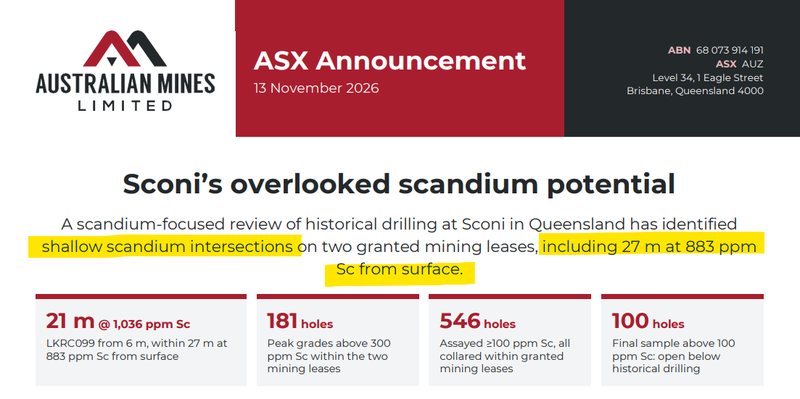
2. Just announced scandium results from its OTHER project (some of the highest grades we have seen) - up to 27m at 883ppm from surface. (source)
TODAY:
(read it here)
AUZ’s “Sconi” project was originally drilling for nickel and cobalt
(back when nobody cared about scandium)
But AUZ has now done some work re-assessing the drilling data base and it turns out there are some pretty face-melting scandium hits at Sconi.
(remember when re-assaying old gold drilling cores for lithium was a thing back in the lithium boom of 2020/2021?)
This project took AUZ to a ~$340M market cap back in 2018 (as a nickel-cobalt play) - now we have some of the highest grade scandium hits we have ever seen too. (source)
IF those hits are anything to go by - it could also be a pretty epic scandium asset too... very early days at the moment though.
It looks to us like AUZ is trying to show the market it has assets that could make it an ASX scandium vehicle.
AND it is getting global corporate advisors onboard to start marketing its project around the world (with what looks like a focus on the US).
What are they trying to achieve?
Who knows.
But it does feel eerily similar to another company where AUZ's Chairman Michael McNeilly sits on the board of - the $306M capped Cobre.
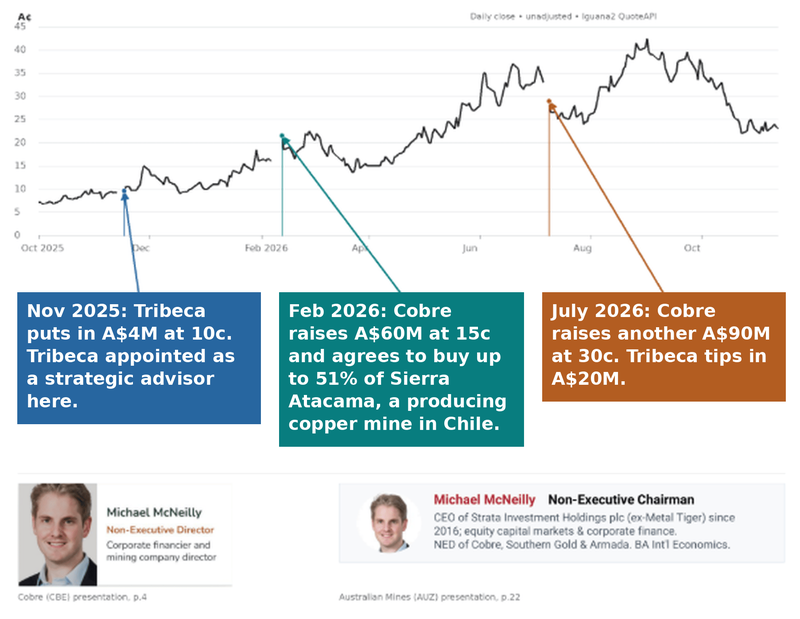
Back in November 2025, Tribeca came into Cobre for A$4M at a premium to the market price AND it was appointed strategic advisor. (source)
Cobre's share price was 9.2c at the time.
Then in February 2026, Cobre acquired 51% of a copper producing mine in Chile and raised $60M at 15c. (source)
By July Cobre had raised another $90M - this time at 30c, with Tribeca tipping in $20M in funds. (source)
At its peak, Cobre hit 43.5c, ~4.7x the 9.2c it was trading at when Tribeca came in, which took Cobre’s market cap from ~$50M to as high as $580M:
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
AUZ’s story arc has some similarities to the early stages of the Cobre story:
- In May: Tribeca came into AUZ at a premium (~14c post consolidation equivalent).
- In September: Michael McNeilly became AUZ's Chairman. (source)
- Then yesterday: Tribeca appointed as AUZ's adviser.
Hopefully they are now cooking up something big for AUZ too.
A big part of why we Invested in AUZ was because we thought the asset was very US SPAC suitable.
It was reason #8 from our AUZ Investment Memo here:
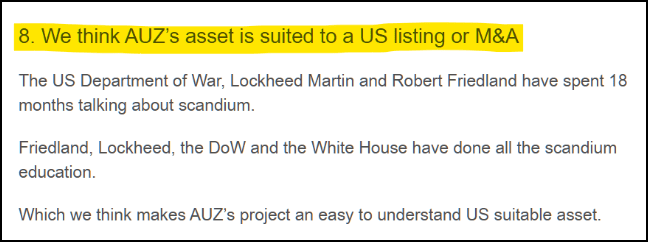
(source - our initiation article)
SPACs are listed “shell companies” on a US exchange with no assets, a big cash balance AND a ~18-24 month deadline to find and buy a real asset/project.
Structurally for a SPAC to do well, it needs to acquire an asset that its shareholders (and the broader US public) understand - otherwise everyone runs for the exits, and the share price tanks.
We think AUZ’s asset fits that criteria because it can piggyback off a lot of the marketing done by Sunrise Energy Metals (its neighbour) over in the US.
Over the last 12-18 months mining billionaire Robert Friedland (he has ~50k followers on Twitter), US president Donald Trump AND the US government have done all of the educating work with the asset next door to AUZ.
All anyone introducing AUZ’s project has to do is say “it’s next door to Sunrise - that stock that Friedland and Lockheed are in AND that Trump’s mentioned” - and then maybe show them this image:
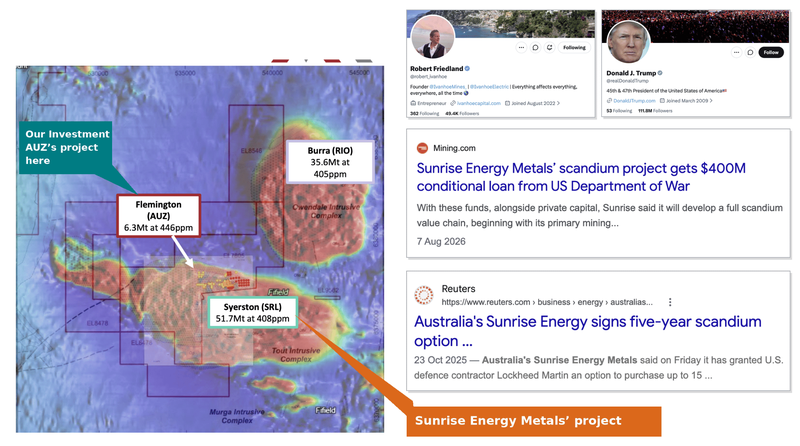
IF AUZ and the Tribeca guys are planning something US focused that would be amazing...
Fun Fact: Tribeca also have a SPAC that they cornerstoned in the US - surely, they will at least name drop AUZ’s project as one to consider to everyone else in that SPAC:
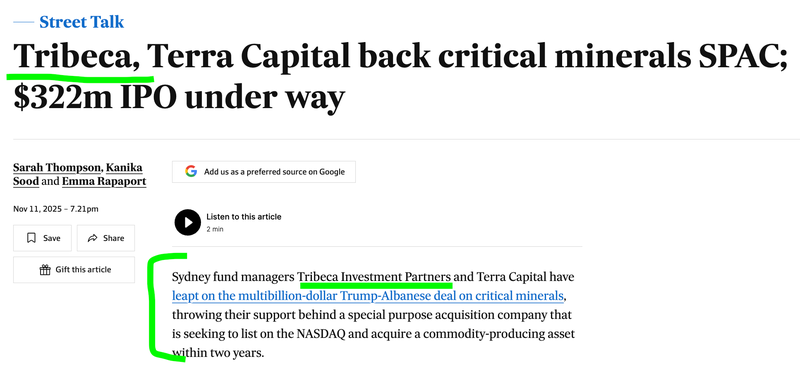
(source)
No guarantees anything happens on the SPAC front.
We did notice Tribeca’s brief also covers “project finance and offtake” - so it could be something related more directly to the project (and less corporate) too.
Especially right now with all of the attention scandium is getting in the US.
First because scandium is used in AI data centre fuel cells
New York listed ~US$60BN Bloom Energy which uses scandium to make solid-oxide fuel cells that give AI data centres on-site power without grid involvement.
Bloom says it believes it is “the world’s largest consumer of scandium oxide” (source) - and we have seen estimates that it swallows up ~74% of global demand. (source)
Bloom is the biggest buyer of scandium in the world and only a few weeks ago Bloom announced a 702MW fuel cell installation in Wyoming for Google. (source)
And a few weeks before that, Bloom did deals with Oracle for up to 1GW and up to 2.8GW - which on its own would need ~114 to 167 tonnes of scandium oxide.
For context - the entire world produced ~80 tonnes of scandium oxide last year - SO THAT one deal would take ~2 years of world consumption. (source)
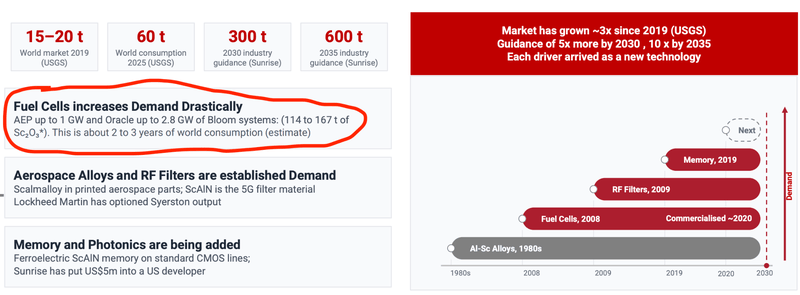
(source)
If Bloom does what it says it will, then the market could become short scandium in a big way very quickly.
And it could mean a few projects need to get developed.
Right now there are zero primary scandium projects in production in the world and ~90% of supply comes out of China. (source)
Second because of all of the interest from the US defence sector
This is the big unknown for the scandium market.
What sort of demand profile comes from scandium use in the defence sector, no one in the industry knows right now.
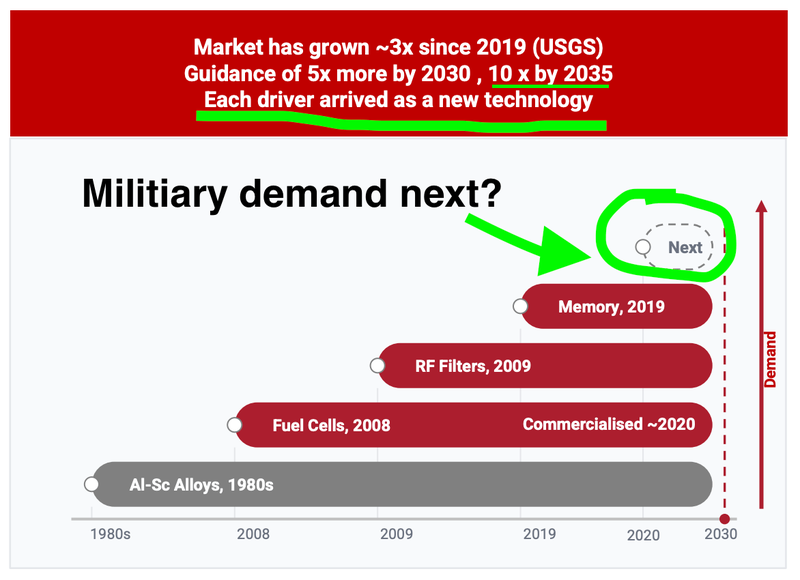
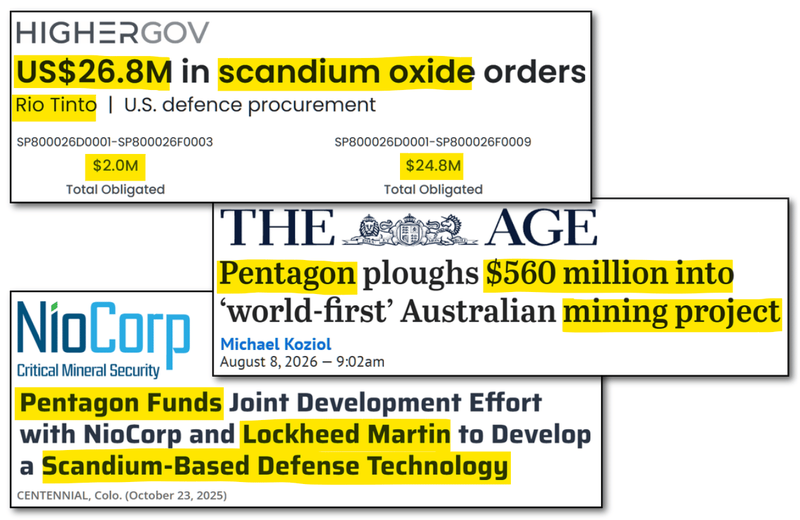
What we do know is that the US Department of War has now put money behind scandium at three different parts of the supply chain:
- The stockpile - US$26.8M of scandium oxide orders placed with Rio Tinto for the National Defense Stockpile. (source)(source)
- The mine - the conditional US$400M loan commitment to AUZ's neighbour Sunrise. (source)
- The fighter jet parts - US$10M toward a scandium-aluminium alloy program with Lockheed Martin. (source)
(source) (source) (source) (source)
And Lockheed Martin - the world’s largest defence contractor who builds F-35 fighter jets and PAC-3 missiles - looking to lock up supply from two scandium mines:
- October 2025 - Sunrise Energy Metals (AUZ’s neighbour): an option over the first 15 tonnes a year of scandium oxide for five years. (source)
- August 2026 - NioCorp in Nebraska: a non-binding MOU to buy up to 15 tonnes a year for ten years, as oxide or as finished scandium-aluminium alloy. (source)
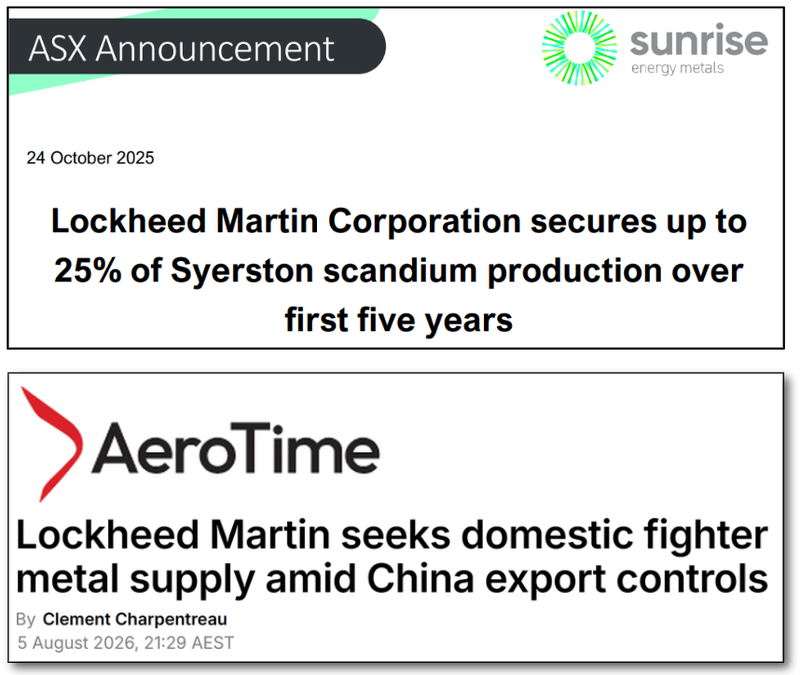
We think Lockheed AND the US government wouldn’t be lining up this much supply if it didn’t have an intended use case for it.
And post that NioCorp deal - it’s starting to look like it may be into the fighter jet supply chain...
Part of Lockheed Martin’s “Skunk Works joint development program” (source) being partially funded by that US$10M Department of War grant we mentioned earlier. (source)
WHICH is going to prototype scandium-aluminium alloy components “that will expand the capabilities of modern fighter aircraft.”
Skunk Works is the Lockheed division that built the U-2, the SR-71 Blackbird and the F-117 stealth fighter - i.e. the “secret-projects” shop.
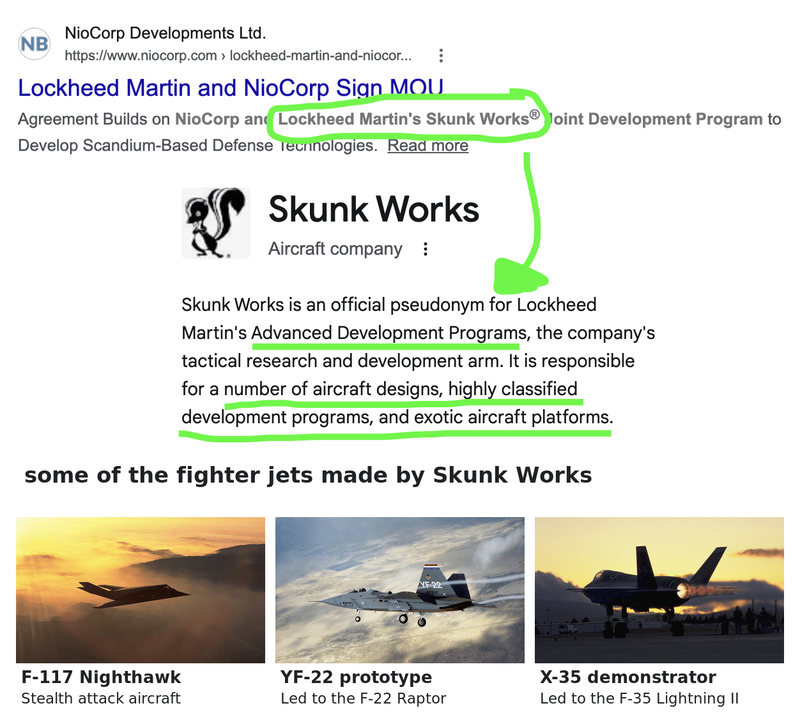
It looks like Lockheed is cooking something big up in the military space too (akin to what the Soviets did with their military in the 70’s and 80’s)
Fun Fact - during the 1980s, Soviet metallurgists started using aluminium-scandium alloys in fighter jets like the MiG-21 and MiG-29, keeping the application classified for years.
(making the Soviet planes lighter, more fuel efficient, longer range and with higher payload capacity)
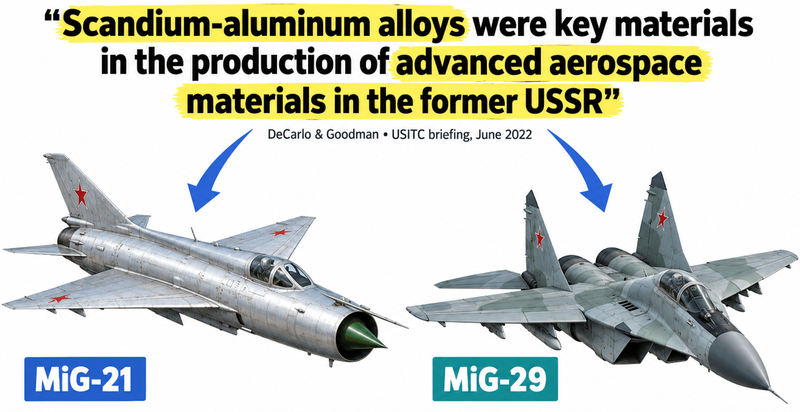
According to the US International Trade Commission, the scandium-aluminium alloys were key parts of the Soviet “advanced aerospace materials” advantage AND are “still used in Russian MiG aircrafts today”.
(source)
Up until now, the West hadn’t really had enough control of its supply chains to go hard on developing military tech using scandium.
IF the Bloom growth story plays out AND/OR Lockheed/the US Department of War achieves whatever it is aiming to achieve with its scandium deals we think scandium demand could surge.
And maybe force a few mines to get built...
Lockheed is the first to move from the defence contractors - we think more could follow
So Lockheed has done deals with two companies - Sunrise and NioCorp (one in Australia and one in the USA).
As far as we can find, no other big defence contractor has done a scandium deal yet.
We think that IF any of the other big defence guys start looking for supply - AUZ’s project could be one they (at the very least) watchlist.
Hopefully the Tribeca corporate team show off the project to a few of those guys too...
Especially with AUZ’s project being in a part of the world these guys now know and understand (thank you Lockheed and Donald Trump):
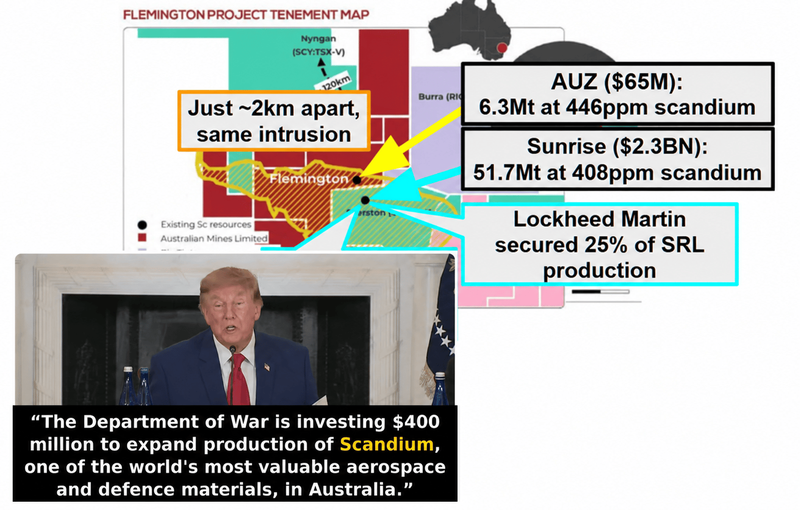
(no guarantees of course - AUZ has no offtake, no MOU and no government funding right now)
Ultimately, we are Invested in AUZ for it to achieve our Big Bet as follows:
Our AUZ Big Bet:
"AUZ re-rates to a $500M+ market cap by advancing its scandium project toward a development decision and/or becomes the subject of a corporate transaction (takeover, JV, or US-listing event) at multiples of our Initial Entry Price."
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our AUZ Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
AUZ owns one of the highest grade scandium deposits in the world
AUZ’s project is one of only three pure-play scandium deposits on the planet with grades above 300ppm.
Of those three, AUZ’s is the highest grade - the other two projects are owned by $245BN Rio Tinto and $2.2BN Sunrise Energy Metals.
AUZ’s current market cap is only $76M.
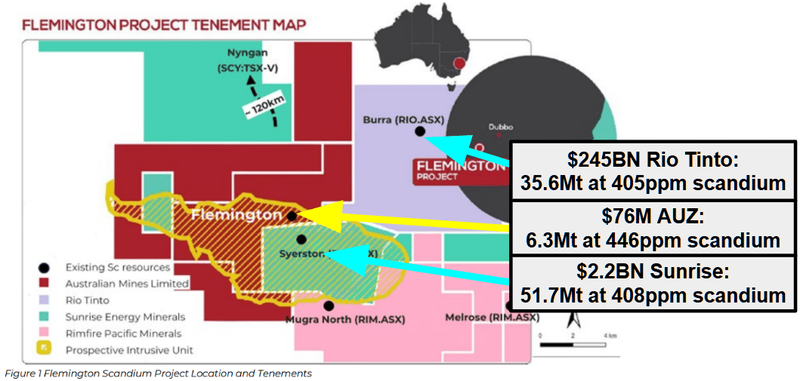
(source)
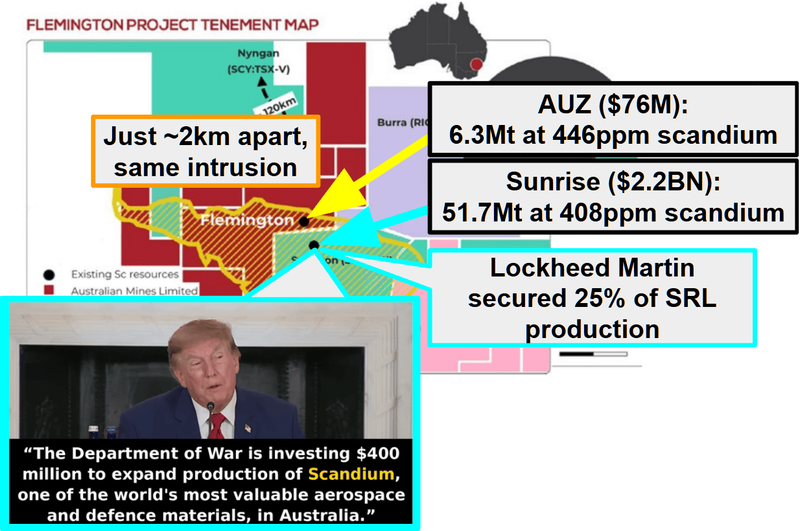
Sunrise’s project next door to AUZ has received:
- A US$400M conditional loan commitment from the US Department of War. (source)
- An offtake option deal from defence contractor Lockheed Martin. (source) and
- A shoutout from the US President himself, Donald Trump, at a mining roundtable in the US in August. (source)
AUZ’s project sits directly on the same geological intrusion that hosts Sunrise’s project:
(source)(source)(source)(source)
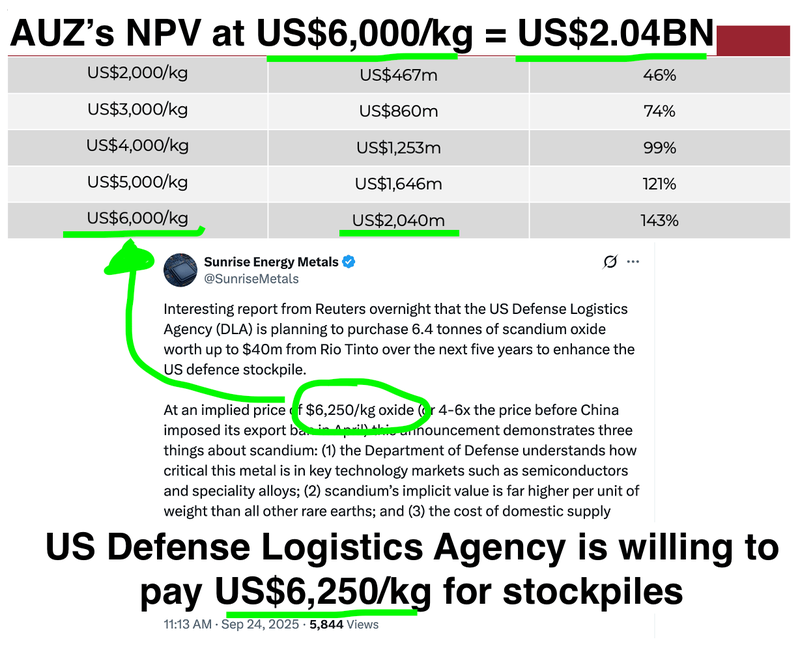
AUZ’s project also has a scoping study showing a US$860M NPV from US$125M of CAPEX at a US$3,000/kg scandium price.
If we use a scandium price of US$6,000/kg, the NPV rises to US$2.04BN.
That price is not unreasonable.
The US Defense Logistics Agency’s planned scandium stockpile purchase from Rio Tinto has an implied ceiling of ~US$6,250/kg. (source)
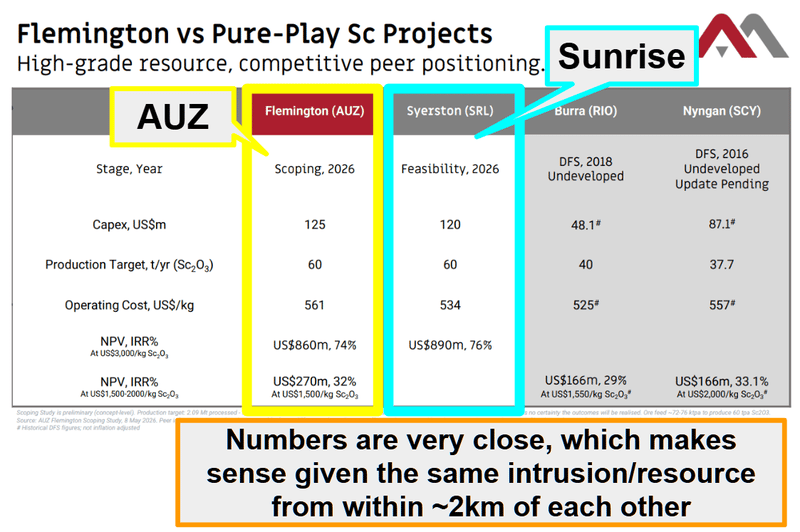
AUZ’s project also has the same planned output as Sunrise’s - ~60 tonnes a year of scandium oxide - from three shallow pits instead of Sunrise’s planned 13.
Right now, Sunrise is capped at ~$2.2BN.
AUZ is capped at ~$76M.
Here is a current side by side comparison of Sunrise and AUZ’s assets:
(source)
We are Invested in AUZ to see it progress its asset - closer to the position Sunrise’s asset is in AND hopefully along the way bridge that valuation gap to Sunrise.
(currently that is a ~29x multiple gap).
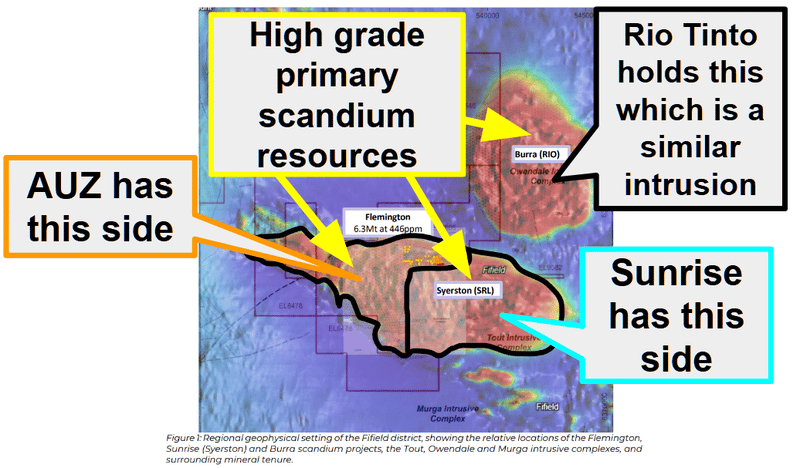
Remember AUZ’s asset literally sits on the same geological intrusion as $2.2BN Sunrise’s:
(source)
Naturally it would make a lot of sense if the two companies came together.
BUT we are Invested in AUZ to see it bridge its gap by progressing its own asset.
Currently the main differences between Sunrise and AUZ from an asset perspective are:
- Study stage - Sunrise has a Definitive Feasibility Study, an Ore Reserve and a Final Investment Decision.
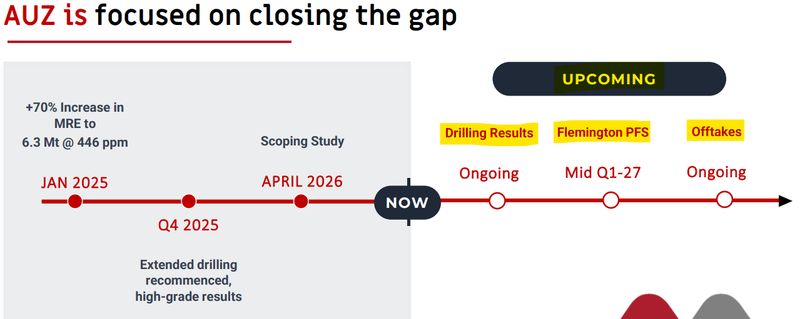
🚨 AUZ has a Scoping Study, with a Pre-Feasibility Study due in mid-Q1 2027. (source)
- Offtake and funding - Sunrise has a conditional US$400M loan commitment from the US government AND an offtake option with defence contractor Lockheed Martin.
🚨 AUZ has offtake discussions “ongoing” and no government funding/support (YET).
- Corporate - Sunrise is re-domiciling to the US and going for a primary NASDAQ listing.
🚨 AUZ is ASX listed for now and is only also listed on the OTCQB (no mainboard US listing YET).
- Size versus grade. Sunrise’s resource is ~8x the tonnage.
🚨 AUZ’s is the higher grade (446ppm vs 408ppm) with a simpler three-pit mine plan versus Sunrise’s 13 planned pits.
- ✅ Scale - Both are planning production of scandium at ~60 tonnes a year - but AUZ’s PFS is also assessing 120 and 180 tonne a year cases. (source)
In September AUZ appointed a specialist PFS team - with the PFS due in mid next quarter (Q1 2027).
Drilling is also “scheduled to commence following receipt of the required exploration activity approval” from the regulator. (source)
We think the PFS will be a big step toward AUZ hopefully closing that valuation gap with Sunrise - especially for anyone looking at which project to support - where being advanced matters.
(source)
Australian Mines
What we want to see next from AUZ
🔄 Pre-Feasibility Study for scandium project
We think this could be the next major catalyst for AUZ.
Here are the milestones we are tracking:
✅ PFS formally commenced and fast-tracked (May 2026)
✅ Specialist PFS consultant team appointed (September 2026)
🔄 Metallurgy, geotech, tailings, environment and water studies
🔄 Assessment of the 120tpa and 180tpa scale-up cases
🔲 PFS completed (mid-Q1 2027)
🔲 Drilling to grow its scandium resource
We want to see AUZ drill out and grow its scandium resources - so that the market can start to make stronger comparisons between AUZ and Sunrise’s asset.
Here are the milestones we are tracking:
🔄 Drilling approvals (lodged - drilling to start once received)
🔲 Drilling commences (~50 holes / ~1,250m)
🔲 Drilling results
🔲 Corporate/commercial progress for scandium asset
We also want to see AUZ execute the Sunrise playbook and land some (or all) of the following:
🔄 Offtake / strategic partner discussions
🔲 First offtake, MOU or government-linked funding
🔲 Get interest from US investors OR get listed in the US
🔲 Name change to First Scandium approved (AGM, 24 November)
What could go wrong
The single biggest risk right now is still “Single-customer demand risk”.
The scandium demand story leans heavily on ONE company - Bloom Energy.
Bloom’s share price fell after it released its results last month and a shareholder class action is currently in place (Bloom says it is without merit). (source)
If Bloom’s ramp slows, or if the market stops believing it, scandium stocks would be sold off with it - regardless of what AUZ does.
Source: “What could go wrong” - AUZ Investment Memo 12-Aug-2026
Other risks
Like any early-stage critical minerals development company, AUZ carries significant risk, here we aim to identify a few more risks.
Although Tribeca's appointment gives AUZ access to capital markets and strategic investors, an adviser appointment is not a transaction. There is no guarantee it leads to funding, an offtake, a partner or a US listing, and any capital raised could dilute existing shareholders.
While we point to what happened at Cobre after Tribeca came in, Cobre's re-rate came from a producing copper deal and two large raises. AUZ is a different company with a different asset, and there is no guarantee its share price follows a similar path.
Given AUZ's share price has run from ~10c to ~18c in under three weeks on (almost) no news, the price could pull back sharply if volumes fade or the next catalyst takes longer than the market expects.
AUZ had ~$4.6M in cash at 30 September, which it estimates covers ~2.5 quarters of spending. With the PFS, Flemington drilling and now possible Sconi work all needing funding, a capital raise is likely and could dilute existing shareholders.
While the PFS is targeted for mid Q1 2027, study timelines often slip, and a PFS showing higher costs or weaker economics than the scoping study could widen the valuation gap to Sunrise rather than close it.
The Flemington drilling program is still waiting on NSW regulatory approval. Delays in that approval, or drilling that fails to extend the resource, would push out the timeline for stronger comparisons to Sunrise.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our AUZ Investment Memo
Our Investment Memo provides a short, high-level summary of our reasons for Investing.
We use this memo to track the progress of all our Investments over time.
Our AUZ Investment Memo covers:
- What does AUZ do?
- The macro theme for AUZ
- Our AUZ Big Bet
- What we want to see AUZ achieve
- Why we are Invested in AUZ
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.