AUZ: USA critical minerals on the menu as Trump and Xi meet in the USA
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 14,730,000 AUZ Shares at the time of publishing this article. The Company has been engaged by AUZ to share our commentary on the progress of our Investment in AUZ over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
The long awaited one day meeting between Chinese President Xi Jinping and US President Donald Trump wrapped up a few hours ago.
The “trade war truce” has been extended by two months...
Chinese President Xi announced that he is gifting two giant pandas to the USA for a zoo in Atlanta (their names are Ping Ping and Fu Shuang).
...but not any heavy rare earths, tungsten, antimony or scandium.
We’ve been watching the conveniently timed “critical minerals” news releases out of the USA during the Trump-Xi meeting.
(of course a few juicy announcements were going to come out in the day before the meeting to help set the tone):
- ~34 hours ago - Glencore landed a US$500M EXIM financing to help build the US critical minerals stockpile (source)
- ~48 hours ago - US committed up to US$7BN in loans for Argentine energy, mining and infrastructure projects (source)
- ~3 days ago - Italy and the US signed a critical minerals MOU, with a working group on recycling and recovery (source)
- ~2 days ago - A US-Denmark-Greenland security deal was signed to tighten the screening of non-NATO/EU investments (source)
Great time to be an established critical minerals project - the attention and capital is flowing in.
And the now slightly extended USA-China “trade war truce” ends in 108 days...
(instead of the originally planned 47 days)
We all know how long it takes to build a mine. And if you don’t - it takes many, many years.
There is not much that can be done in 108 days aside from the USA continuing to throw more capital, attention, incentives and announcements at the critical mineral supply problem.
(which is great for critical minerals stocks)
In the last 2 weeks we have seen more investment into US sourced and produced tungsten.
Last week there was US$150M funding to restart a mine as a part of a US$2BN funding arrangement involving $850M Elmet.
A couple of days ago Elmet also signed a US$1.8BN offtake deal for the Hemerdon mine in the UK. (source)
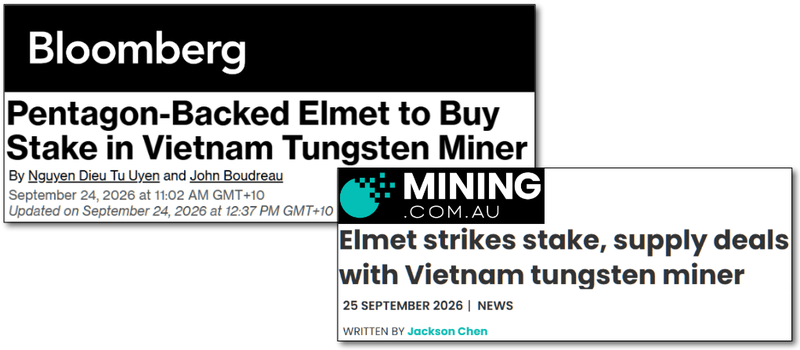
Plus ANOTHER new one in the past 24 hours (a 4.99% interest in MSR for US$124.75M, a valuation of near US$2.5BN):
And ~7 weeks ago $450M into a scandium company in NSW called Sunrise Energy Metals, now capped at $3.9BN.
Our scandium Investment is the $70M capped Australian Mines (ASX:AUZ), owner of one of the highest grade scandium projects in the world...
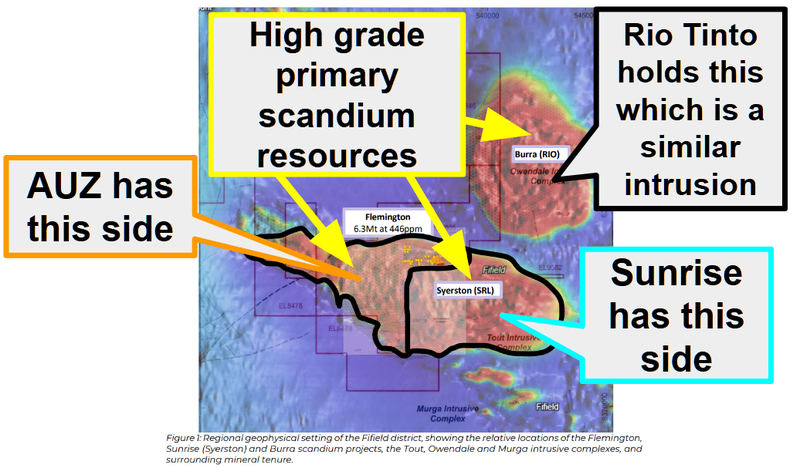
... sitting on the same geological intrusion as its direct neighbour, that same $3.9BN Sunrise Energy Metals.
Literally the same geophysical structure:
(source)
Sunrise has become what it is today because its backed by mining billionaire Robert Friedland AND Trump said this about the project:
"The Department of War is investing $400 million to expand production of scandium, one of the world's most valuable aerospace and defence materials, in Australia."
BUT... AUZ’s project has a higher grade.
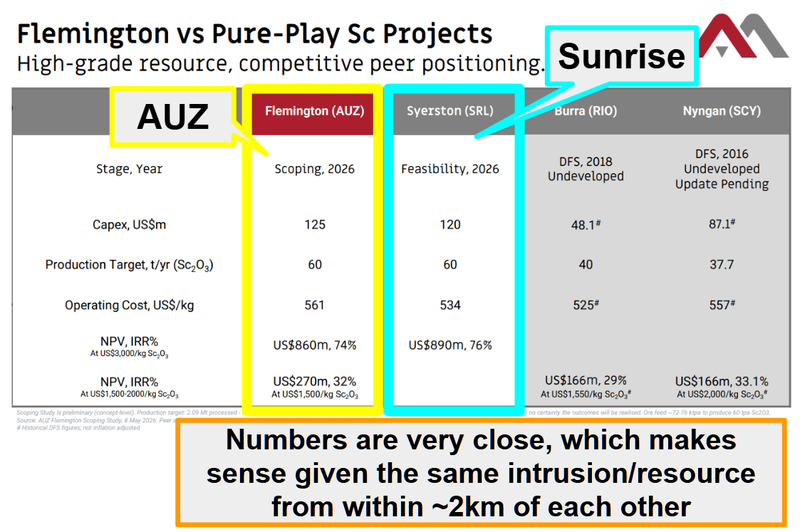
AND the same targeted production run rate relative to Sunrise, yet its market cap is ~56x less.
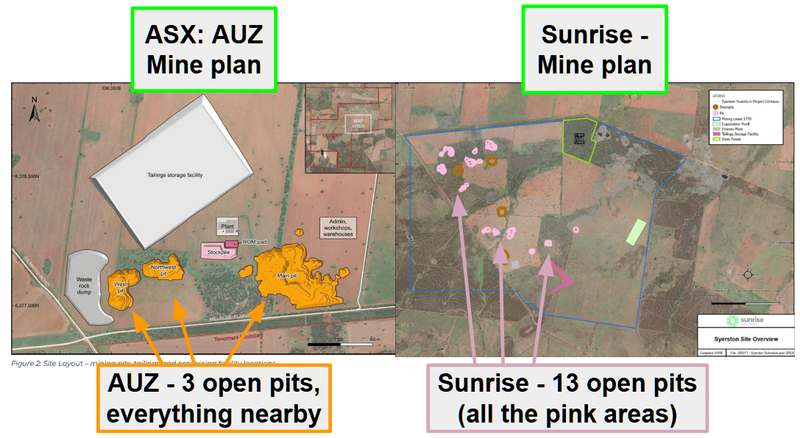
AUZ is capped at $70M, Sunrise at $3.9BN and here is a side by side of the two assets:
(source)
Aside from the large valuation gap, the main difference between Sunrise and AUZ right now is that they are at different stages.
Sunrise is a lot closer to being development ready... BUT we think that could change very quickly.
AUZ just appointed PFS “specialist consultants” and now expects to have an integrated PFS completed in the middle of Q1 of 2027. (source)
AUZ also expects to be drilling soon once an approval is received - so we could see the resource grow too.
Technically, by mid Q1 of 2027 we could see AUZ in a position where it has a project with higher grade AND at the same development study stage as its neighbour, the $3.9BN Sunrise Energy Metals.
Whose project has been able to attract:
- The US Department of War - giving a US$400M conditional loan to,
- Major US defence contractor Lockheed Martin - signed an offtake option with,
- Chaired and majority owned by mining billionaire Robert Friedland.
Remember Sunrise sits on the same geological structure as our Investment AUZ’s asset next door.
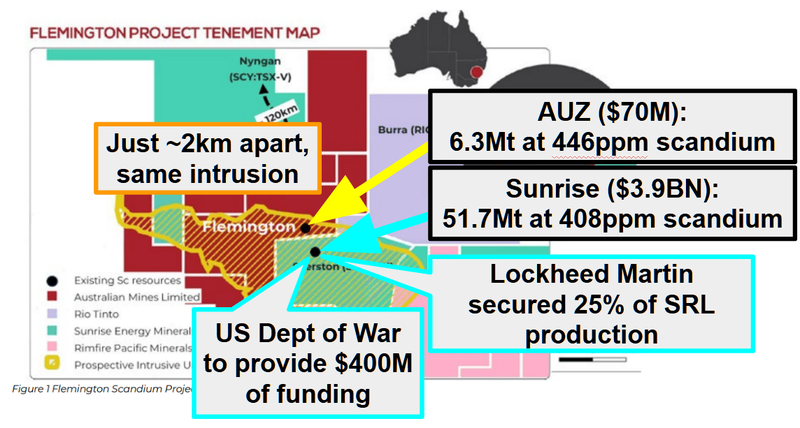
(source)(source)(source)(source)
At the same time, AUZ could also have produced a PFS which COULD end up 3x’ing the scandium output of its project when developed. (source)
Is AUZ preparing its assets for future scandium demand from advanced technologies?
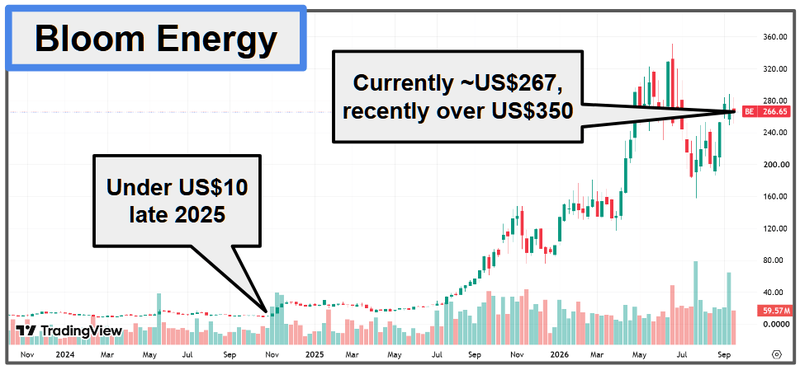
Or maybe just responding to the growth of the biggest scandium consumer in the world, the $112BN Bloom Energy?
Bloom buys ~74% of the world’s scandium and is now capped at $112BN - its share price is up ~44% in the last ~10 weeks.
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
So what even is scandium and who are NYSE listed Bloom Energy?
Scandium is one of the world’s most valuable aerospace, defence materials and it helps power AI data centres.
And surprise surprise... China controls ~80% of scandium mining and ~100% of processing. (source)
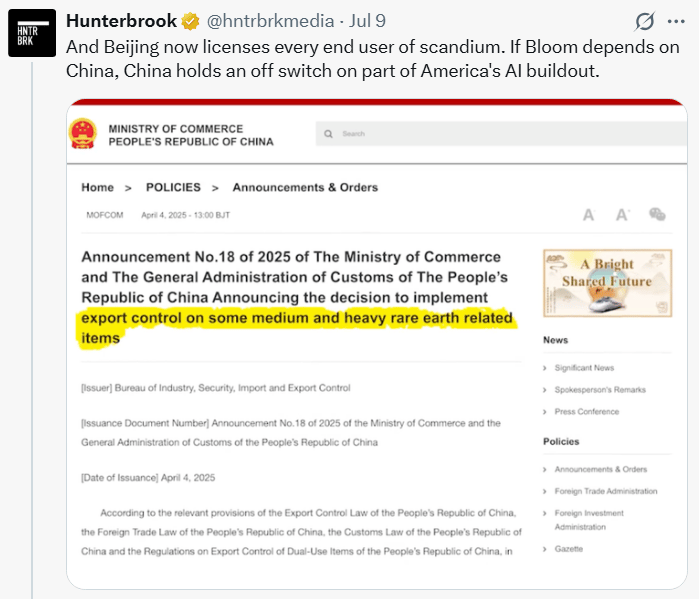
China has had export controls in place on every form of scandium since April 2025. (source)
One company called Bloom Energy already consumes ~74% of the world's scandium supply making fuel cells for AI data centres.
Scandium is a core material in fuel cell tech developed by US$112BN NYSE listed Bloom Energy - used to power AI data centres.
Bloom Energy has recently and rapidly become the largest consumer of scandium on the planet - for powering AI data centres.
Bloom Energy makes mini, modular, power plants that sit on-site, which give big buildings like AI data centres non-stop electricity without burning fuel.
Investors have driven Bloom to a US$112BN market cap in the hopes Bloom Energy’s solid-oxide fuel cells can solve the severe electricity bottleneck facing AI data centres.
Bloom recently became a darling of the AI stock boom because its fuel cells might provide data centres with “behind-the-meter” power.
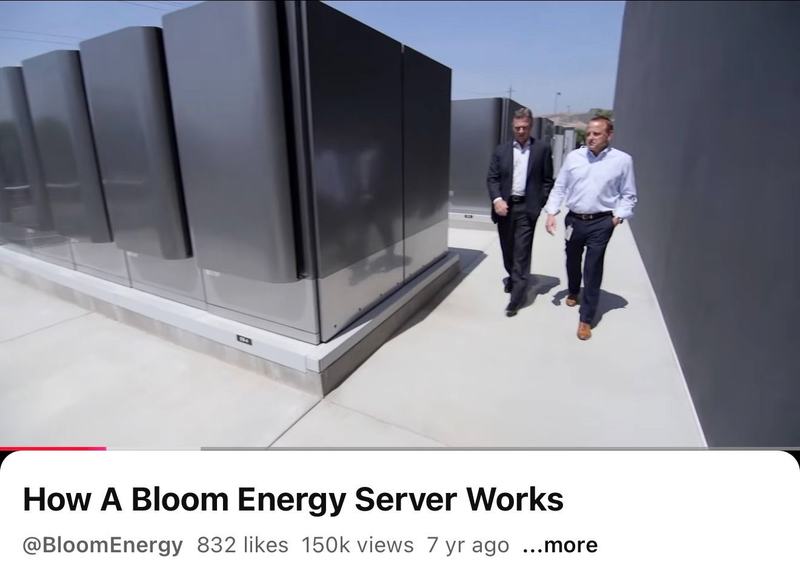
Check out how their technology works in this explainer video here:
(source)
Bloom counts Amazon Web Services and Oracle as clients.
Here’s where scandium comes in:
Each Bloom fuel cell is made up of ~10% scandium oxide (locked by Bloom’s patents). (source)
Each gigawatt of Bloom fuel cells needs ~25-60 tonnes of scandium. (source)
The entire global production capacity was ~80 tonnes of scandium last year. (source)
At the moment, Bloom consumes ~74% of the world's scandium - making fuel cells that power AI data centres (servicing customers like Amazon and Oracle).
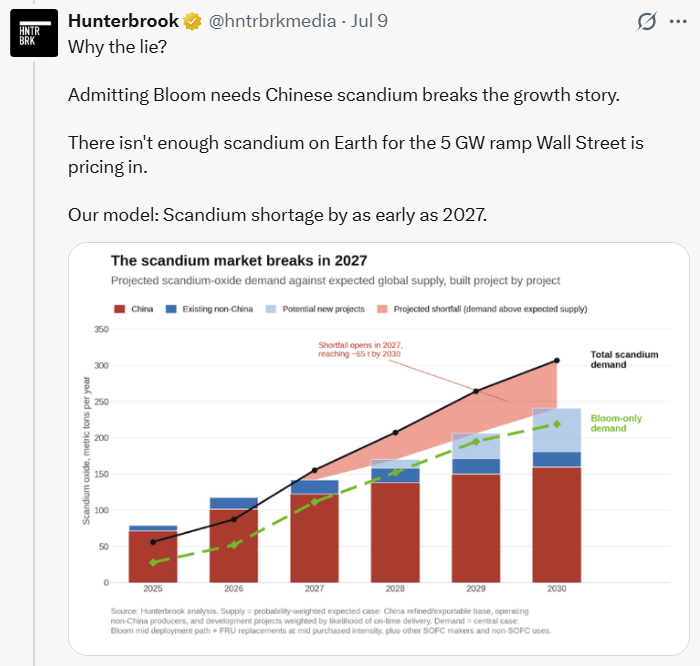
If it hits analyst forecasts of “5GW-by-2030” target, alone it would need ~220tpa of scandium - nearly 3x the ~80 tonnes of scandium per year the entire planet produces today. (source)
(just one company doing one thing... this doesn't include what Lockheed Martin is up to and all the other scandium applications)
If we think Bloom’s growth is going to happen - then being Invested in a scandium project like AUZ makes a lot of sense to us.
If you look at Bloom sceptics - owning scandium makes a lot of sense too.
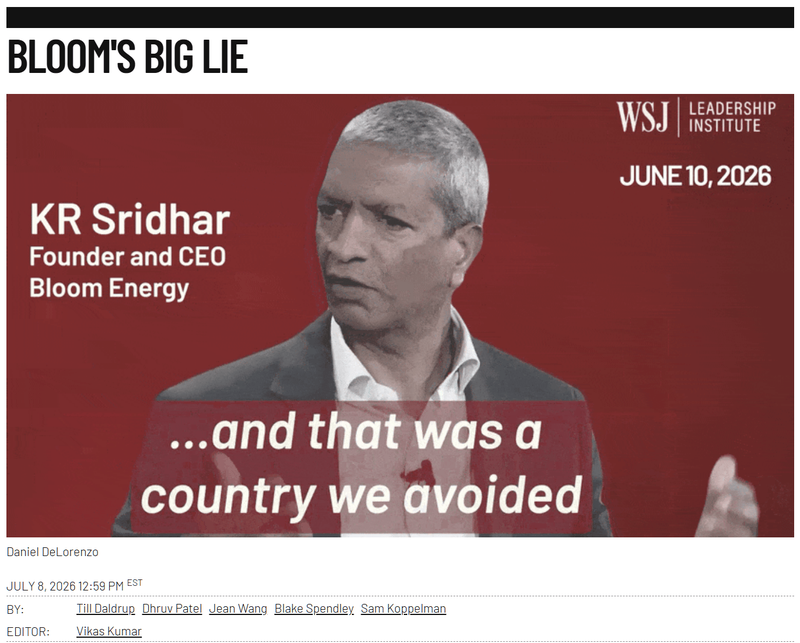
A few months back, Bloom was the subject of a short report from a US group, Hunterbrook.
The short report is called "Bloom's Big Lie". (source)
(source)
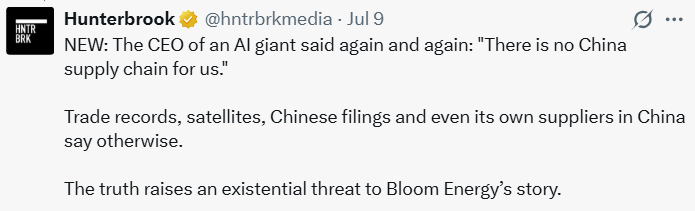
The main argument from the shorts is the claim Bloom’s scandium supply chain is heavily reliant on China.
(source)
AND that at any time China can switch off supply and kill Bloom’s supply of scandium, kicking USA AI efforts right in the nuts:
(source)
AND that there won't be enough scandium to fuel Bloom’s claimed growth forecasts:
(source)
Bloom's stock dropped ~12% off the back of that report.
Bloom’s response to all of this was that they have "sufficient scandium oxide to meet our current fuel cell demand and backlog" and that its supply is "not dependent on China".
It also said that it has "clear visibility into our supply chain to support production of 25GW of fuel cells per year."
We are generally pretty optimistic but even by our standards, that is a big call.
25GW of Bloom Fuel Cells would mean ~600 tonnes to ~1,500 tonnes of scandium demand a year.
Compared to the current market of ~80 tonnes per annum.
Which means someone, somewhere, is going to have to bring on new mine supply (outside of China).
And again, this is for just one company, doing one thing with scandium.
All of this is before any military demand.
Scandium is also a critical input into aerospace, defence and automotive sectors.
The problem is, the West has no secure supply chain, so it can't experiment on those “potential applications”.
The way we see it, fuel cell tech demand alone justifies bringing new mines online.
The “defence applications” are the big blue sky upside to demand.
IF scandium can help power data centres at lower temperatures and more efficiently we can think of a lot of military applications for that type of mineral...
(drones, AI robots... you get where we are going.)
No wonder Lockheed Martin and the Department of War are circling AUZ’s neighbour multi-billion dollar neighbour... what do they know that we DON’T know about how much scandium they will need?
(Remember from above - Lockheed did a scandium offtake deal with AUZ’s neighbour for up to 25% of production for the first five years)
IF the US can build a reliable Western scandium supply chain, then who knows what gets built around that source of supply.
Anyway... after reading that short report, it's hard to not be bullish on scandium project owners which win in either of the two scenarios:
- Bloom is right - It ramps up to 5GW+ by 2030, meaning Bloom ALONE would need ~220 tonnes of scandium a year - nearly 3x current global production.
- The shorts are right - Bloom doesn’t have the scandium supply it needs and will need to use its US$112BN market cap to find (or incentivise) a supply response.
Or, of course option 3) Bloom calls it quits and abandons its growth plans, risking cratering US$112BN in market cap.
You would think Bloom would rather just use 1% of its market cap and underwrite a mine instead of calling it quits.
We have no idea what Bloom (or the DoW/US government) will do next.
BUT we are pretty comfortable holding onto AUZ for a few years to see how this one plays out.
Especially right next door to the scandium project that the USA has handpicked to bring into production asap.
The two ways we think this can play out for AUZ
First - there is the obvious argument that AUZ and Sunrise come together and go to the US as a combined entity.
(The two projects sit on the same intrusion so it would make sense)
Here is a clip of billionaire Friedland talking about how Sunrise will eventually have to list in the US - Australian Scandium Miner Secures $400 Million US Investment
A logical endgame for the district could be one integrated scandium hub with Sunrise as the handpicked vehicle as the "US (and western) national champion".
BUT we are NOT Invested in AUZ just hoping for a takeover.
Second - We are Invested in AUZ because we want to see AUZ progress its asset and close the current ~56x gap to its neighbour Sunrise.
Sunrise is capped at ~$3.9BN
AUZ is capped at ~$70M.
We think Sunrise’s assets are great but the valuation gap currently looks extreme to us.
BUT there is no disputing AUZ’s project is one of the highest grade scandium resources in the world.
(higher grades typically mean lower costs to produce when it comes to mining)
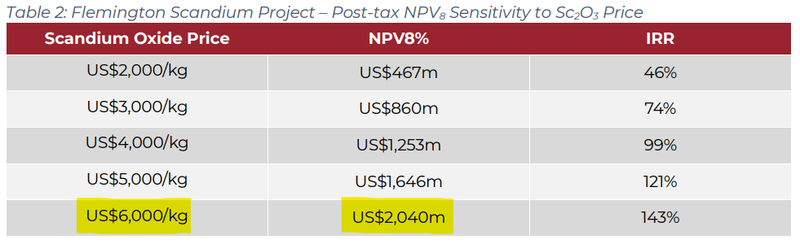
It's also very advanced with a scoping study showing a Net Present Value (NPV) of US$860M based on a 28 year mine life.
(That NPV number is based on a US$3,000/kg scandium price. The US DLA is buying scandium for its strategic stockpiles at a much higher price of ~US$6,250 per kilo) (source)(source)
At US$6,000 per kg, AUZ’s project NPV is ~US$2.04BN.
(source)
Another kicker for AUZ is its scoping study is based around mining ONE big open-pit and two pits alongside it, as opposed to the 13 separate pits Sunrise has in its feasibility study.
(we are not mining experts, but building fewer pits that are higher grade sounds a lot simpler than having 13 different pits being mined at once)
Of the three big projects in this part of NSW, it is the smallest in terms of tonnage BUT the highest grade (versus Rio and Sunrise’s assets).
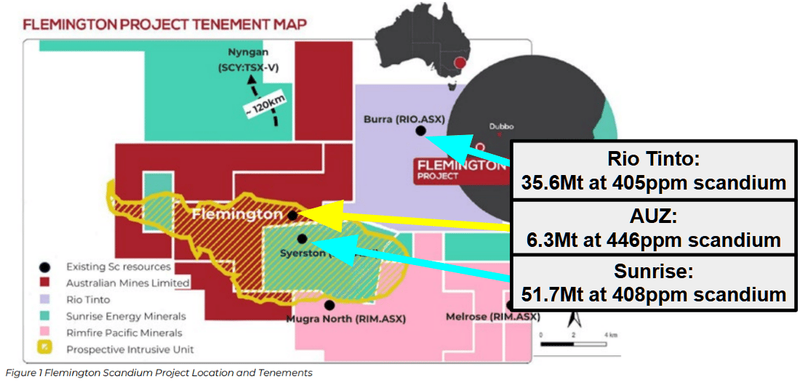
(source)
Fortunately, for AUZ, scandium is one of those commodities where size doesn’t really matter because right now the market is relatively small.
The entire world produced ~80 tonnes of scandium oxide last year. (source)
When the market is that small, you don't need a monster deposit AND grade probably matters a lot more.
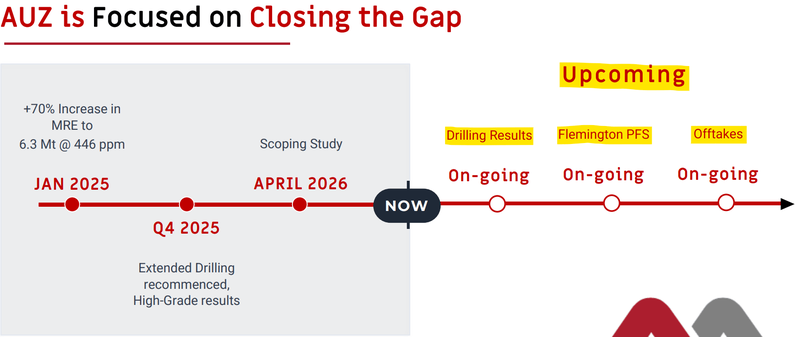
We are Invested to watch AUZ get re-rated on its own catalysts independent of what its multi billion dollar neighbour is up to:
- Drilling results hopefully extend its resource (strengthening the comparisons to Sunrise's asset).
- Complete a Pre-Feasibility Study (PFS) - due in ~5 to 8 months, and
- Offtake and strategic partner discussions result in firm commitments.
(source)
We want to see AUZ execute something similar to Sunrise’s playbook.
A deal with a major scandium consumer, a big defence contractor or a corporate/government funding deal.
Sunrise is capped at ~$3.9BN
AUZ is capped at ~$70M.
That's a ~56x gap between two projects that we think aren’t that far apart from one another.
We Invested in AUZ ~6 weeks ago - in that launch note we detail:
- Why we think US critical minerals are about to have their “2020-2022 lithium” moment.
- What does AUZ do?
- What is the macro theme?
- Our AUZ Big Bet
- The 9 reasons we are Invested in AUZ
- What we want to see AUZ achieve next
- What could go wrong?
Check out the full note here: Our Latest Investment is Australian Mines Ltd (ASX: AUZ)
Here are the reasons why we Invested in AUZ
These reasons were published on the 12th of August 2026 in our initiation note linked above - we have included updates below where necessary.
- AUZ owns one of the highest grade scandium resources in the Western world - 446ppm, versus Sunrise at 408ppm and Rio Tinto's nearby deposit at 405ppm.
- Neighbour Sunrise has a Lockheed Martin offtake option, a US$400M loan commitment from the US Department of War, and is now planning a US listing.
- The valuation gap is ~40x - Sunrise is capped at ~$3BN, AUZ at our Initial Entry Price was capped at $58M.
UPDATE: (AUZ is now capped at $70M, Sunrise at $3.9BN)
- AUZ has a similar mine plan to neighbour Sunrise - both projects sit on the same geological structure AND have the same planned ~60tpa output (AUZ's asset is smaller in tonnage, but higher grade, with a simpler 3-pit mine plan versus Sunrise's 13).
- AUZ's 2026 scoping study showed a Net Present Value (NPV) of US$860M based on a US$3,000 per kg scandium price - The US Defense Logistics Agency is paying US$6,250 per kg for its stockpiles - at US$6,000 per kg AUZ’s NPV is US$2.04BN
- China controls the market (for now) - ~80% of global scandium mining, ~100% of processing, and export controls on every form of scandium since April 2025.
- AI data centres are the demand kicker - ~74% of global scandium demand comes from ONE company, Bloom Energy, which makes the fuel cells powering AI data centres.
- Scandium is also a military metal - a small amount makes aluminium stronger and lighter, essential for fighter jets, missiles, hypersonics and 3D printed aerospace parts.
- We think AUZ's asset could end up in the US - via takeover, JV or a US listing event.
- AUZ’s run to a ~$235M market cap on another one of its assets during the 2017-18 battery metals boom - it still owns 100% of that project.
- Plus we also like its gold project in Brazil - an earn-in to 80% of a gold project with a ~336koz historic estimate and monster historic hits (104.5m @ 1.59g/t).
Ultimately, we are hoping the reasons above contribute to AUZ delivering our Big Bet as follows:
Our AUZ Big Bet:
"AUZ re-rates to a $500M+ market cap by advancing its scandium project toward a development decision and/or becomes the subject of a corporate transaction (takeover, JV, or US-listing event) at multiples of our Initial Entry Price."
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk and commodity price risk - just some of which we list in our AUZ Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What else do we want to see AUZ deliver?
Drilling to grow the scandium resource
We want to see AUZ drill out and grow its scandium resources - so that the market can start to make stronger comparisons between AUZ and Sunrise’s asset.
Here are the milestones we are tracking:
🔄 Drilling approvals (recently lodged, drilling to begin once approved)
🔲 Drilling commences
🔲 Drilling results
Progress the scandium project through to development
We want to see AUZ progress its scandium project through to being development ready.
The next major catalyst being a Pre Feasibility Study (PFS)
Here are the milestones we are tracking:
✅ PFS formally commenced and fast-tracked (May 2026)
🔄 Mine optimisation, metallurgical testwork, infrastructure
🔄 Assessment of 180tpa scale-up case
🔲 PFS completed (~Q1/Q2 2027)
Commercial progress for scandium asset
We also want to see AUZ execute the Sunrise playbook and convert:
🔄 Offtake / strategic partner discussions
🔲 First offtake, MOU or government-linked funding
Corporate - progress toward a US facing listing
This one is all about building up the company to get listed on a major US stock exchange OR become a takeover target for one of the big US listed critical minerals players (OR SPAC’s).
This one is out of AUZ’s control to some extent but we would like to see some progress toward a listing.
What could go wrong?
In the short-medium term the key risk for AUZ will be “Single-customer demand risk” and “Market risk”.
There is no guarantee that the demand projections from Bloom Energy play out the way the market expects.
IF the Bloom Energy demand story was to fall away, scandium stocks more broadly would be sold-off.
Single-customer demand risk:
Single-customer demand risk
The scandium demand story currently leans heavily on ONE company - Bloom Energy.
If Bloom's ramp up slows OR if it engineers scandium intensity down (its own patents describe "thrifting"), the urgency behind Western scandium supply could deflate.
Source: “What could go wrong” - AUZ Investment Memo 12-Aug-2026
Other risks
Like any early-stage exploration company, AUZ carries significant risk, here we aim to identify a few more risks.
While AUZ aims to expand its resource base with its next round of drilling - there is no guarantee the drill program delivers any economic mineralisation.
Fast-tracking the Pre-Feasibility Study and funding ongoing exploration requires substantial ongoing expenditure. The company will likely need further capital raises to fund development, which risks diluting existing shareholders.
Much of our AUZ bull case hinges on the company securing government-backed funding, a major defence offtake deal, or a corporate transaction. There is no guarantee these discussions will lead to binding agreements, which could leave AUZ struggling to fund development independently.
Extracting and refining scandium from laterite deposits is technically complex and requires significant upfront infrastructure capital compared to the current market cap.
Furthermore, upcoming drilling and future mine development remain subject to environmental approvals and potential regulatory delays in New South Wales.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our AUZ Investment Memo
Our Investment Memo provides a short, high-level summary of our reasons for Investing.
We use this memo to track the progress of all our Investments over time.
Our AUZ Investment Memo covers:
- What does AUZ do?
- The macro theme for AUZ
- Our AUZ Big Bet
- What we want to see AUZ achieve
- Why we are Invested in AUZ
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.