AL3: ~$2.2M sale to Northrop Grumman - one of the ‘big four’ US military contractors. $78M sales pipeline. ~$60M market cap with $24.4M cash in the bank.
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 7,630,973 AL3 Shares and the company’s staff own 220,143 AL3 Shares at the time of publishing this article. The Company has been engaged by AL3 to share our commentary on the progress of our Investment in AL3 over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
AML3D (ASX:AL3) is one of my favourite stocks for the current market and geopolitical climate.
AL3 sells defence/military manufacturing tech (3D printing metals parts) that helps speed up military manufacturing.
(faster, better, stronger and cheaper than traditional methods)
And leaders across the US military AND government, including the US President have all stated that military manufacturing needs to be much faster and more efficient (will show you all the direct quotes in a second)
AL3 has opened a US based facility and has a letter from the US Navy saying their tech will be pivotal in rolling out 100x 3D printing systems AND printing ~1600 complex metal parts per year by 2030. (source)
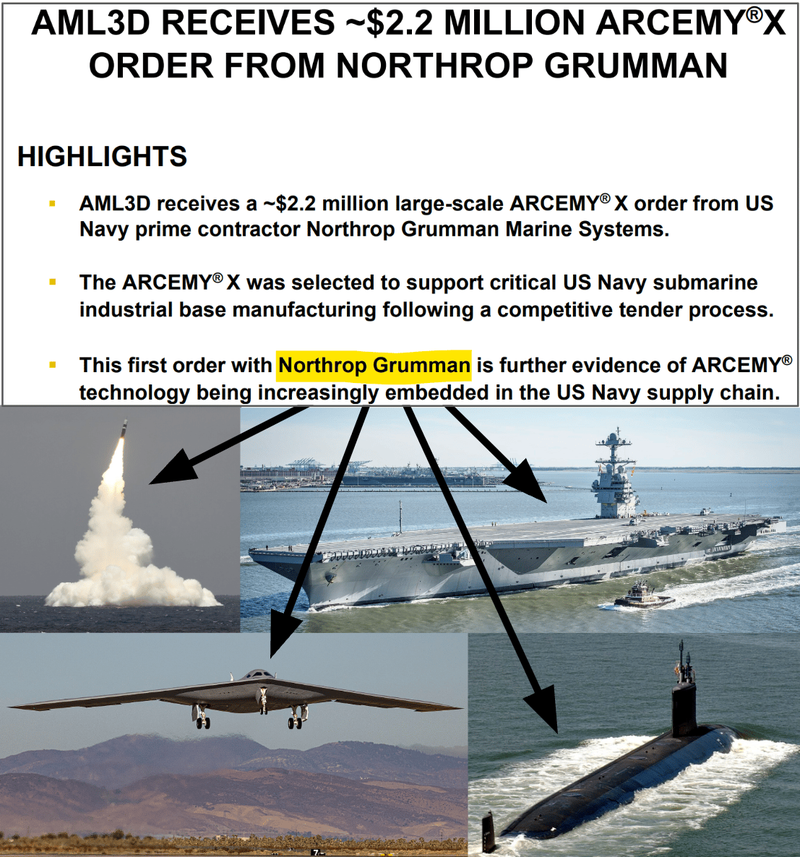
And Today AL3 announced a $2.2M sale to Northrop Grumman - one of the four major military industrial base companies.
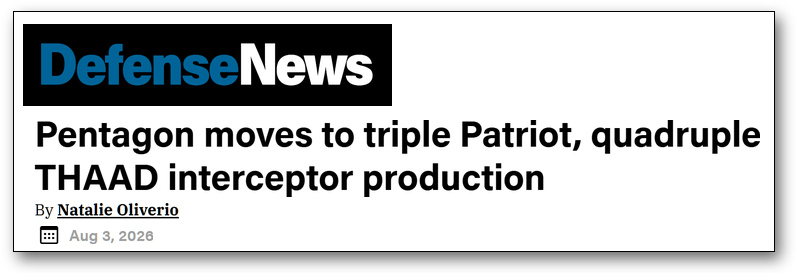
Less than 90 days ago, the US Pentagon started signing deals to triple missile and quadruple interceptor rocket production:
(source)
One of the companies helping deliver that production is $111BN Northrop Grumman.
A US Navy Prime Contractor - and the fourth-largest defence contractor on the planet in terms of revenues.
Today, Northrop Grumman became a customer of our small cap defence Investment AL3
... Ordering one of AL3’s ~$2.2M large-scale metal 3D printing systems - “to support critical US Navy submarine industrial base manufacturing”
Including a two-year maintenance and services package.
Aside from supporting critical US Navy submarines, Northrop Grumman also builds stealth bombers, military drones, satellites, rocket motors, radar and electronic warfare systems.
Hopefully they are impressed with AL3’s tech and this first deal leads to many more? Let’s see.
(source)
On 7 January 2026, The US President Donald Trump signed an executive order targeting slow production and underinvestment by major defence contractors. (source)
He said: “While the United States produces the best military equipment in the world, we do not make enough of it quickly enough to meet the needs of our military and our partners.”
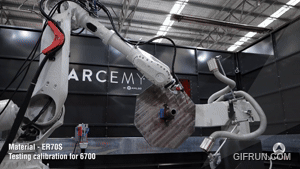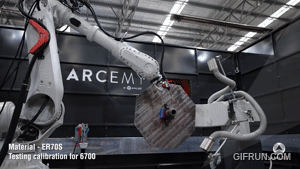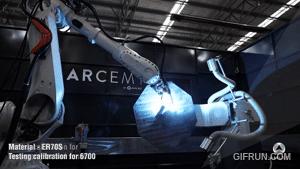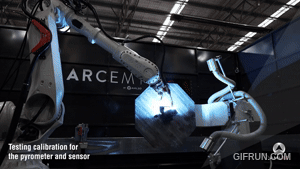
This is where AL3’s tech comes in:
(source)
AL3 makes 3D metal printing systems that produce complex metal parts - faster, better, stronger and cheaper than traditional foundry methods.
AL3 also owns and operates its own fleet of 3D printers - to print parts for customers on demand.
(customers like the US Navy, defence, shipbuilding, oil and gas, aerospace and utilities).
AL3 is currently capped at $60M.
With $24.4M cash in the bank at 30 September. (source)
AL3 had its best year ever in FY26 hitting $12.5M in revenues.
AND AL3 carried over ~$16.8M in orders to FY27 - that’s BEFORE today’s deal with Northrop Grumman.
So next year should be an even better year...
That’s before AL3 lands any more big deals from its $78M sales pipeline (it says these are “near-term order opportunities”).
Northrop’s CEO on its latest quarterly call said it is seeing: “unprecedented levels of demand for defense capabilities”
And that “we are investing to rapidly expand our munitions and missile capacity to meet operational needs”
And today AL3 signed its first order with Northrop - check out what Northrop had to say about AL3 too:
“AML3D will play an important role across multiple programs, accelerating SIB (Submarine Industrial Base) manufacturing in the United States”.
Massive - coming from one of the ‘big four’ US defence contractors.
Also massive because we think this is one foot in the door for AL3 to start selling its systems into other parts of the US military industry complex - not just the Navy.
AL3 already sells to companies like Huntington Ingalls (the largest military shipbuilder in the USA), Austal USA - and now Northrop.
All of those AL3 customers are entrenched in the US navy supply chain.
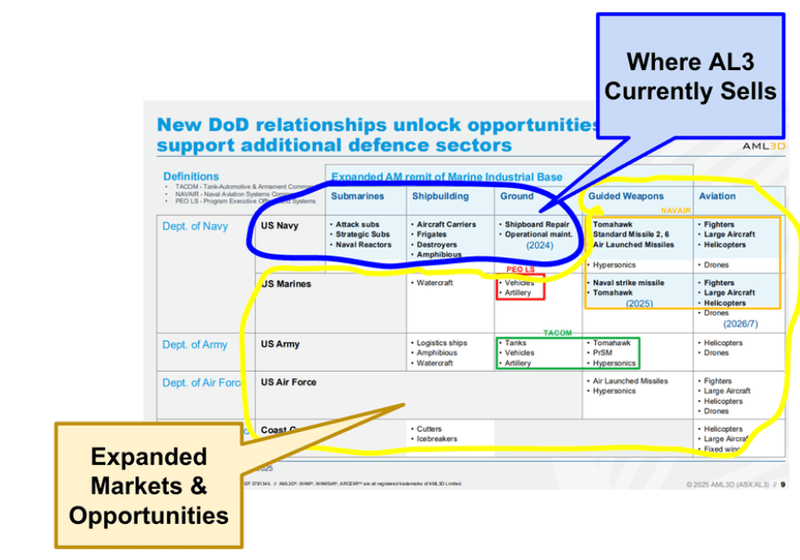
But we have referred to the image below in the past which shows:
- Blue box = Where AL3 sells today (US Navy submarines and shipbuilding)
- Yellow box = Where we think AL3 could sell next - Guided weapons, aviation, the Army, the Air Force.
(source)
Northrop Grumman sells into the blue and yellow boxes in the image above...
So AL3’s 3D printers will go into a plant making parts for Virginia-class attack submarines, and missile launch systems. (source)
AND potentially everything else Northrop makes, like B-21 bombers, the solid rocket motors for Patriot and THAAD interceptors.
Foot into the door for sales into the Army, Air force etc etc?
We think it could be.
We note - Huntington Ingalls (with six AL3 systems installed/ordered) also produces aircraft carriers AND destroyers AND unmanned systems.
So that’s two CURRENT customers that could lead those sales channel changes...
AL3 is working on the potential catalyst for sales into the Aerospace space RIGHT NOW
Five weeks ago, AL3 joined “industry and research partners, including an aerospace prime, in an advanced Aerospace manufacturing project.” (source)
With the aim of “achieving qualified Aerospace tooling production capability”.
Basically meaning - AL3 is having its 3D printing tech qualified for use in the aerospace setting.
We googled “aerospace prime” and here is what came up:
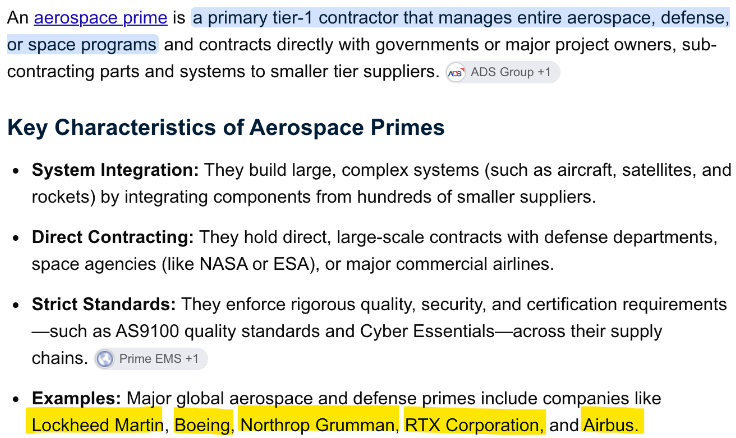
We take that as AL3 laying the ground work for getting its 3D printing (additive manufacturing) tech qualified for use in supply chains where companies like Boeing, Airbus and the big defence aerospace contractors operate.
(Or a Northrop who is now already an AL3 customer.)
We have said before that we think AL3’s integration into the US Navy supply chain could open doors into other parts of the military industrial complex.
Now we are seeing it play out in stealth (the qualification work in the background) - then one day AL3 announces a sale into one of those supply chains and the market starts to price that growth potential into the stock.
Things like qualifying a tech are not really seen as “sexy” by the market - so they don't really get any recognition (in a company's share price) until they actually turn into signed deals.
But it has to be done... and when completed, we think it could be a game changer for AL3’s business.
We think AL3 selling into the US Navy is company making on its own anyway
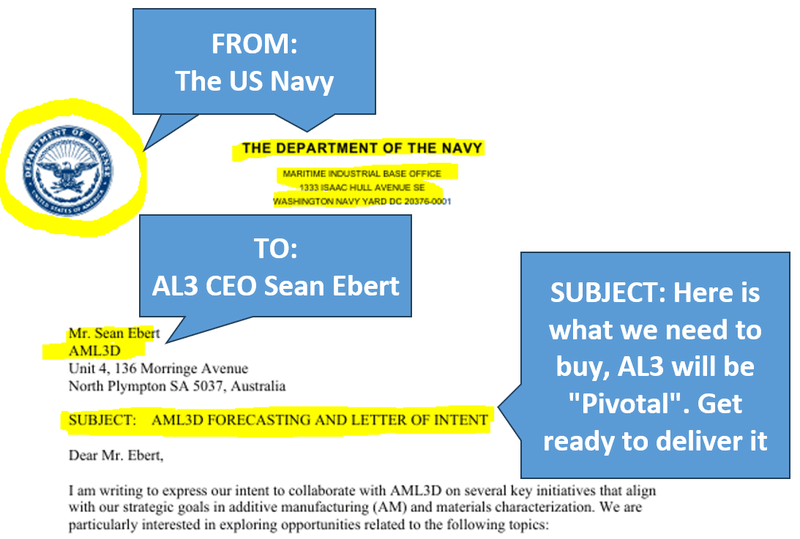
Remember this letter from July last year:
(Source: US Navy Letter of Intent to AL3)
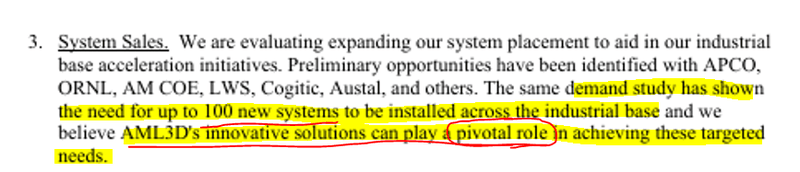
AL3 received a letter from the US Navy forecasting demand for ~100 x 3D printing systems and...
Up to 1,600 x 3D printed parts per year by 2030 across the US submarine and shipbuilding industrial base.
And it told AL3 it would play (in the US Navy's own words) a "pivotal role in achieving these targeted needs."
Here is what an AL3 “3D metal parts printing farm” could look like in the future (we made this using AI):
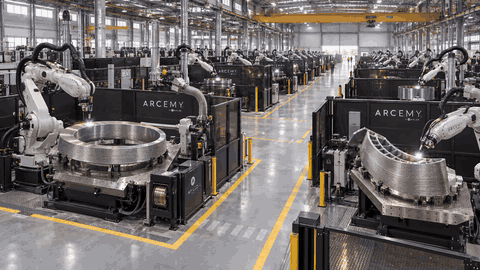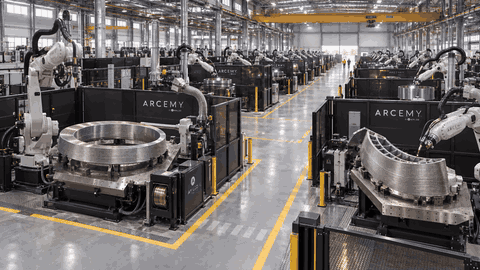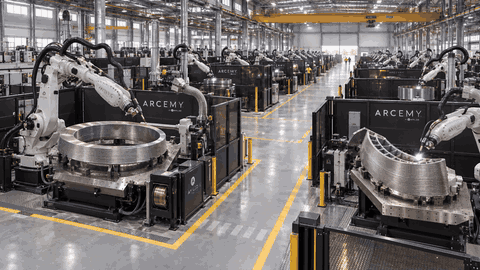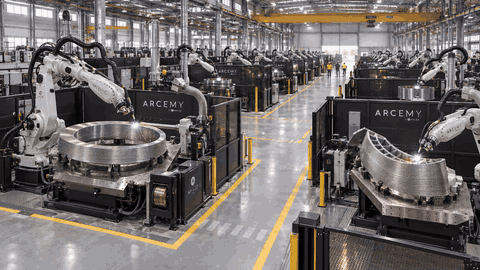
(hypothetical AI generated image by us)
We think AL3’s penetration into the US Navy supply chain alone could be company making...
Quick back of napkin calcs on that US Navy LOI:
AL3’s systems have sold for between ~$1M and $2.5M each - so 100 systems is somewhere between ~$100M and $250M in gross revenue.
Then there are the ~1,600 parts per year - who knows how much of that is printed by AL3 or AL3 systems...
(No guarantee AL3 captures anywhere near all of that, these are just back of napkin calcs based on a number of assumptions we could have gotten wrong)
So far, since that letter, AL3 has landed:
- A $4.5M order for two systems from a subsidiary of US$15.4BN Huntington Ingalls Industries (HII), the largest military shipbuilder in the USA (source)
- A $9.9M follow-up order (four more systems) from the same customer - AL3's biggest ever order (source)
- A $2.6M order to 3D print five submarine parts the US Navy can no longer source anywhere else (source)
- A $1.7M system sale to a US Navy component supplier (source)
- AL3's first portable, containerised 3D printing system live at the US Navy's Additive Manufacturing Centre of Excellence (source)
- A ~$0.5M production parts order from Austal USA Advanced Technologies (source), AND
- Today's ~$2.2M Northrop Grumman order. (source)
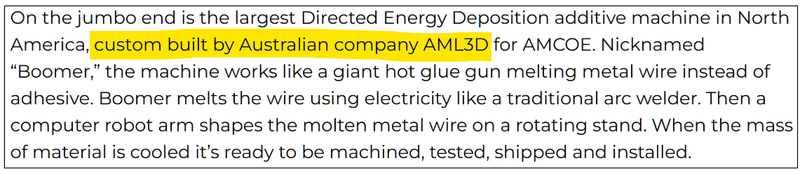
AND the largest “Directed Energy Deposition 3D printer” in North America in the US Navy's Additive Manufacturing Center of Excellence in Danville, Virginia was built by AL3.
(source)
Little old $60M capped AL3 centre stage in the US additive manufacturing game - nice...
Eventually, we think success in the US could unlock the EU/UK markets too.
AL3 has entered the UK defence market - can AL3 run its US playbook in the UK/EU?
What we know right now is that AL3 is currently running a material feasibility program with ~A$108BN BAE Systems in the UK.
AND has distribution deals in place for both the UK and Europe.
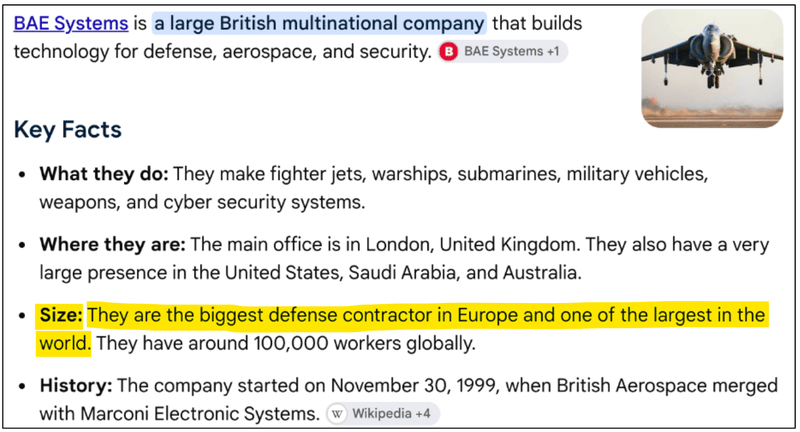
BAE systems is the biggest defence contractor in Europe and one of the biggest in the world.
(source - we googled “who is BAE systems”)
We think that right now, the market is completely missing the UK/EU opportunity for AL3.
And how quickly things can happen after all of the groundwork has been completed.
For example, AL3 in the USA, went from materials qualification work and zero system installs in 2023.
To - three years later having 17 systems contracted in the US, record revenue, and a $78M sales pipeline. (source)(source)(source)
We think AL3 in the UK/EU is where it was in the US back in 2023.
- AL3 is running materials feasibility work with BAE Systems right now
- Has UK/EU distribution deals signed, AND
- AL3 says it is in "advanced negotiations" for its first European ARCEMY system order. (source)
That first order would trigger AL3 building a $5M European Technology Centre - exactly the same way AL3 launched into the US.
And then we would hope the US style deal cycle kicks off leading to a similar 10+ system sales deal...
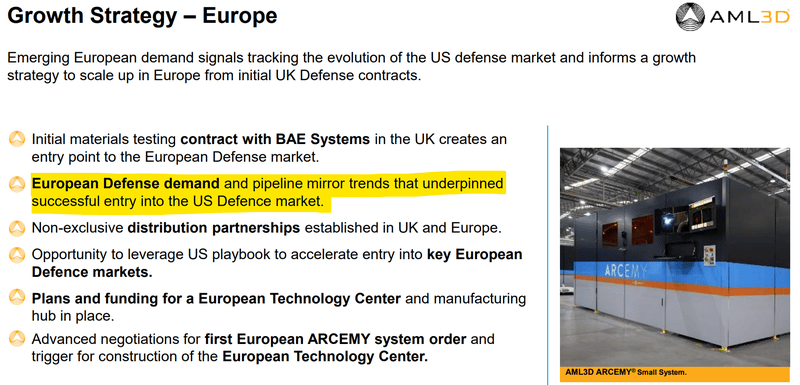
AL3’s most recent deck calls out the potential US style expansion in the EU too - here is what AL3 had said:
"European Defense demand and pipeline mirror trends that underpinned successful entry into the US Defence market."
(source)
We think the macro is relatively strong for AL3 too.
Europe at the 2025 NATO summit agreed to lift defence spending to 5% of GDP by 2035.
(source)
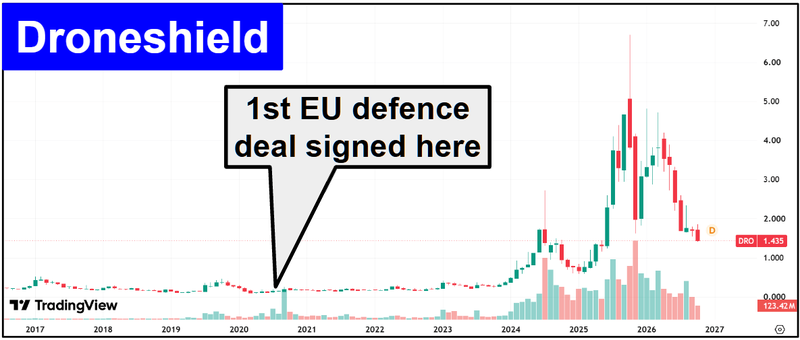
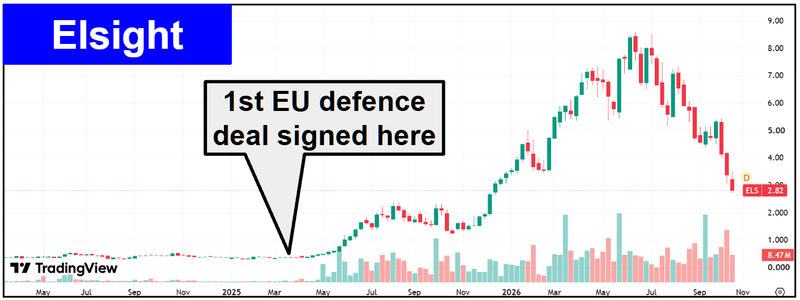
The UK/EU has also been the reason for so many ASX defence stocks re-rating.
DroneShield’s run to over ~$5.5BN market cap was off the back of deals in the EU defence space.
And the same is true for ~$637M capped Elsight (which peaked near $1.9BN).
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
We think that if a few of the familiar names (to ASX punters) in the EU/UK start announcing deals with AL3, the market could start to price the EU/UK expansion into AL3’s share price.
For now though, the main game is still very much the US...
Why AL3 now?
The reason we are bullish AL3 from a macro perspective right now goes back ~200 years...
Bear with us on this one.
Why is the US moving so fast on 3D printing?
Because for the last ~200 years, global superpower status has tracked one metric: shipbuilding capacity.
The last global superpower before the US was Britain.
At its peak in the 1890s, Britain built ~80% of the world's shipping tonnage. (source)
Then came the World Wars and at the peak of the war, the US was delivering ~800,000 tons of new ships every month - roughly 70 times its pre-war rate.
One California shipyard got so fast it built an entire ship in 7 days.
By 1945, the US had the largest navy ever assembled, the world's reserve currency... and the superpower title.
Britain's shipbuilding share never recovered - it slid from 57% in 1947 to 17% a decade later, and today the UK builds essentially no commercial ships at all. (source)
Now the same thing is happening between China and the USA.
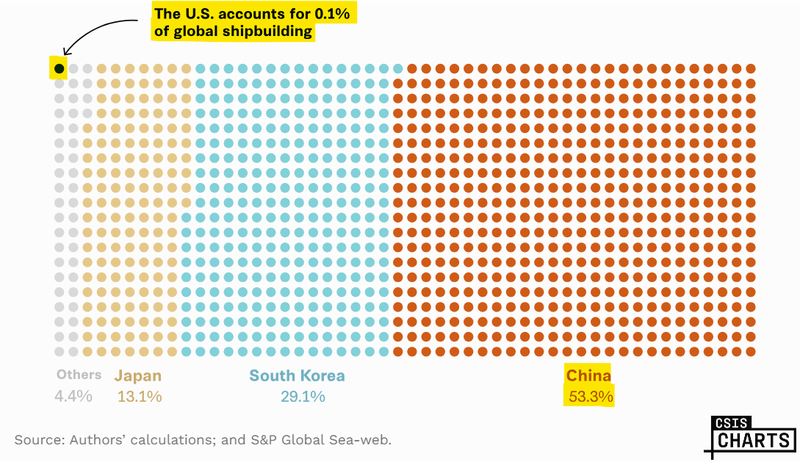
China now builds more than 50% of the world's commercial ships.
The USA builds 0.1%. (source)
(source)
One single Chinese state-owned shipbuilder (CSSC) built more commercial tonnage in 2024 alone than the entire US shipbuilding industry has built since World War II. (source)
US Naval Intelligence estimates China's shipbuilding capacity at ~23.2 million tons per year versus less than 100,000 tons for the USA.
That is 232 times more capacity. (source)
So it makes sense that shipbuilding capacity has become one of the few genuinely bipartisan priorities in Washington.
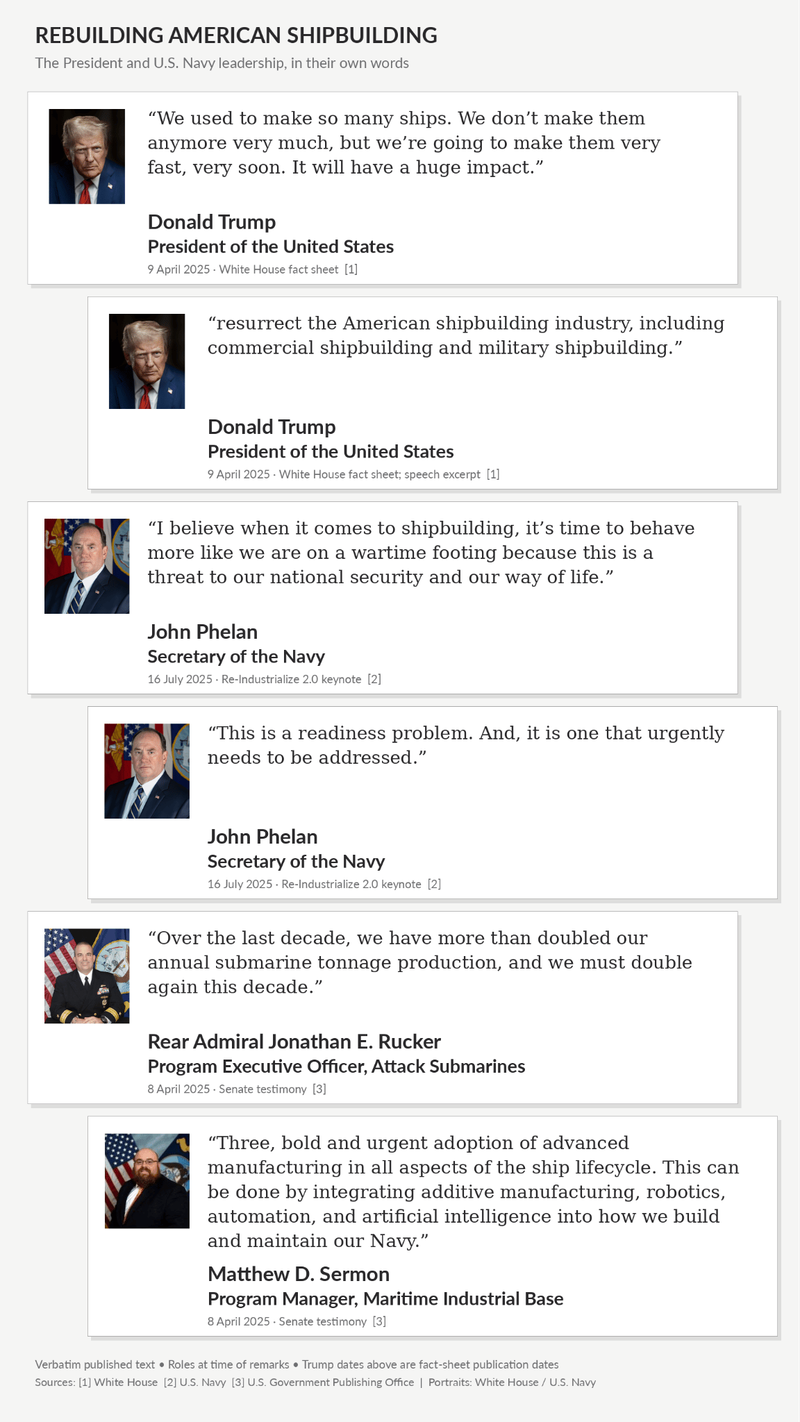
Here is what the US President Donald Trump and Navy leadership are saying about the need to catch up:
(source) (source) (source) (source) (source) (source)
If the future is going to be robots working with software to build stuff, that’s where additive manufacturing comes in - and why the US Navy has been throwing money and urgency at it:
- The BlueForge Alliance was allocated US$951M specifically to rebuild the US submarine industrial base (source)
- The "Big Beautiful Bill" earmarked US$450M for additive manufacturing in shipbuilding. (source - page 110)
- The US Department of War's FY2026 budget allocated US$3.3BN for additive manufacturing (source)
- The Navy's FY27 budget request asks for US$65.8BN for shipbuilding. (source)
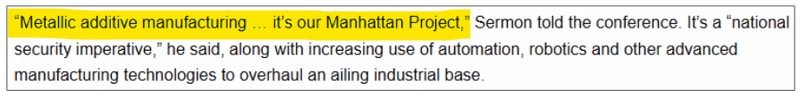
The US Navy has called metallic additive manufacturing its "Manhattan Project" - and told parts suppliers to either adopt 3D printing or get left behind.
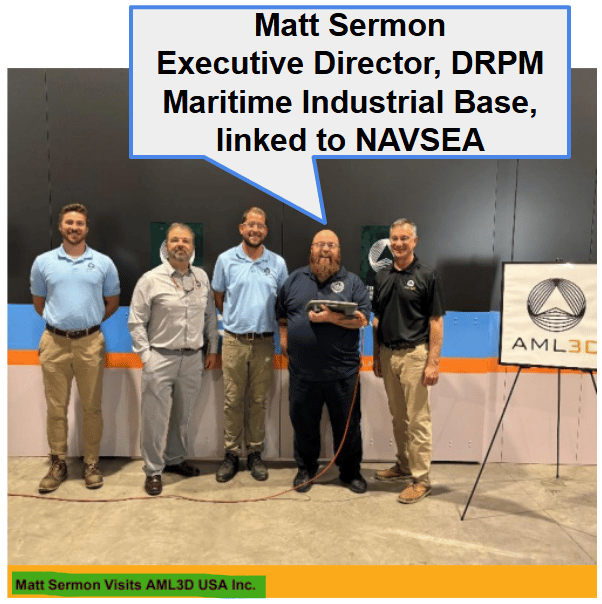
Here's that quote from Matt Sermon, Executive Director of PEO-Strategic Submarine (linked to NAVSEA):
(source)
NAVSEA is responsible for the acquisition, development and maintenance of US Navy submarine systems and programs - and is directly linked to Huntington Ingalls, AL3's biggest customer.
This is the same Matt Sermon who featured in AL3’s latest Investor presentation on slide 17:
(source)
IF this is going to be the future of "modern manufacturing” - then we think AL3 may have one of the biggest tailwinds of any macro thematic in the market right now:
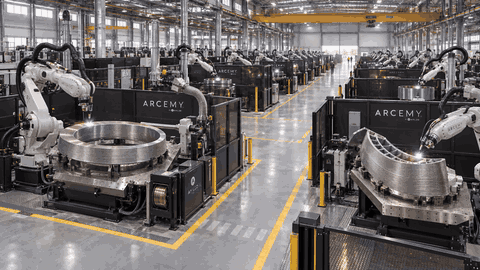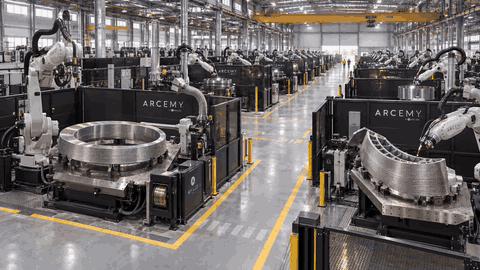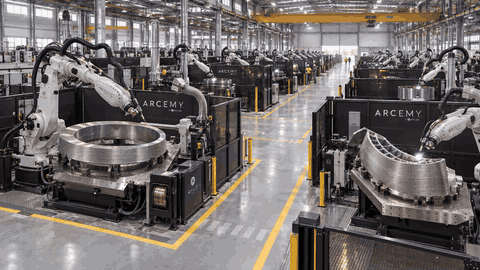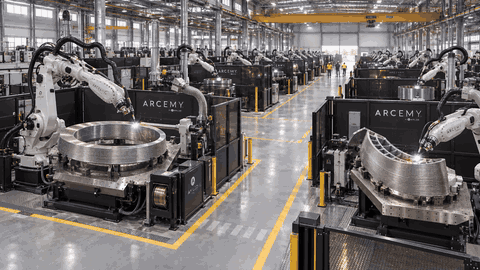
(This image is AI generated - a good use of tokens we think - much better then our planet taking a dump reading the AFR with carefully placed sweat beads - if you know you know)
Our AL3 'Big Bet':
"AL3 re-rates to a $500M market cap on achieving significant sales growth across an expanding range of industries and jurisdictions"
NOTE: our "Big Bet" is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and regulatory risk - just some of which we list in our AL3 Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
Recap: What does AL3 do?
AL3’s technology combines robotics, welding, automation and software.
A robot arm paired with AL3’s software welds layers and layers of metal wire into the shape of the required metal part.
And it gets the job done faster and cheaper than the traditional method of casting parts. (source)
(up to ~75% faster than conventional casting and forging with ~95% less material waste)
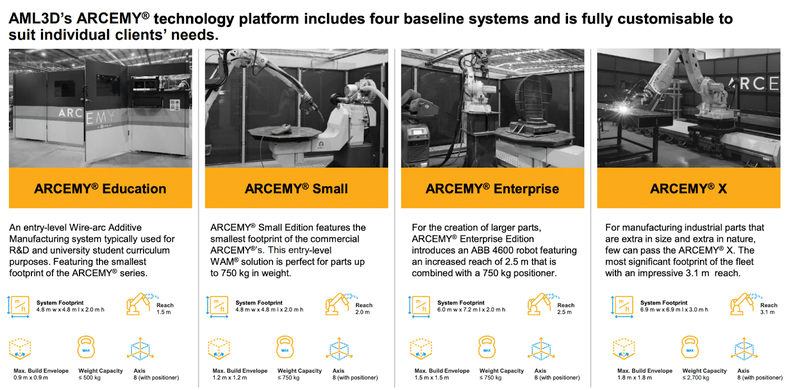
(source)
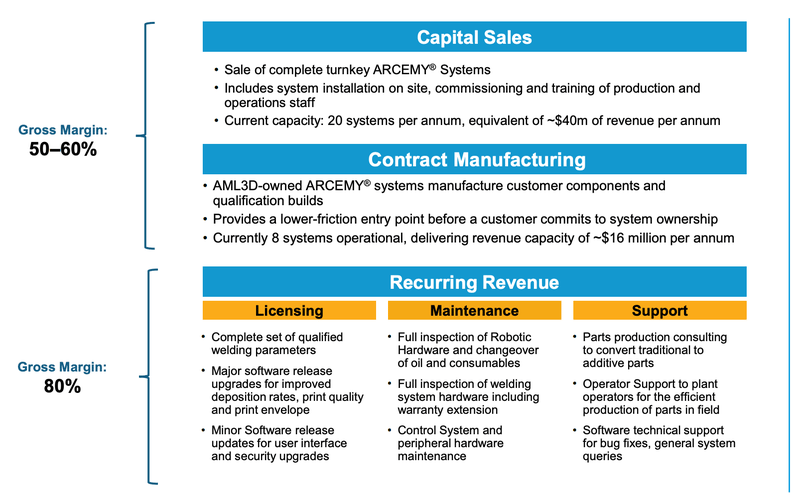
AL3 makes revenue from three areas:
- ARCEMY system sales - this is where the customer pays upfront for one of AL3’s printing systems and gets it installed on site (typically ~$1M to $2.5M each).
- Software & services recurring fees - ~$250K per year, per system for software licensing, hardware maintenance and tech support.
- Manufacturing/prototype deals - this is where AL3 uses its own fully owned systems to print specific parts for customers.
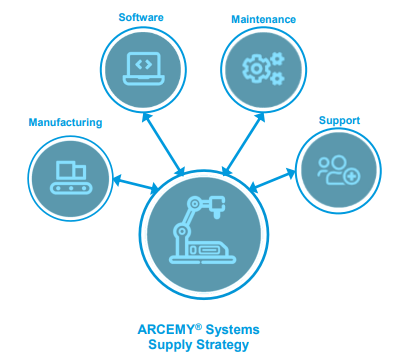
(source)
Here is a great slide from AL3’s recent investor presentation summarising the model:
(source)
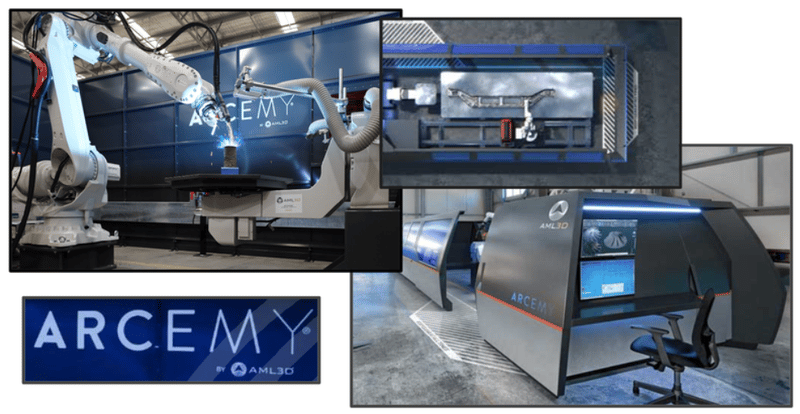
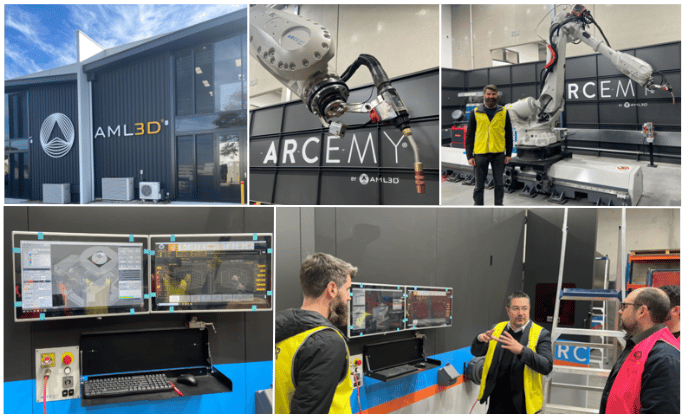
We have been to AL3’s facilities, here is what we saw
We have been to AL3's Australian facility in Adelaide a few times to check the systems out and it's pretty cool to see these things in operation.
To see our full site visit write up read: Our AL3 site visit and what we learnt
Here are some pics from the site visit:
What's next for AL3?
🔄More system sales into the US market
We want to see more orders from the six US naval base companies named in the Navy's LOI.
The two installations we are looking forward to seeing the most is today’s Northrop Grumman order AND the previous Huntington Ingalls orders. (source) (source)
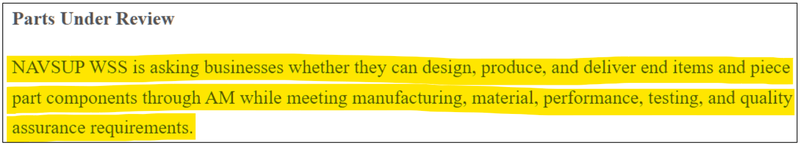
We have also noticed that a 129-part RFI IS open from the US Navy and responses close on the 2nd of November - hopefully something comes from that for AL3. (source)(source)
The article below also mentions AL3 has been contracted to produce submarine parts no longer produced elsewhere.
(source )
We also want to see progress from the 🔲 Aerospace tooling qualification with the unnamed aerospace prime.
🔄US facility expansion
AL3 has flagged that it will be doubling the capacity of its Ohio facility.
AL3 plans to invest $12M to expand production capabilities.
We don't expect things to suddenly take off but a few system sales every few weeks/months would be a great outcome here.
🔄UK and European market entry
AL3 has appointed distributors in the UK and Germany, and is running alloy testing with BAE Systems.
We think the alloy testing contracts are precursors for system sales/manufacturing deals - these testing contracts are where the bigger guys test AL3’s tech before buying.
Sales into Europe or the UK could change the way the market sees AL3’s future growth potential.
AL3 has said in the past it “has the cash reserves to fund a $5 million investment in a UK Technology Centre to support UK and European demand” (source)
What could go wrong?
The single biggest risk right now is without a doubt order conversion risk.
The US Navy's Letter of Intent is a demand forecast, not a contract - it's non-binding, contains no guaranteed dollar value, and the Navy named other companies alongside AL3 that could help meet its targets.
Sales risk
There is always the possibility that AL3 does not close more sales, and its financial performance suffers as a result.
Source: "What could go wrong" section - AL3 Investment Memo 27 June 2024
Other Risks
Like any small-cap advanced manufacturing and technology company, AL3 carries significant risk, here we aim to identify a few more risks.
Qualification and technological integration risk is a key hurdle, as expanding into new verticals like aerospace tooling or European defence primes requires rigorous material testing that can take substantial time and may ultimately fail to meet military-grade specifications.
Long sales and procurement cycles in the defence sector mean negotiations and contract awards can drag out for quarters or face unexpected political and budgetary delays.
Expansion across Australia, the United States, and now Europe places heavy demands on executive bandwidth and operational resources. Opening facilities such as the planned UK Technology Centre and expanding the Ohio site could stretch internal management capacity thin.
Capital expenditure commitments for international facility expansions and ongoing research and development also create significant cash burn, which introduces the ongoing risk of capital raises and shareholder dilution if commercial cash flows do not ramp up quickly enough.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our AL3 Investment Memo
You can read our AL3 Investment Memo in the link below. We use this memo to track the progress of all our Investments over time.
In our AL3 Investment Memo, you can find the following:
- What does AL3 do?
- The macro theme for AL3
- Our AL3 Big Bet
- What we want to see AL3 achieve
- Why we are Invested in AL3
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.