PUR banks A$2.08M cash from investment sale
Our lithium Investment Pursuit Minerals (ASX: PUR) just sold part of its shareholding in London listed Kendrick Resources, banking ~A$2.08M in net proceeds.
PUR's main focus is its Rio Grande Sur project that hosts a 1.26Mt LCE JORC resource in Argentina's Lithium Triangle.
Just over a week ago PUR released expanded economics for the project:
- US$1.09BN NPV at a 26.2% IRR
- Ore reserve up ~250% to 438,000 tonnes LCE
- Staged expansion from 5,000tpa to 17,500tpa
PUR then followed that up with a US$40M non-binding MoU with ~A$9.6BN batterygiant EcoPro, covering Stage 1 offtake ,a US$20M pre-payment and US$20M for 20% of the project.
Early in our Deep Dive on the MoU last week, we flagged funding as the near term risk we were watching (PUR had just $761k cash at 30 September):
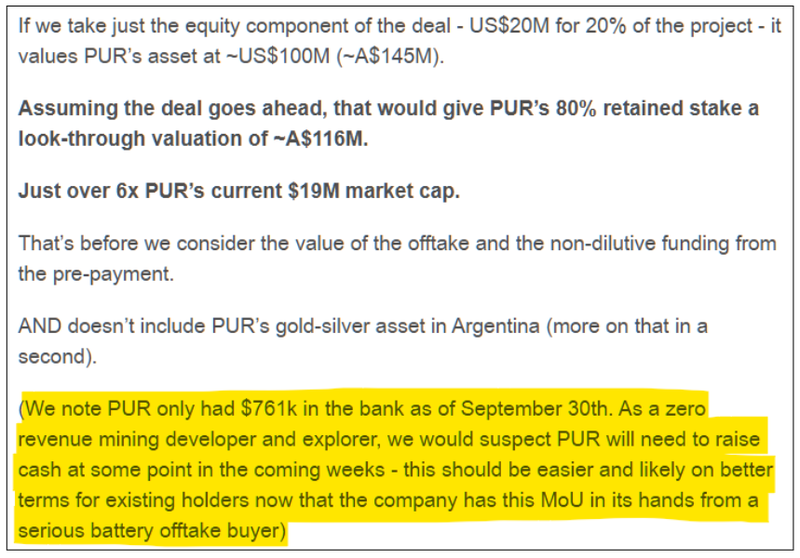
(source - our 9th Nov article)
So with today's update, this takes PUR's cash balance to ~A$2.03M (as of today, not September 30). (source)
So this helps in the near term, and may give PUR the room to get the MoU to binding, which is when the cash could start to flow in for the development financing. (no guarantees it gets there)
PUR still holds Kendrick shares worth ~A$1.26M at current prices, so it could realise more value from selling the rest:
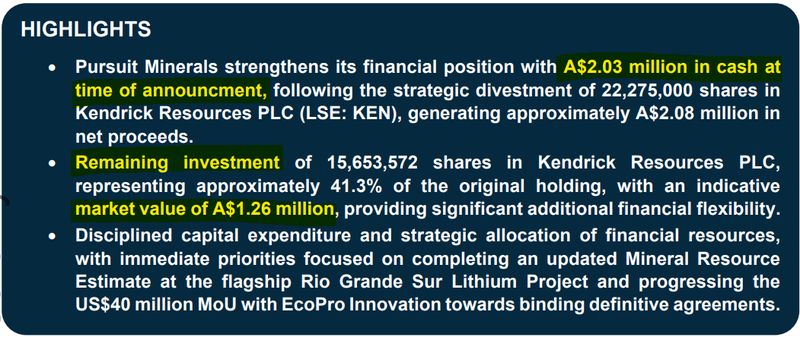
(source)
More on PUR’s US$40M MoU announced last week
A week ago PUR announced it had signed a US$40M (~A$58M) MoU for its advanced stage lithium project in Argentina with the lithium arm of Korean battery conglomerate ~A$9.6BN EcoPro group.
EcoPro Group is the second biggest battery cathode material producer in the world.
(they cover every aspect of the battery manufacturing supply chain)
The same group supplying battery materials to the likes of Samsung.
(lithium is the key material in batteries, remember - in the cathodes)
Now, that conglomerate, under the proposed terms of the just signed MoU, could come into PUR’s lithium asset in a three way deal, through:
- 100% offtake of PUR’s Stage 1 production - ~5,000tpa of lithium carbonate for the life of the mine.
- US$20M lithium pre-payment - US$20M of development funding, drawn against build milestones and repaid in lithium.
- US$20M equity in the project - EcoPro takes 20%, PUR keeps 80% and stays on as operator.
This deal is a “Memorandum of Understanding” at this point - and is non-binding with respect to the proposed investment, funding and offtake arrangements - which remain subject to due diligence, definitive agreements, necessary approvals, and other conditions precedent.
But we have seen EcoPro announce and then COMPLETE deals with small ASX listed companies before:
- A$6.8M equity investment into Blackstone Minerals - nickel in Vietnam. Completed 21 April 2020. (source)
- 7,000tpa binding lithium carbonate offtake with Ioneer - Lithium in Nevada, USA. Signed 30 June 2021, upsized to 7,000tpa 16 Feb 2022; still in force. (source)
- A$8M equity investment into Green Technology Metals - lithium in Canada. Completed October 2024. (source)
So they have appetite, and can and do complete deals with ASX small caps…
If we take just the equity component of the deal - US$20M for 20% of the project - it values PUR’s asset at ~US$100M (~A$145M).
Assuming the deal goes ahead, that would give PUR’s 80% retained stake a look-through valuation of ~A$116M.
Around 5.5x PUR’s current $21M market cap.
That’s before we consider the value of the offtake and the non-dilutive funding from the pre-payment.
AND doesn’t include PUR’s gold-silver asset in Argentina.
See more on
- The MoU
- PUR’s lithium drilling and PFS addendum
- Plus PUR’s gold/silver project which should be drilled soon
In our coverage from last week: PUR: The world’s second biggest battery cathode maker signs US$40M MoU with $19M capped PUR.
What's next for PUR?
After the MoU announcement last week, the main things we want to see are the DDH-4 assays, and the pilot plant getting set up on site so EcoPro can start qualifying PUR's product.
🔄 Progress lithium project in Argentina
We want to see PUR develop this project, it has a JORC resource estimate, further drilling showing high grades and now a MoU looking at development financing.
Here are the catalysts we are hoping to see PUR deliver in the short-medium term:
- 🔄 Assay results from hole #4 (currently in the lab)
- 🔄 Pilot plant relocation to site, then commissioning approvals
- 🔄 Commercial evaporation pond approval (application lodged)
- 🔲 Updated JORC resource incorporating recent two holes (hole #3 and hole #4)
- 🔲 Product samples to EcoPro for qualification
- 🔲 Project debt (up to US$120M)
- 🔲 Definitive agreements with EcoPro (conditions deadline 31-Dec-2027)
🔲 Maiden drill program at gold-silver project in Argentina
PUR announced this project around 12 months ago and has been running surface exploration/geophysics to prepare for its own maiden drilling here, which should be soon.
We also want to see PUR drill this project, we covered it in the recent Deep Dive article here: PUR also has a gold-silver project that we like
Here are the catalysts we are tracking across this project:
- ✅ Geological mapping - five targets defined
- ✅ IP survey - 8-hole, 3,350m program designed
- 🔲 Rig mobilisation and drilling commences
- 🔲 First assays from Sascha and Marcelina