PUR: The world’s second biggest battery cathode maker signs US$40M MoU with $19M capped PUR.
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 5,675,105 PUR Shares and 610,356 PUR Options at the time of publishing this article. The Company has been engaged by PUR to share our commentary on the progress of our Investment in PUR over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
The global AI and robots build-out is coming.
Super-intelligence and hordes of genius helper-robots - self improving and rebuilding themselves faster and faster as they get smarter and smarter.
Solving cancer, helping us live forever, designing and building anything we want, doing our dishes and laundry.
We have said many times that the bottleneck to this abundant future will be commodities supply.
Materials to build it all and then the electricity to power it.
Specifically generation, transport and storage of electricity.
And we have started to see deals in the electrification minerals space...
THIS MORNING:
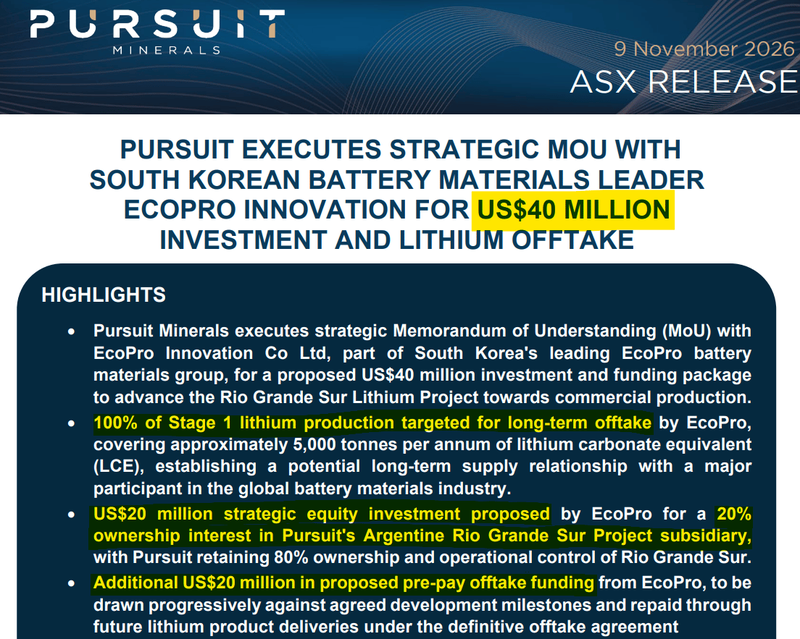
$19M capped Pursuit Minerals (ASX:PUR) just signed a US$40M (~A$58M) MoU for its advanced stage lithium project in Argentina...
...with the lithium arm of Korean battery conglomerate ~A$9.6BN EcoPro group.
EcoPro Group is the second biggest battery cathode material producer in the world.
(they cover every aspect of the battery manufacturing supply chain)
The same group supplying battery materials to the likes of Samsung.
(lithium is the key material in batteries, remember - in the cathodes)
Now, that conglomerate, under the proposed terms of the just signed MoU, could come into PUR’s lithium asset in a three way deal, through:
- 100% offtake of PUR’s Stage 1 production - ~5,000tpa of lithium carbonate for the life of the mine.
- US$20M lithium pre-payment - US$20M of development funding, drawn against build milestones and repaid in lithium.
- US$20M equity in the project - EcoPro takes 20%, PUR keeps 80% and stays on as operator.
This deal is a “Memorandum of Understanding” at this point - and is non-binding with respect to the proposed investment, funding and offtake arrangements - which remain subject to due diligence, definitive agreements, necessary approvals, and other conditions precedent.
But we have seen EcoPro announce and then COMPLETE deals with small ASX listed companies before:
- A$6.8M equity investment into Blackstone Minerals - nickel in Vietnam. Completed 21 April 2020. (source)
- 7,000tpa binding lithium carbonate offtake with Ioneer - Lithium in Nevada, USA. Signed 30 June 2021, upsized to 7,000tpa 16 Feb 2022; still in force. (source)
- A$8M equity investment into Green Technology Metals - lithium in Canada. Completed October 2024. (source)
So they have appetite, and can and do complete deals with ASX small caps...
If we take just the equity component of the deal - US$20M for 20% of the project - it values PUR’s asset at ~US$100M (~A$145M).
Assuming the deal goes ahead, that would give PUR’s 80% retained stake a look-through valuation of ~A$116M.
Just over 6x PUR’s current $19M market cap.
That’s before we consider the value of the offtake and the non-dilutive funding from the pre-payment.
AND doesn’t include PUR’s gold-silver asset in Argentina (more on that in a second).
(We note PUR only had $761k in the bank as of September 30th. As a zero revenue mining developer and explorer, we would suspect PUR will need to raise cash at some point in the coming weeks - this should be easier and likely on better terms for existing holders now that the company has this MoU in its hands from a serious battery offtake buyer)
(source)
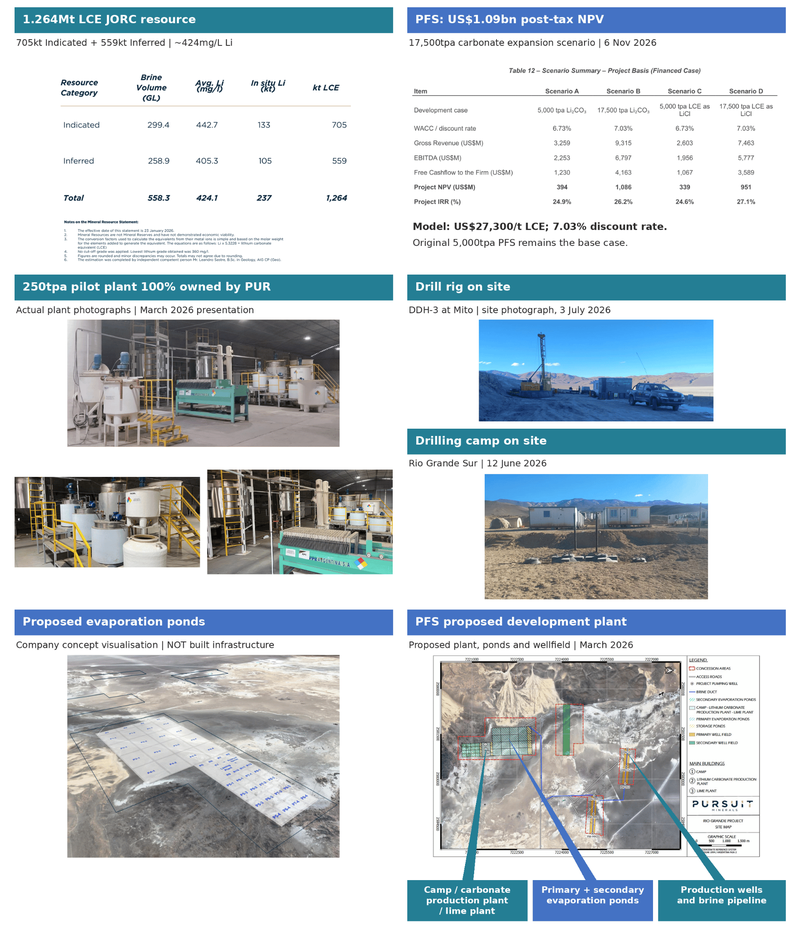
PUR’s project has a 1.26Mt Lithium Carbonate Equivalent (LCE) JORC resource estimate.
AND a Pre-Feasibility Study (PFS) showing a Net Present Value of US$394M (from US$136.5M of Stage 1 CAPEX).
In a more bullish lithium market environment, using those May 2026 prices, and the full project expansion, that NPV jumps to US$1.09BN.
PUR also has a gold-silver exploration project in Argentina - ~100km from Newmont's 8Moz Cerro Negro mine - about to be drilled by PUR for the first time chasing a “Cerro Negro 2.0” style discovery.
(More on that gold asset further down)
Armed with those two assets, PUR’s market cap, before the market gets to react to today’s deal, is just ~$19M ( ~US$13M).
At the very least, we think today’s MoU from a major battery materials maker should put a nice floor under PUR’s valuation.
In a more bullish market, it would have been one of those announcements that delivered a nice pop up in the share price.
Let’s see how the market reacts this morning.
Again, the look-through valuation of the equity piece of today’s deal alone is ~A$116M for the 80% that PUR would end up owning (if the deal gets completed).
~6x PUR’s current market cap.
PUR is capped at ~$19M and had ~$760k cash in the bank at 30th September 2026.
We are hoping the market re-rates PUR off the back of today’s announcement, opening a window for PUR to raise cash at a much higher valuation relative to its last traded price.
We are conscious of the deal being non-binding though, so it will be interesting to see how the market reacts.
Anyways...
How did tiny PUR land a deal with a $9.6BN Korean battery materials group?
Maybe this had something to do with it:
(source)
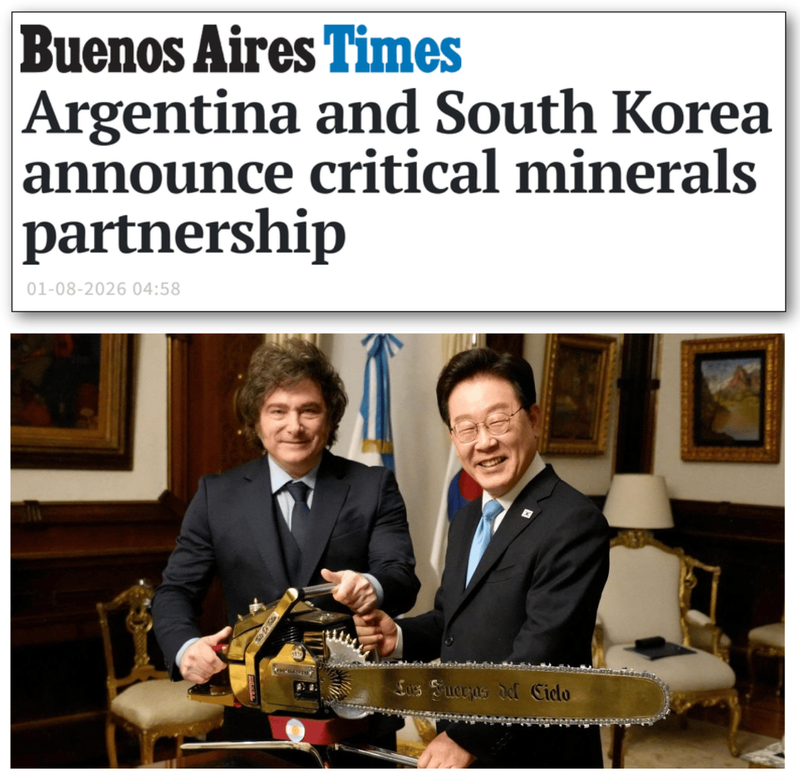
That’s Argentine President Javier Milei and his South Korean counterpart, Lee Jae Myung with Meli’s golden bureaucracy cutting chainsaw.
On 31 July, Argentina and South Korea signed a critical minerals deal - covering exploration, extraction, processing and refining.
The agreement placed an emphasis on "pursuing joint projects across the entire lithium value chain"...
Bang - a few months later, ~A$9.6BN EcoPro - South Korea's biggest cathode materials group - is doing a deal with tiny $19M ASX listed PUR.
Korea imports more than ~95% of its critical minerals, mostly out of China. (source)
The USA now requires at least 60% of a battery's direct material cost to come from outside "prohibited foreign entities" (like China) to qualify for production tax credits.
So Korean cathode makers (like EcoPro) are being forced to secure supply from parts of the world that make it eligible for US tax credits.
This isn't the first deal EcoPro has done with an ASX junior - it also did a deal with $294M capped Ioneer for supply from its lithium project in Nevada, USA.
So it feels like PUR fits somewhere in their “secure supply that we can sell into the US” strategy for the South Koreans.
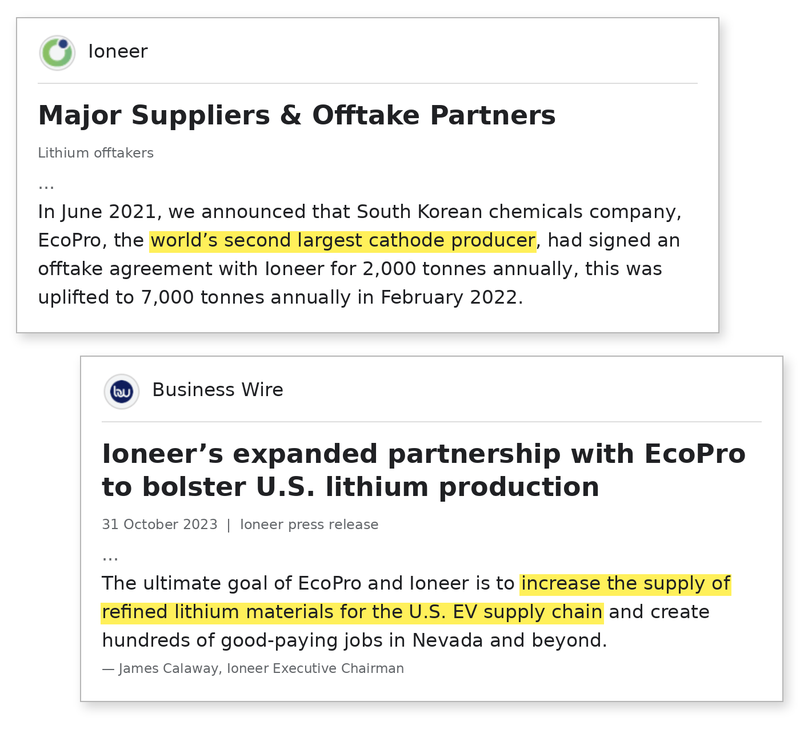
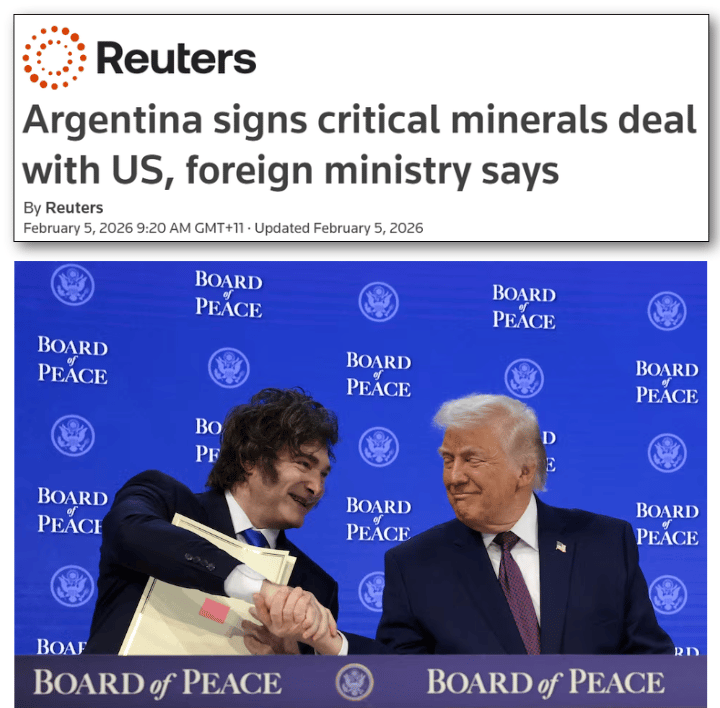
And naturally, with the US and Argentina being on semi-friendly terms and Argentina having the world’s third largest lithium reserves, it makes sense EcoPro would look at Argentina as a jurisdiction to lock in supply from.
(source)
It could also be because PUR’s project is advanced stage
We like PUR’s lithium project because:
- It's a brine project (not hard rock) so if it can be brought into production, its operating costs would be at the bottom of the cost curve - that makes these projects more resilient during tough times. (source)
- The project has an existing 1.26Mt Lithium Carbonate Equivalent (LCE) resource + a 438kt reserve.
- The project is at the Pre-Feasibility Study stage and there are renders/plans of how the project would be developed.
- There is a 100% owned 250tpa pilot plant that’s produced 99.5% lithium carbonate before - this one is key because it makes PUR’s life a lot easier trying to meet the “product qualification” condition from today’s deal.
- PUR’s already well advanced with permitting and has a 2027 construction start target.
- PUR’s plan is to produce a lithium carbonate product (which is exactly what EcoPro use to produce hydroxides).
(source)(source)(source)(source)
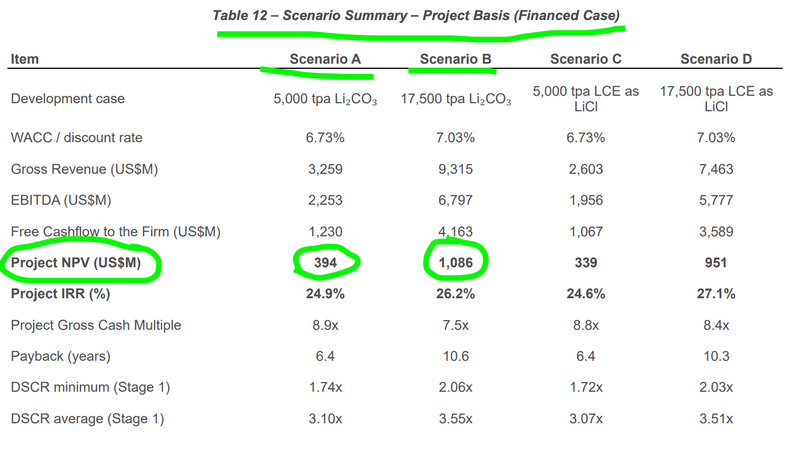
Below is a screenshot of the project economics for a two phased development (based on the recently updated PFS):
- Stage one (US$394M NPV) - a 5,000tpa lithium carbonate operation - which is what EcoPro are coming in for.
- Stage two added (US$1.086BN NPV) - A second plant which would take the project to 17,500tpa, with most of the stage two equity funded out of stage one cash flow.
(all using a lithium price of US$27,300/t).
(source)
PUR is already working on permitting:
- ✅ PUR received environmental approvals to relocate the pilot plant to site and build eight pilot evaporation ponds in September. (source)
- 🔄 Environmental application lodged for the commercial-scale evaporation ponds for the 5,000tpa operation - currently under assessment, it was lodged in September. (source)
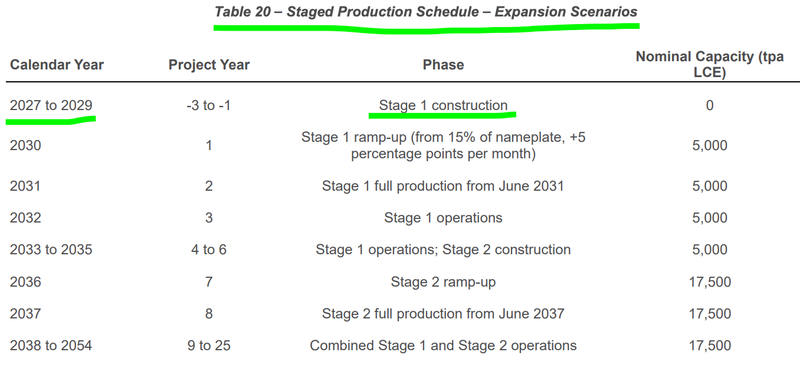
If the timeline in the PFS is anything to go by, PUR COULD technically have the project ready for construction in 2027 (next year) - which also aligns with the conditions deadline on the MoU with EcoPro (December 2027):
(source)
So anyone looking at PUR’s project really doesn’t require that much imagination to see what a developed project might look like...
(or any excel spreadsheets to model the project from scratch)
The way we see it - PUR’s project is one of those assets that needs a lithium bull cycle and one brave financier to come in and get it off the ground.
(or someone like EcoPro who cares more about securing raw material supply)
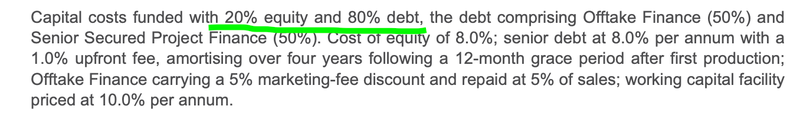
Looking at the updated PFS from Friday - PUR had assumed throughout the study that the project would be financed ~20% with equity and 80% debt:
(source)
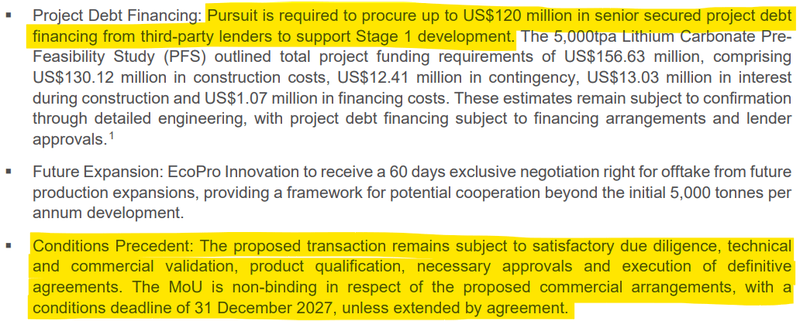
And looking at the MoU signed today - the assumed total stage one funding requirement is ~US$156.6M - construction, contingency, interest during construction and financing costs.
So technically, if the PFS is executed as planned, PUR COULD finance the rest of the CAPEX with debt.
In theory, the ~US$156.6M Stage 1 CAPEX bill could be covered by EcoPro’s US$40M and up to US$120M in project debt.
All of this assumes the EcoPro deal goes from non-binding to binding.
PUR will have until the end of 2027 to meet all of the conditions precedent to EcoPro’s deal.
We think PUR securing that US$120M in senior secured project debt financing from third party lenders is going to be the most important part (and likely most difficult) of the puzzle.
(source)
Of course, there is no guarantee PUR converted this EcoPro MoU to a binding agreement - this could take a while OR never happen - that is a major risk.
We think the one thing that could help get everything over the line will be a run in lithium prices.
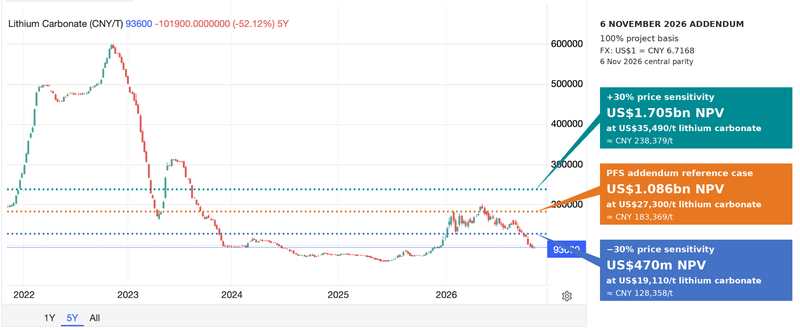
Especially if prices run to ~US$27,300/tonne - which produces that US$1BN+ NPV scenario for the expansion of PUR’s project.
That might seem like a longshot given lithium is at ~US$13,700/t today - but it was sitting at those levels not that long ago (in May 2026).
It’s a volatile commodity to price, and impossible to forecast with much certainty.
Below is how PUR’s project economics would look at different lithium prices - a run to that US$35,000 level would be incredible between now and the end of 2027... no guarantees of course.
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
While we wait for that debt piece to get sorted - PUR is having a crack at the blue sky exploration upside right now
Another way PUR could help get the EcoPro deal (or debt deal) over the line is by growing the size/scale of its project.
And we think that the current drill program PUR is running could grow materially from here (if the current exploration program delivers strong results).
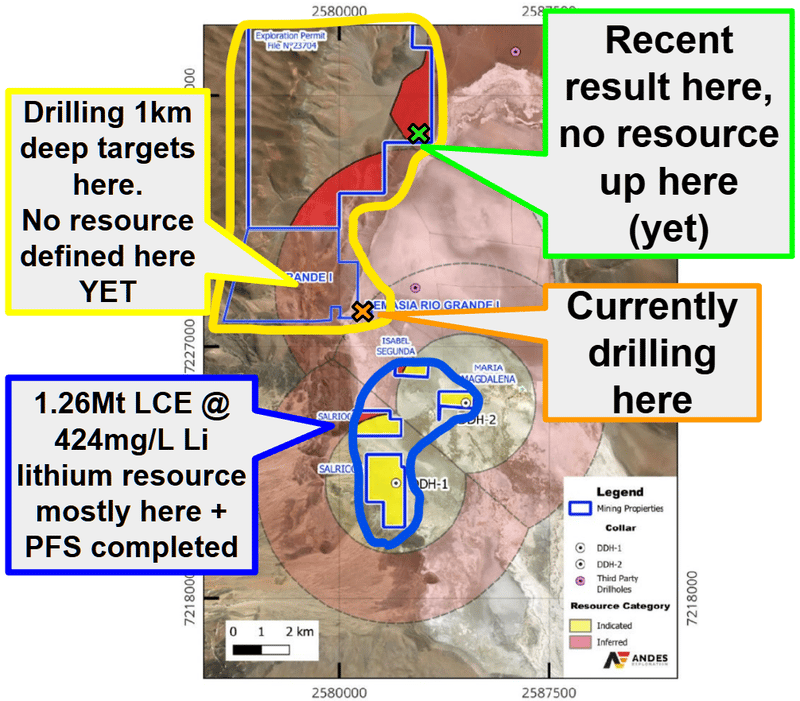
Here is where PUR's existing JORC resource sits:
(source)
The resource - 1.264Mt LCE at 424mg/L - sits in four small tenements in the core of the salt lake.
That’s what the current Pre-Feasibility Study is based on.
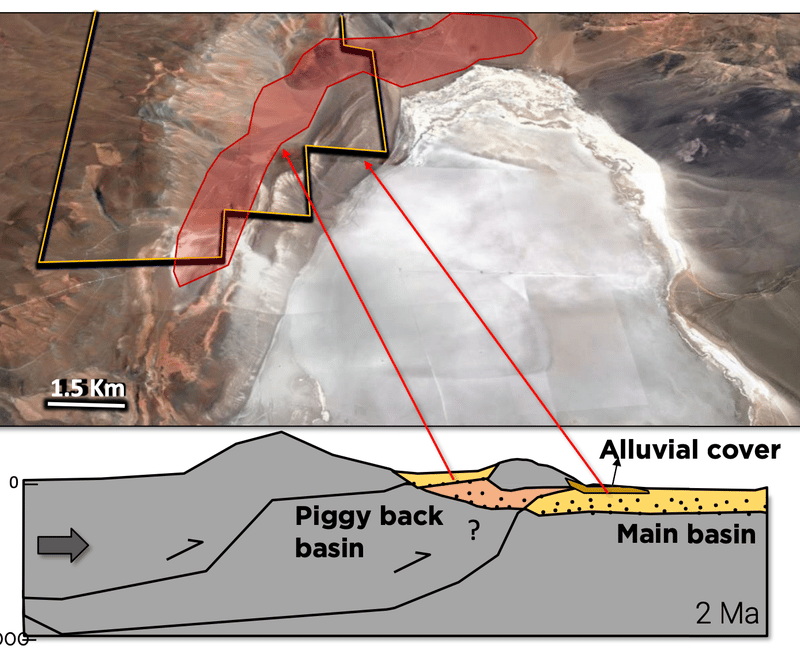
BUT the blue sky exploration upside for PUR has always been based on a theory that the brine reservoirs inside the salt lake extend below ground into the margins.
Here is that theory in visual form:
PUR somewhat validated that theory with geophysical surveys from earlier in the year which showed conductivity down to ~250m to ~1.1km depths and off into the margins of the salt lake:
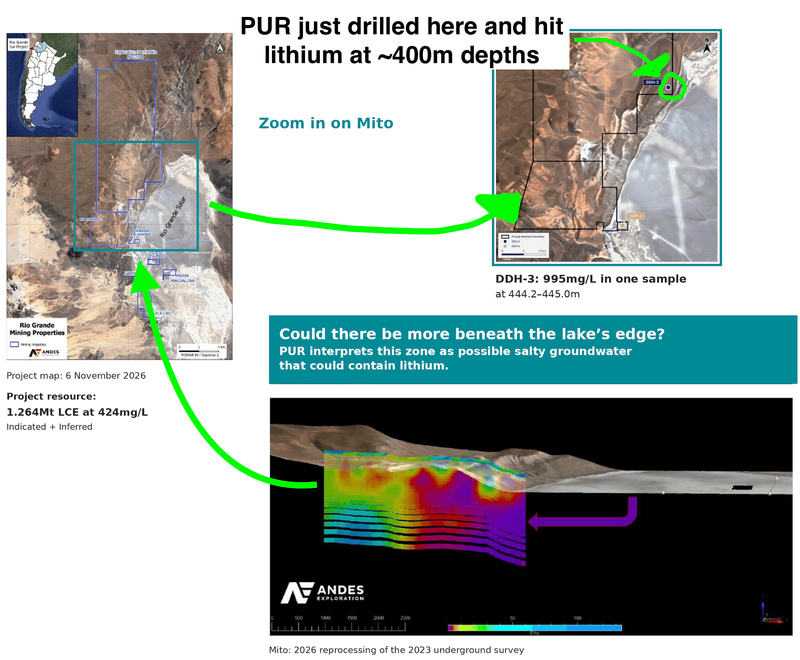
Then from July, PUR put the first hole into those targets and hit a peak grade of 995mg/L lithium and the hole ended in mineralisation at ~560m, so the system remains open at depth.
(Those grades are more than double the average grade of the current resource which is ~424mg/L Li)
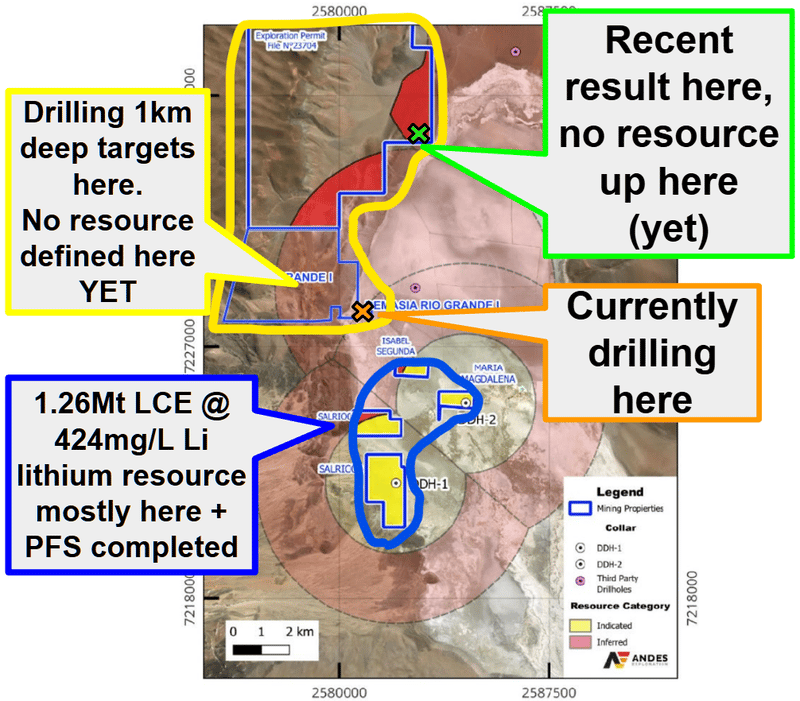
The green X in the image below is where that recent hit came from (north of PUR’s existing resource inside the salt lake):
(source)
Being outside of the current resource - there is a chance PUR’s project grows in size if we keep seeing results similar to those from the green hole located to the north from above.
PUR has now finished its fourth hole at the project, sitting in between last month's results and the current resource area. (source)
IF this hole hits lithium too, it could rapidly expand the area that gets added into the next resource estimate.
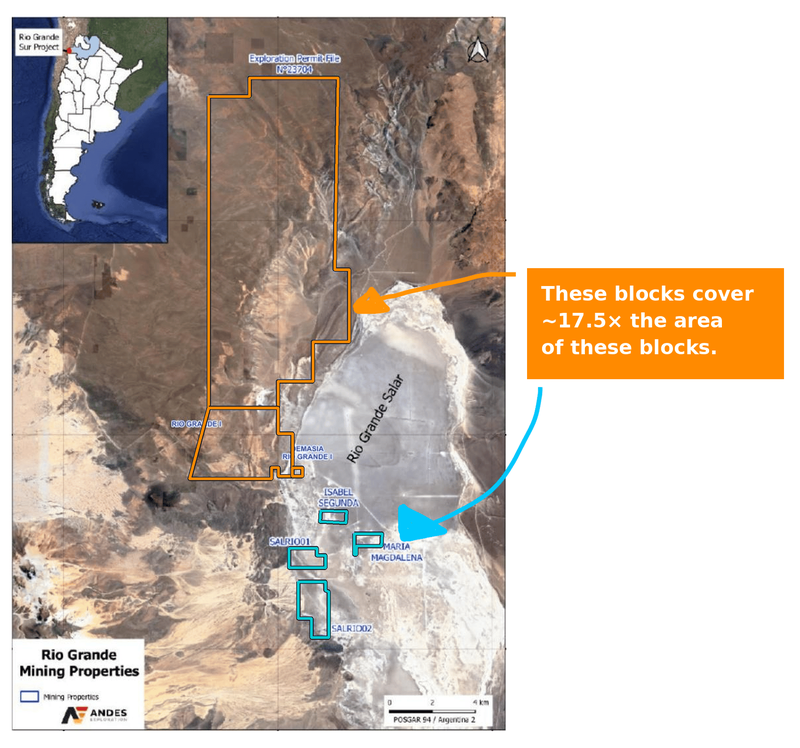
Again, here is the scale of those blocks on the margin versus what PUR has inside the salt lake - that one block to the north is ~15x the area the resource sits in:
(source)
PUR also has a gold-silver project that we like
As mentioned earlier, PUR also has a gold and silver asset.
It's been a rough few months for gold and silver - but we came across these two videos over the weekend and feel good about owning gold and silver stocks again:
(source)
(source)
We are still bullish gold and silver AND last week we saw that the market is willing to reward good drill hits on untested targets too.
Here is how the market’s rewarded our WA gold Investment BPM Minerals (ASX: BPM) which had a strong drill result out from one of its giant untested targets:
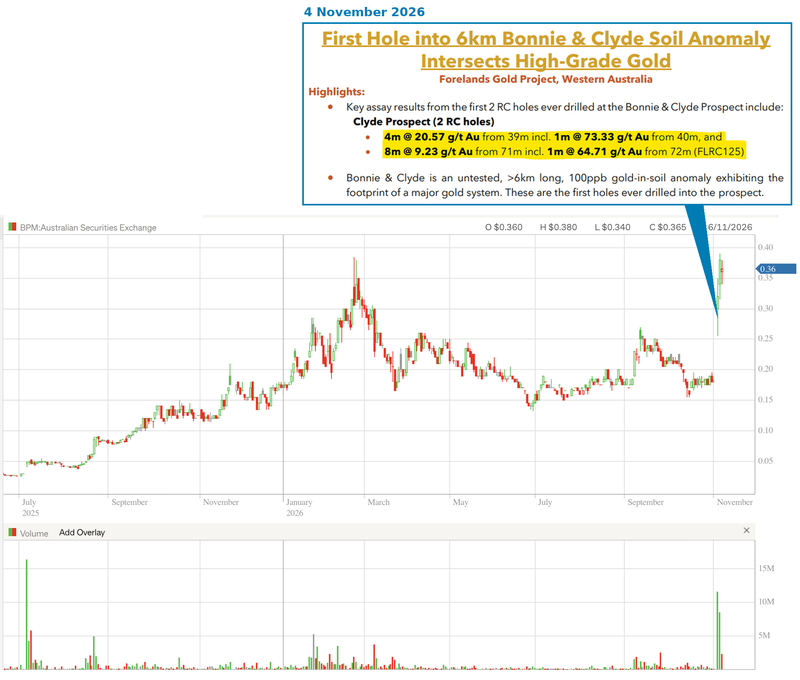
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
We are looking forward to seeing PUR drill its project because we think it's one where the company can make a genuinely material discovery.
PUR’s project sits in the Santa Cruz Province of Argentina, one of the world’s premier precious metals provinces.
This province is host to ~30 million ounces of gold equivalent discoveries.
PUR’s exploration theory is based around a lookalike drill target to where the 8M ounce Cerro Negro deposit was discovered.
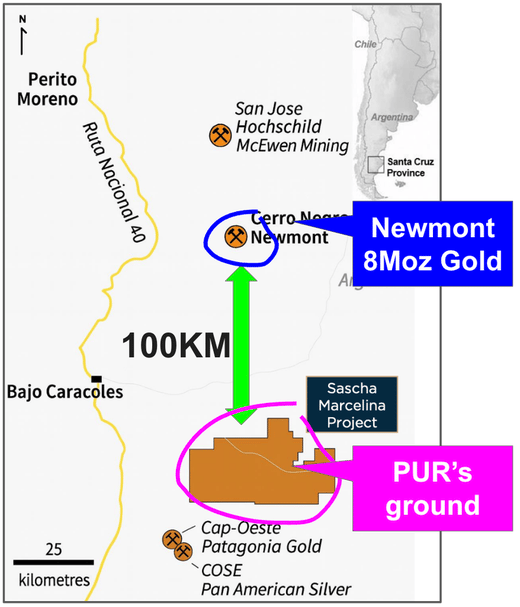
(source)
At the moment we already know the project has:
- A 5.5km mineralised vein corridor, never drilled below ~170m - the best historic hit was ~1.55m at 8.92g/t gold, AND
- An 11km2 silica cap with IP geophysics showing chargeability and resistivity anomalies underneath it - the "Cerro Negro playbook" target.
The silica cap is the “Cerro Negro” look alike.
All the ingredients are there: structure, mineralisation, geophysics, and geochemistry...
Now we just need to see PUR drill and validate if the theory is correct.
With the gold-silver asset we are backing PUR’s Chairman Tom Eadie.
Tom is the Chairman of another ASX listed gold company Southern Cross Gold.
Southern Cross, for a long time, was misunderstood by the market because of the type of deposit the company had...
However, Southern Cross has gone from $3.80 to $8.59/share and a $2.24BN market cap under Tom Eadie’s stewardship.
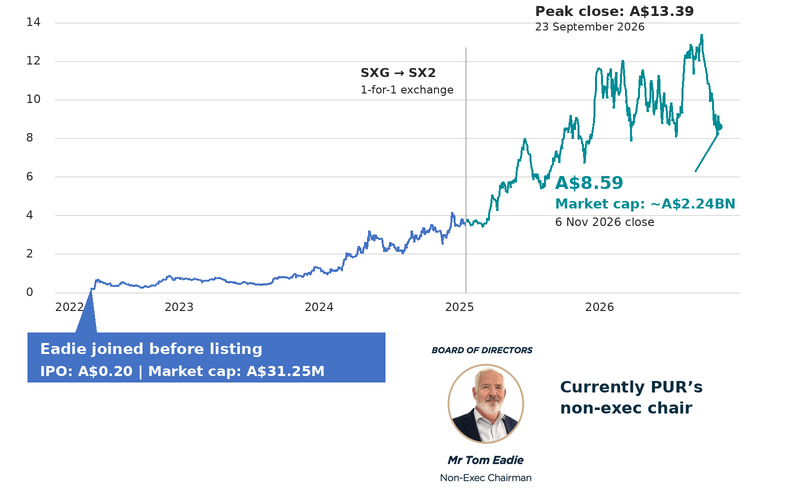
Both Southern Cross and Cerro Negro are high grade gold assets across multiple thin veins...
... similar to what PUR is looking for on this new asset - and naturally, PUR will be applying the same geological model and exploration strategy that unlocked those finds.
Previous drilling on PUR’s project only went down to 170m.
PUR’s theory is that if it drills down to 150-400m it could make a giant gold discovery that was previously missed because of the shallower silica cap that sits on top of the gold mineralisation.
This is exactly how the 8 million ounce, Newmont owned, Cerro Negro was discovered...
PUR plans to drill test the veins marked with a (?) on the map below and soil sample, channel sample and follow up previous hits:
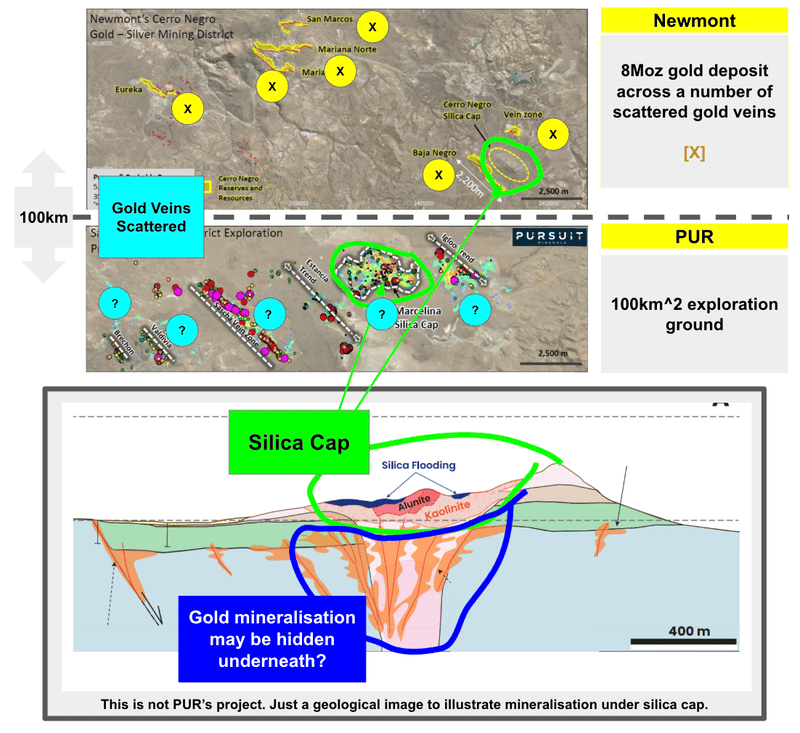
PUR already has permits in for drilling - so drilling could happen whenever PUR has the cash/rig ready for it...
This is high-risk, high-reward exploration from PUR.
They might not find anything valuable.
Or one good drill hit could unlock the entire project and be a company maker.
Ultimately, a discovery on the gold-silver project OR progress on the lithium project (into development) is what we want to see for PUR to achieve our Big Bet, as follows:
Our PUR Big Bet:
“PUR discovers and defines a large resource, leading to a long term re-rate in the company’s share price by >1,000%”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including funding risk/dilution risk, commodity price risk and delay risk - just some of which we list in our PUR Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What's next for PUR?
After today's announcement the main things we want to see are the DDH-4 assays, and the pilot plant getting set up on site so EcoPro can start qualifying PUR's product.
🔄 Progress lithium project in Argentina
Ultimately, we want to see PUR develop this project.
Here are the catalysts we are hoping to see PUR deliver in the short-medium term:
- 🔄 Assay results from hole #4 (currently in the lab)
- 🔄 Pilot plant relocation to site, then commissioning approvals
- 🔄 Commercial evaporation pond approval (application lodged)
- 🔲 Updated JORC resource incorporating recent two holes (hole #3 and hole #4)
- 🔲 Product samples to EcoPro for qualification
- 🔲 Project debt (up to US$120M)
- 🔲 Definitive agreements with EcoPro (conditions deadline 31-Dec-2027)
🔲 Maiden drill program at gold-silver project in Argentina
We also want to see PUR drill this project.
Here are the catalysts we are tracking across this project:
- ✅ Geological mapping - five targets defined
- ✅ IP survey - 8-hole, 3,350m program designed
- 🔲 Rig mobilisation and drilling commences
- 🔲 First assays from Sascha and Marcelina
What could go wrong?
In the short term the two key risks for PUR will be "deal completion risk” and “financing risk”.
The MoU with EcoPro is currently non-binding.
For the deal to complete, PUR needs to meet the following conditions:
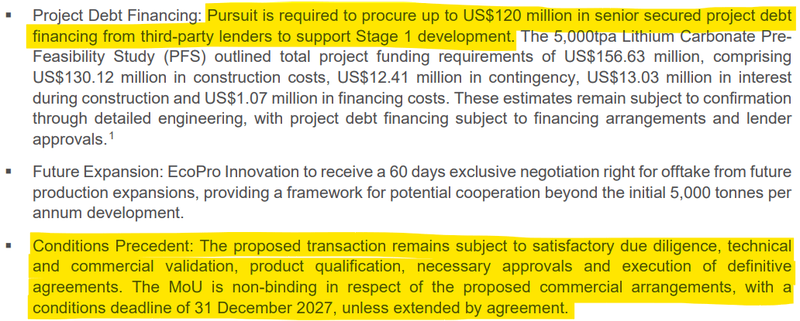
(source)
The deadline for all of these is 31 December 2027.
EcoPro also has time to complete due diligence - so there is a real risk the deal never completes and in that scenario we would think that any move higher from the last traded price could reverse.
We also know that PUR had just ~$760K cash in the bank at September 30.
That will mean PUR is likely going to have to raise capital in the short-term (given it is pre-revenue).
Depending on the market reaction to today’s deal, the raise could require a discount to PUR’s last traded price.
PUR’s cash balance could also be a bit of a deterrent to institutional on-market buying today as anyone who likes the announcement might think “we can just build a position in the upcoming capital raise”.
So we are conscious that the financing risk could dampen the market response to today’s news.
Other risks
Like any small-cap exploration and development company, PUR carries significant risk, here we aim to identify a few more risks.
PUR’s updated PFS is based on a US$27,300/t reference price - roughly double today's spot price of ~US$13,700/t.
At current lithium prices PUR’s project may not have an NPV high enough to justify the CAPEX to bring it into production.
The PFS targets a construction start in January 2027, the project still needs commercial approvals, up to US$120M in project debt and a Definitive Feasibility Study.
Any slippage delivering any of those milestones could delay first production and add to costs.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
PUR Investment Memo
You can read our PUR Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
Our PUR Investment Memo covers:
- What does PUR do?
- The macro theme for PUR
- Our PUR Big Bet
- What we want to see PUR achieve
- Why we are Invested in PUR
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.