WCE: 77% confidence in Australia’s highest grade silver resource
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 3,816,833 WCE Shares at the time of publishing this article. The Company has been engaged by WCE to share our commentary on the progress of our Investment in WCE over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
The silver price is above US$50/oz!
If I had said that anytime over the last few hundred years, silver bulls would have been cracking out the champagne and caviar.
Silver only went above $50 for the first time EVER about 12 months ago.
AND it has stayed above $50 since.
However silver stocks have been sold off in recent months...
(mainly because the market got over excited after silver touched US$120 in January - which has changed the narrative from “OMG silver went UP to $50” to “OMG silver went DOWN to $50”)
Our Investment West Coast Silver (ASX:WCE) holds 70% of the Elizabeth Hill silver project in WA.
WCE is currently capped at $22M, and had over $5.6M cash at September 30th.
WCE’s Elizabeth Hill silver project was one of Australia’s highest grade silver mines when in production.
It spat out 16,830t of ore at ~2,194g/t average grade delivering 1.19 million ounces of silver.
Including the below giant silver nugget:
“The Karratha Queen”.
When a singular nugget gets its own name and a display cabinet at the Perth Mint, you know it’s pretty epic:
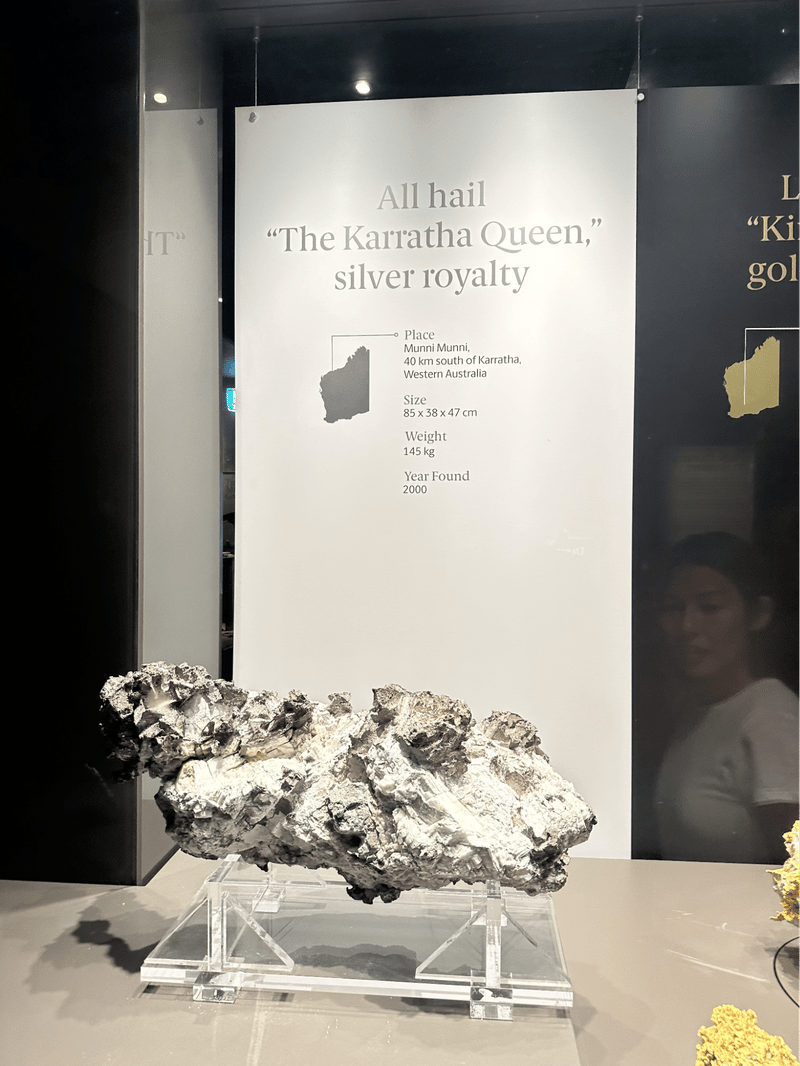
(Source: our photo from the Perth Mint of the largest Australian native silver nugget in existence - this came from WCE’s current ground)
Mining at WCE’s project stopped in the year 2000 when silver dropped to US$5 per ounce. (source)
As we said above, for the last 12 months silver has traded above US$50 an ounce.
WCE has recently been drilling enough holes to prove there are still economic quantities of silver there AND recommence high grade silver mining as quickly as possible.
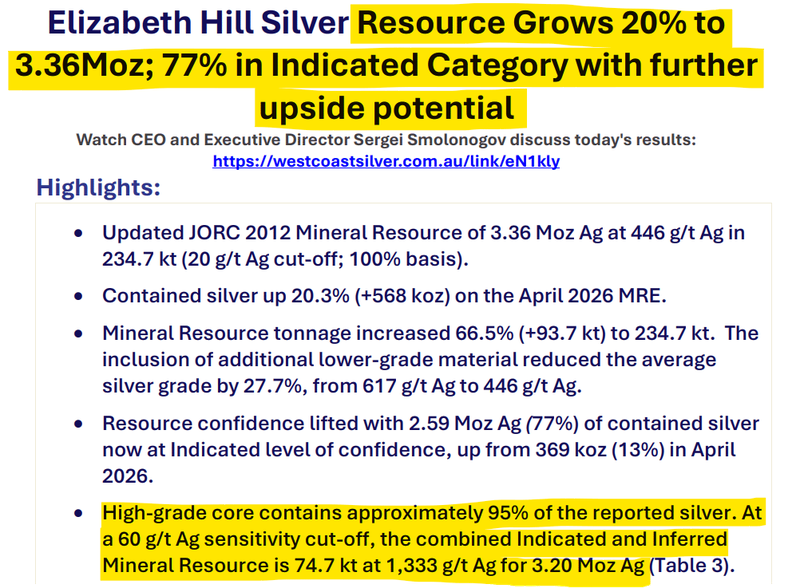
Today WCE announced 77% of its silver resource has moved from the inferred to indicated category.
Now WCE has 3.36M ounces of silver at 446 g/tonne, and much higher resource confidence levels.
Companies like WCE drill holes into the ground and bring up rock samples to test how much valuable minerals they contain.
Each hole only tells you specifically about the rock it passes through - so geologists have to estimate and interpret what’s between the holes.
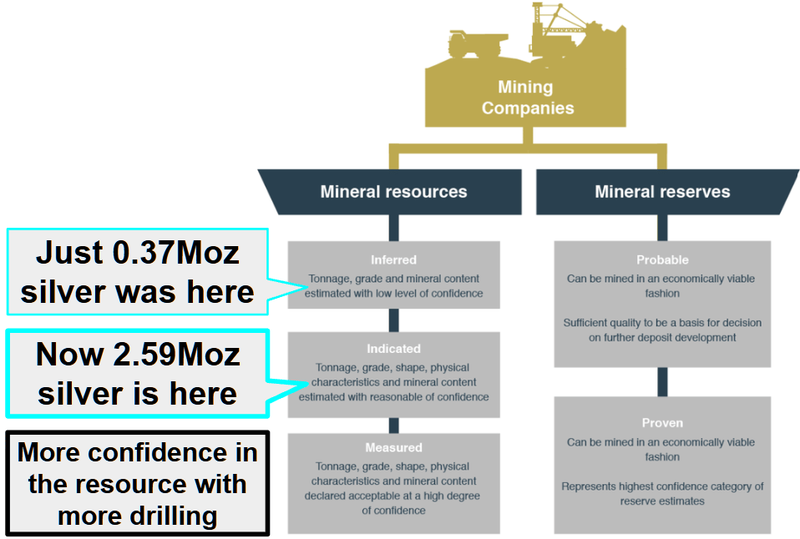
An inferred resource is an estimate based on limited drilling, with considerable uncertainty about how much mineral is there and how consistently it’s spread through the rock.
An indicated resource means there is stronger evidence of the resource size - usually from more closely spaced drilling. Geologists are more confident in the amount and quality of what’s underground.
Yeah OK so who cares about a resource being “indicated” instead of “inferred”?
Serious institutional investors, fund managers and processing plants that can take mined silver ore and extract and sell the silver (and share the profits with WCE).
“Call me when you have an indicated resource.”
An indicated resource unlocks:
- Scoping study - a first look at project economics and development options. WCE has commenced baseline studies, we expect completion of the Scoping Study in the first months of next year.
- Potential toll treatment deals - this is where WCE, as the owner of raw ore can pay another company - which owns an established processing mill or plant - a fee (or "toll", get it?) to crush, grind, and process their ore into a valuable concentrate or doré bar. Toll treaters want to know how confident you are in the resource you have.
- Getting taken more seriously by instituational investors - which could accelerate the funding of WCE’s development plans.
All important stuff if WCE wants to start making money from its silver project while silver prices are high.
It’s been mined before...
Elizabeth Hill isn’t a deposit and mine that has existed only in a computer model showing some drilling lines, bright colours for the assays, and some mock ups of what a mine would look like.
It has actually produced silver before.
That history is part of what attracted us to the project.
A known silver system, historical production and a granted mining lease, in a more bullish environment for silver gives WCE a useful starting point for assessing getting this back into production.
And now a higher confidence of how much silver is in the ground.
WCE is also drilling blue sky extensions to the north west of the mineralised system and deeper.
Today: What changed in WCE’s silver resource?
WCE upgraded its JORC Resource Estimate to 3.36 million ounces of silver.
That is near surface with a conceptual open pit shell, on a mining lease, in WA, just 45km from a large regional mining hub.
So not stranded in the middle of nowhere.
Today’s upgrades deliver a 20.3% increase in the silver resource, adding 568,000 ounces to the estimate from April.
WCE is also targeting another update to the resource in March 2027.
(source)
But the number we think will fly under the radar to most and the same number we are paying closest attention to today, is that 77% figure.
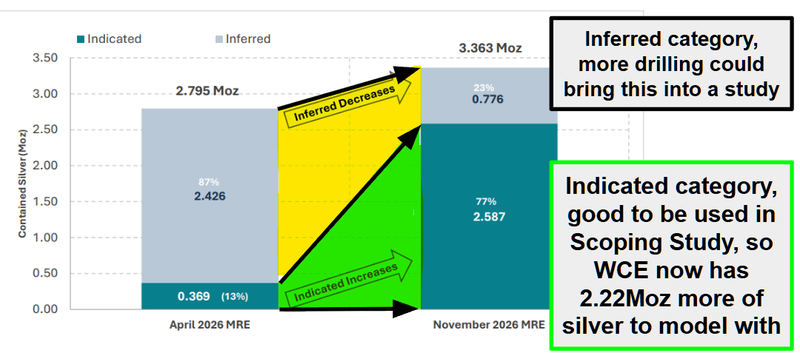
That’s how much of the contained silver now sits in the higher-confidence Indicated category.
Back in April when WCE announced the Maiden JORC Resource Estimate, it was just 13%.
Indicated silver has increased from 369,000 ounces to a more workable 2.587 million ounces, roughly seven times as much:
(source)
Of course that doesn’t mean WCE has found seven times more silver.
What it does mean is that there is more confidence and trust in its silver deposit, so WCE can now put together a Scoping Study which is the first analysis of how they can start mining this silver.
Including estimating how much it might cost to mine it - it's important to have a higher confidence, indicated resource to do this study.
... otherwise it's sorta like buying tickets to the Grand Final for your sports team at the start of the season before you even know they will get into the Grand Final... yes you can do it but it's better to do it when you have higher confidence they will get in.
(And yes this is early stage resource exploration and development, there are risks and so there is always a potential “wharfie time” that can happen even if they DO make it to the Grand Final.)
The updated resource gives the WCE study team a better-supported starting point for assessing how Elizabeth Hill could be mined and processed, and what a potential development might cost.
(source - our article on JORC resources)
On that, metallurgical, geotechnical and engineering work has already started so the study is advancing and previously WCE had guided for Q1 (source) and based on the wording today, appears to be tracking on schedule.
Why the lower cut off grade doesn’t tell the whole story
In a JORC Resource:
Grade means how much valuable metal is in the rock.
Cut-off grade is the minimum concentration used to decide which rock gets counted in a reported resource, based on what could potentially be worth mining
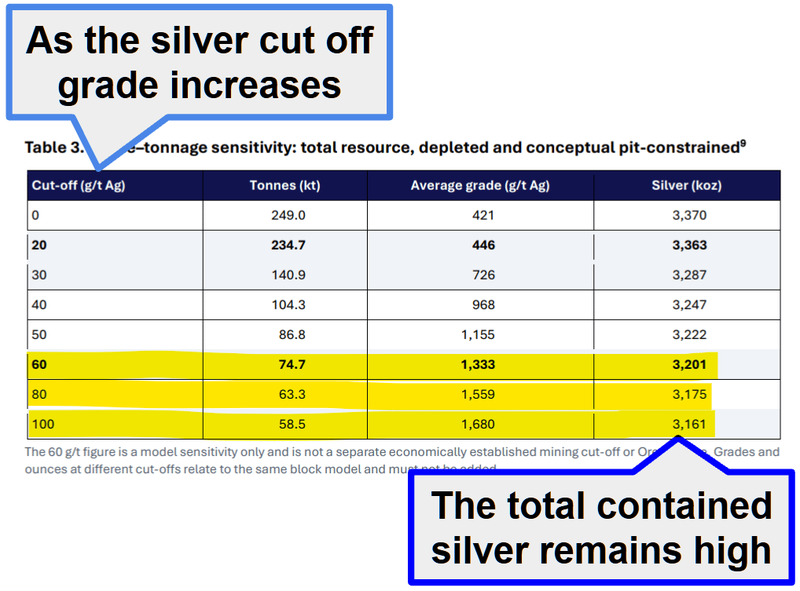
At a 20g/t silver “cut-off”, the updated WCE resource estimate contains 234,700 tonnes at 446g/t for 3.363Moz of silver.
(so basically the resource calculation is ignoring anything below 20g/t silver)
Tonnes are up 66.5% from April, while average grade is down 27.7% as lower-grade material enters the model.
Raise the cut-off to 60g/t in the same model and it still contains 3.201Moz, in 74,700 tonnes grading 1,333g/t:
(source)
In other words, around 95% of the silver sits in just 32% of those tonnes from the headline number.
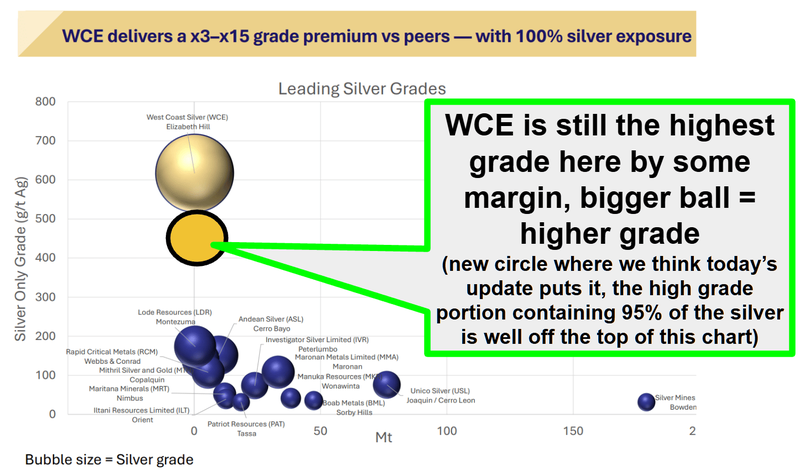
Even with this drop in grade to include more ore, the average grade still puts the project comfortably as the highest grade on the ASX, WCE had included this graphic prior which we have amended:
(source)
That helps explain why the average grade can fall as lower-grade tonnes enter the estimate (the high-grade centre is still there).
It also gives the engineers something useful to investigate: exactly how that concentration of silver might affect potential mining and processing options from a cashflow perspective.
It may make sense to dig through an area that’s profitable to process and stockpile it for later at surface, to get to the higher grade zone.
But this is a sensitivity within the same resource model, not a second resource to add to the headline number. It isn’t proof that WCE can selectively mine those tonnes, recover the assumed silver or do so profitably.
For us, the next question is what the study team can do with that larger, better-defined resource.
Drilling is continuing. The north-west extension is already included as Inferred material, while Elizabeth Hill Deeps remains outside this resource. More on that deeper target below.
WCE is targeting a further resource update in March 2027 and a subsequent Scoping Study, subject to drilling results and technical assessment.
So based on that, it would appear WCE is planning to have all of the technical work done in Q1 next year, with the Scoping Study to follow shortly after.
Not bad to go from project acquisition (24 March 2025) to a Scoping Study two years later.
There are two big items to follow from here:
How much more of the silver system can WCE define with further drilling?
AND
What does the technical work say about mining those ounces in the model?
A reminder that the resource figures above are on a 100% project basis as WCE owns 70% of Elizabeth Hill and funds joint venture expenditure until a Decision to Mine, when the 30% holder Alien Metals can choose to contribute or convert its 30% into a 2% NSR royalty. (source)
What has been going on with the silver price?
Silver is trading at above US$50 per ounce - the highest it has ever been (aside from the spike to and pull back from $120 in January this year).
The reason for the tepid silver sentiment is because it had run to almost $120 in Jan this year before settling back to where it is now.
The run up was glorious, but the price discovery and trend back down has pulled the heat out of silver sentiment.
We remain silver bulls and are maintaining our silver positions for another and bigger rally...
But we recognise the risks here - another rally isn’t guaranteed or it may take much longer than we hope.
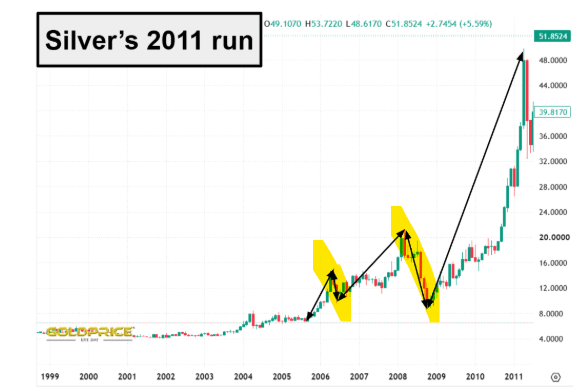
Pullbacks like the one we are in now have interrupted silver rallies in the past too.
Check out the two pull backs during the last silver mega bull run:
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
A year-on-year comparison can hide a rough ride along the way:
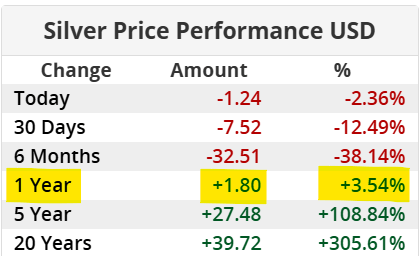
(source)
Over the past 12 months, silver is actually up a few %, but it sure doesn’t feel like it, even though it feels like all of the silver stocks are worse off than 12 months ago.
Sentiment has waned from the 2025 heat, but the annual performance doesn’t indicate this, arguably there is better value now than 12 months ago, but at the end of the day it’s what happens next that matters.
We Invested in WCE to ideally see it start producing silver when (if...) the next rally in the silver price has commenced.
For WCE, the useful question is how the potential mining and processing options perform across a range of silver prices.
IF silver strengthens again, we’d like to think WCE will be further along in understanding its project, rather than only getting back to work once sentiment improves.
WCE is still well cashed up with ~$5.63M in the bank as of September 30, with ~$80k cash in tranche 2 from the prior raise pending.
What options does WCE have to process the ore?
One part of the development case is where the silver would be processed.
Elizabeth Hill is approximately 12km from the Radio Hill processing facility.
WCE’s October presentation listed third-party processing, including Radio Hill, alongside toll treatment and owner-processing options for assessment:
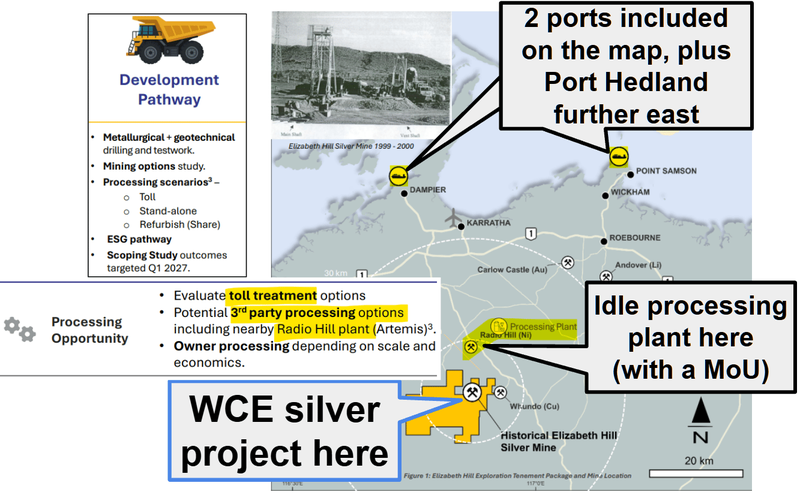
(source)
We’d also be interested to hear whether any off-site processing route beyond Radio Hill is worth assessing, the graphic does label 2 ports and the grade here is high, just maybe an option.
IF an existing facility can treat the material on workable financial terms, that could reduce what WCE needs to build itself.
That is an opportunity worth investigating for a relatively small, high-grade deposit.
The testwork still needs to establish a suitable processing route and recoveries plus find a plant with capacity, plant modifications, transport costs and commercial terms etc to factor in.
Today’s announcement identifies representative metallurgical testing and mining and processing option studies among the next steps, including capital and operating cost evaluation.
Those are the numbers we want to see next.
Not just how much silver is in the ground, but how much can be recovered, what it costs to do it and how much capital is needed before revenue begins.
Auric has shown us what this can look like
A deposit doesn’t always need to support a brand-new processing plant before it can generate cash.
We’ve seen that with Auric Mining in WA.
Auric developed its Jeffreys Find gold project through a 50/50 joint venture with mining contractor BML Ventures, using third-party processing infrastructure.
BML funded and managed the mining, haulage, processing and associated operating costs. After gold sales and direct costs, the surplus cash was split equally between the partners. (source)
By March 2026, Auric reported that it had received approximately $16.5M in total cash distributions from Jeffreys Find, against an initial cash investment of just $1.2M. (source)
That $1.2M was Auric’s reported initial cash investment to be able to get things moving, not the total cost of developing and running the mine.
Jeffreys Find’s cash distributions helped fund Auric’s next project, Munda. (source)
A relatively small mining operation had helped fund it being able to take the next step.
Auric Mining was capped at just ~$6M in March 2023.
AND has since produced ~35-40k ounces of gold all using third party processing infrastructure.
Auric now has a market cap of ~$46M and has ~$33M cash at 30 September 2026. (source)
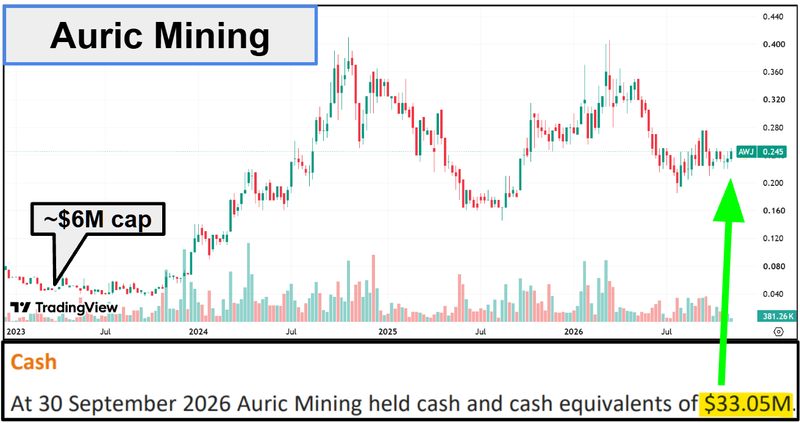
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
That’s why we want WCE to test whether an existing plant could offer a workable first processing route for Elizabeth Hill.
Auric is now pursuing its own Burbanks facility, so its processing strategy is evolving. (source)
The comparison shows a possible development route, not economics WCE can copy: gold and silver projects have different recoveries, costs and commercial terms.
How much more drilling potential is there at and beyond Elizabeth Hill?
We love a good “worm watch”, seeing if an early hit or two actually turns into something bigger and more substantive.
(when we say “worm” we mean the growing estimate of underground mineralisation presented visually in what often looks like a long worm - each new drill hole hopefully makes the worm bigger / longer / fatter)
Back in July we had exactly this, so we are looking forward to seeing WCE releasing some follow up results from here.
This is what it looked like when that assay dropped back in July:
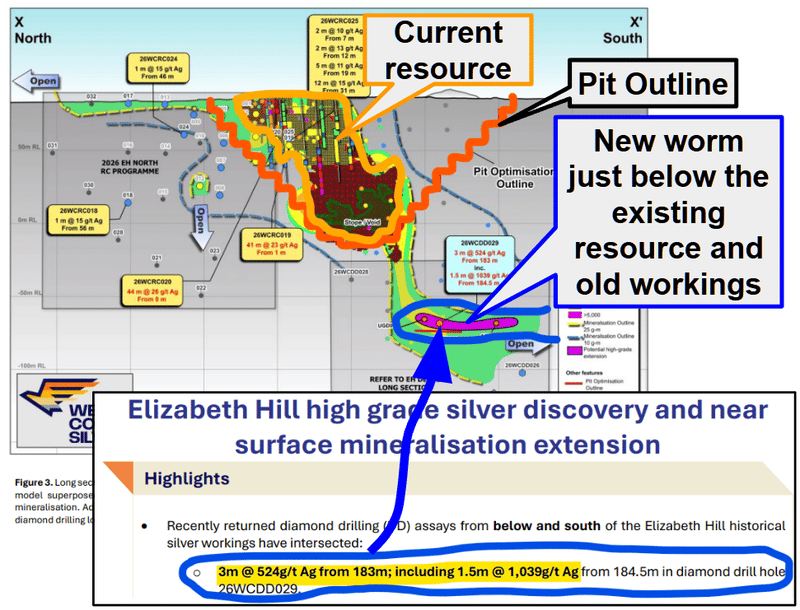
(source)
And a bit of a projection of what it could look like in today’s announcement:
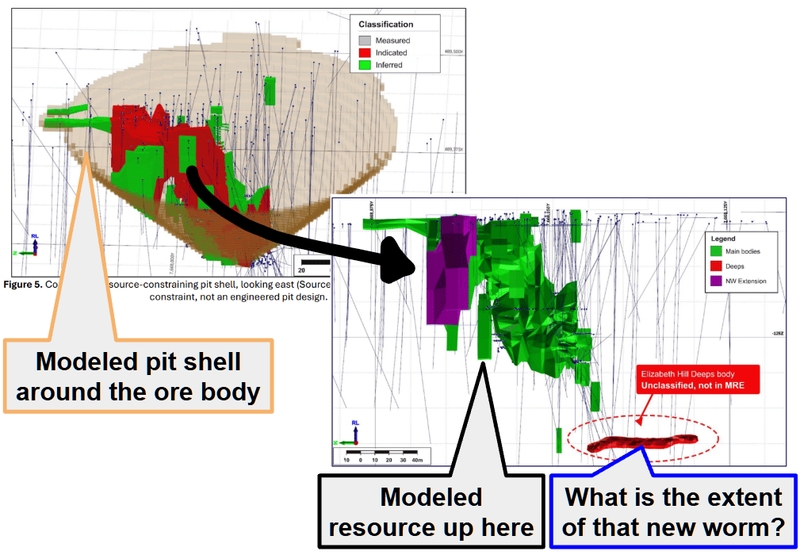
(source)
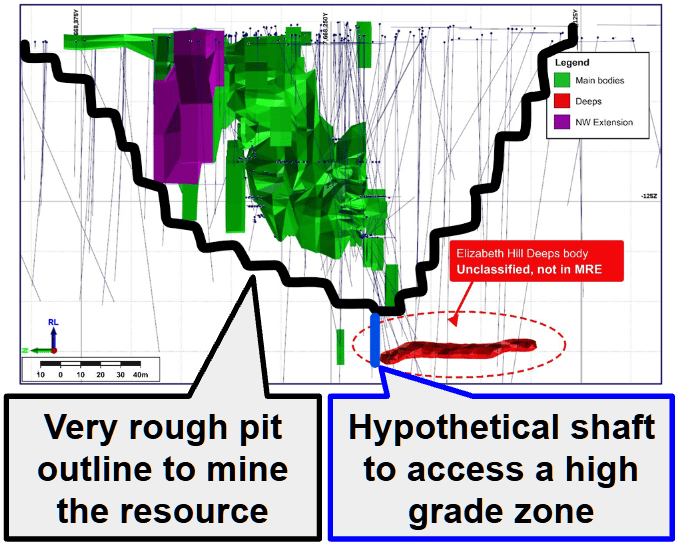
(source)
All we need to see now is more drilling around that area so that “bright purple worm” that represents the inferred high grade silver mineralisation gets longer (and/or fatter) to the point where it becomes too hard to ignore...
This is the overhead view of the current drill program underway:
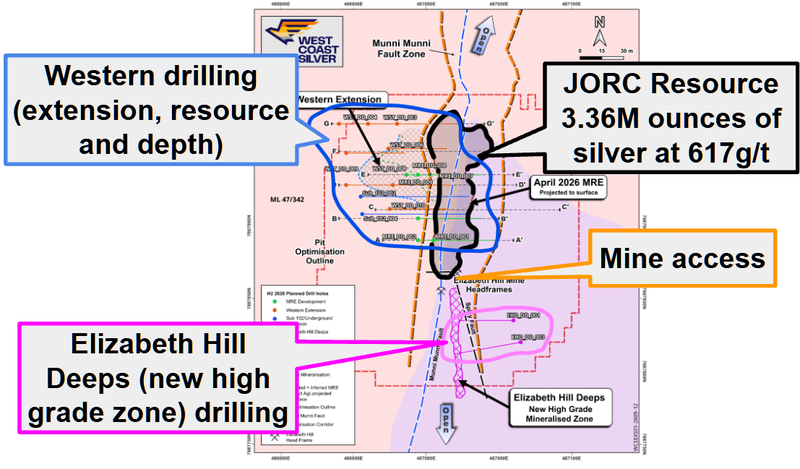
(source)
The work around the existing mine is only one part of WCE’s exploration opportunity.
WCE has consolidated a contiguous land package of approximately 180km2 around Elizabeth Hill, covering a significant part of the Munni Munni Fault system and other prospective faults:
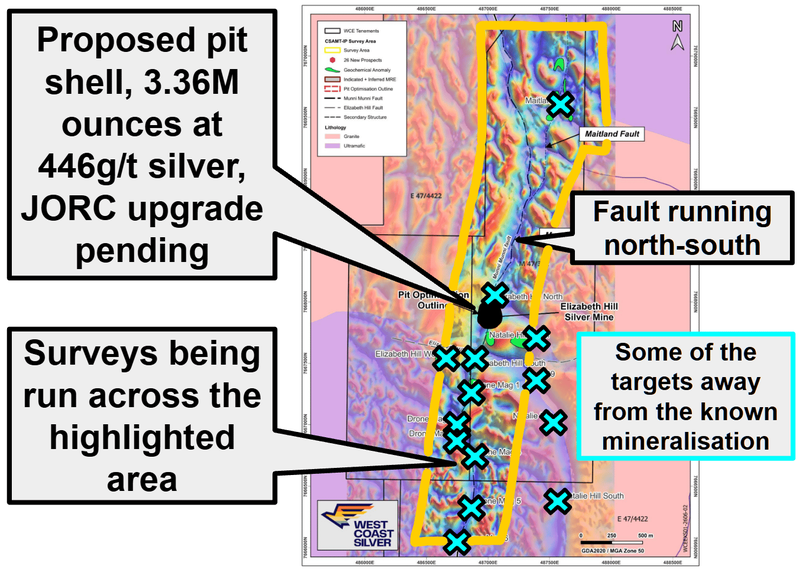
(source)
That gives WCE more ground on which to look for another Elizabeth Hill-style deposit.
Further out, the question is whether similar mineralising systems occur elsewhere along the structures (e.g. faults) that run through the land package.
This is the exploration upside we want WCE to keep testing alongside its development work.
Improve the definition of the existing deposit, assess whether it can be developed, and keep looking for another discovery nearby.
Ultimately, we are Invested in WCE to see it drill out and bring back online its silver project - repeating the types of mining runs done in the past (high grade, low tonnage) BUT this time into a silver market where prices are much higher than before.
Our WCE Big Bet:
“WCE re-rates to a market cap of $300M by bringing the Elizabeth Hill mine back online OR making a new discovery that is as big (if not bigger) than Elizabeth Hill into a strong macro silver theme.”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including exploration risk, commodity price risk and market risk - just some of which we list in our WCE Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What’s next for WCE?
Here is WCE’s latest Gantt chart with what we can expect to see over the coming months from WCE:
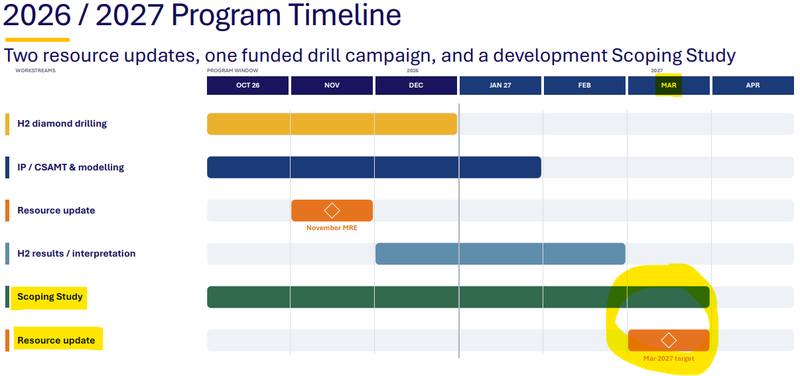
(source - WCE’s latest investor presentation)
So summing up, in terms of exploration the three things we are looking out for are:
- Future drilling to upgrade the resource, including Inferred resources to Indicated.
- Drilling looking for extensions including the deeper high grade 3m at 524g/t silver hit.
- Testing of new targets plus geophysics across the broader project area.
And then all of that data rolling into what we expect to be an updated JORC resource estimate being fed into a Scoping Study, already underway.
Here are the milestones we are tracking right now:
- ✅ Updated mineral resource estimate (released today)
- 🔄 Follow up drilling underway
- 🔄 Scoping study starts
- 🔲 Follow up Mineral Resource Estimate (MRE) (Q1 2027)
- 🔲 Scoping study results (expected after the MRE, ~Q1 2027 - source)
What could go wrong?
In the short term the key risk is around “exploration risk” and “commodity price risk”.
WCE is currently drilling surrounding the historical mine.
There is a risk WCE does not find enough economically viable mineralisation and the company’s share price re-rates lower.
Exploration risk
There is no guarantee that WCE’s upcoming drill programs are successful. WCE may fail to find economic deposits of silver.
Source: What could go wrong? - WCE Investment Memo 8 August 2025.
Right now, the silver price has pulled back significantly from its all time highs earlier in the year.
WCE’s primary commodity exposure is silver, so any further falls in the silver price could mean WCE’s share price moves lower.
Commodity price risk
The performance of commodity stocks are often closely linked to the value of the underlying commodities they are seeking to extract. Should silver prices fall, this could hurt the WCE share price.
Source: What could go wrong? - WCE Investment Memo 8 August 2025.
Other risks
Like any small-cap silver exploration and development company, WCE carries significant risk, here we aim to identify a few more risks.
While 77% of the contained silver now sits in the Indicated category, the resource is not an Ore Reserve and WCE notes it does not demonstrate economic viability. The Scoping Study will be the first test of whether these ounces can be mined profitably.
The pit shell constraining the resource assumes 90% metallurgical recovery, based on recoveries reported by the historical operation. Until modern testwork confirms it, lower recoveries could shrink the pit and the ounces that make it into a mine plan.
The Auric example we reference is a gold project with a different partner, plant and commercial terms. There is no guarantee WCE can secure a similar contractor funded arrangement, or that one would deliver similar cash returns.
WCE is targeting a further resource update in March 2027 ahead of the Scoping Study. Delays in drilling, assays or testwork could push both milestones back, at a time when silver sentiment is already weak.
With ~$5.63M cash at 30 September and drilling, geophysics and studies running at once, WCE is funded for its near term work but will likely need more capital to reach a development decision, which could dilute existing shareholders.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our WCE Investment Memo
In our WCE Investment Memo, you can find the following:
- What does WCE do?
- The macro theme for WCE
- Our WCE Big Bet
- What we want to see WCE achieve
- Why we are Invested in WCE
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.