IVR: That’s a huge pit
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 10,676,928 IVR Shares at the time of publishing this article. The Company has been engaged by IVR to share our commentary on the progress of our Investment in IVR over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
Silver up over 3% on Friday?
We’ll take it.
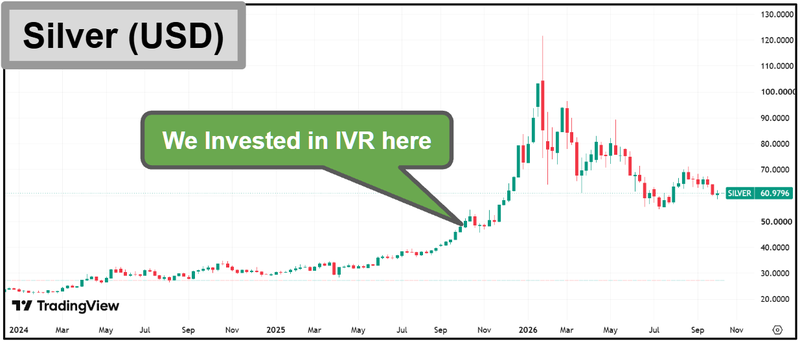
After our favourite precious metal spiked to $120/oz in in January this year, silver has continued to trade well above its two previous all time highs for all of 2026:
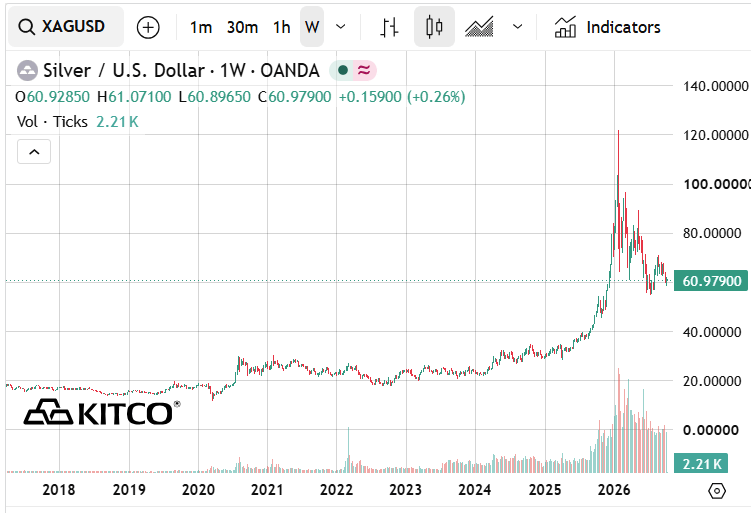
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Earlier this year we wrote about how every major silver bull market came with a 45% to 50% pull back in the middle:
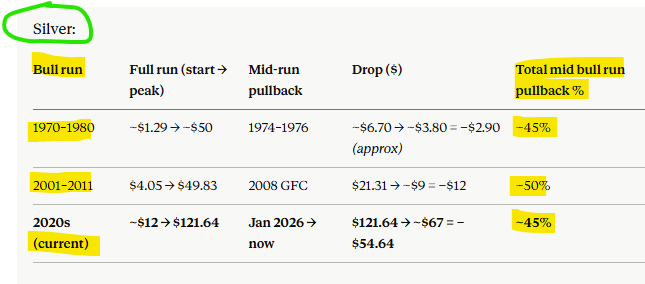
(source: our article from June 2026)
We are holding our silver positions, waiting for the next major leg up in the silver price.
And when silver goes up it should take silver stocks with it - especially the ones closest to building a mine.
We Invested in Investigator Silver (ASX:IVR) because we think its project could be one of the mines that end up being built in this cycle.
IVR has an advanced stage 57M ounce silver deposit in South Australia. (source)
It’s one of Australia's highest grade pure play silver projects.
The project has a Definitive Feasibility Study (delivered in February) that demonstrated:
- A$1.154BN pre-tax NPV and a 93% IRR (at US$80/oz silver - silver is currently trading at US$61/oz),
- An 11 month payback on A$260M of development capital, and
- A$39.70/oz all-in sustaining cost (US$27.39/oz) - well below that current spot price above.
(at the pre-production stage, advanced projects with a real shot at building a mine run first in a bull market for that commodity)
Since our Investment in IVR, fundamentally the silver trade has gotten stronger too.
We have seen:
- Silver move onto the same list as antimony, tungsten and rare earths by China (for export controls).
- The US government add silver to its critical minerals list.
- A confirmed SIXTH straight year of silver deficits (where mined supply is less than demand)
- And then a few months ago Samsung said it would start mass production of a solid-state EV battery that uses a silver-carbon layer in 2027.
So with all of that in the market... WHY isn't the silver price US$200 or US$300/oz?
Anyone who has been around markets for longer than a few years will know that whenever there is a big move into all time highs, there is a pretty quick (and aggressive) pullback that comes with it.
BEFORE finding a base... to launch higher again.
One US fund manager thinks that the next rally comes after the world has shed enough of its above-ground silver inventories (which he thinks could be inside the next 3 years). (source)
Remember... silver is in its SIXTH consecutive year of global silver deficits. (source)
So, once inventories are low enough (or completely gone), the market could react by pushing silver prices up to a level where it incentivises new supply to come online.
We are backing IVR because the MD (Lachlan Wallace) knows how to get a mine built - especially in South Australia.
He was the Managing Director of Hillgrove Resources, where he led the design, permitting, financing and restart of the Kanmantoo copper mine ~55km east of Adelaide.
That was the last mine to come into production in South Australia.
Here he is pictured with the first copper concentrate that came out of the ground in February 2024.
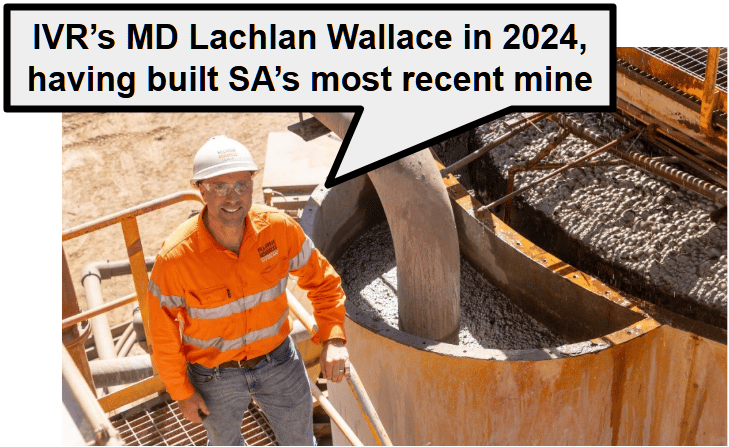
(source)
We are now backing him to do it again with IVR, in the same state, in the same permitting and construction environment - this time with a silver asset.
IVR has played the silver cycle about as well as we could have hoped (so far)
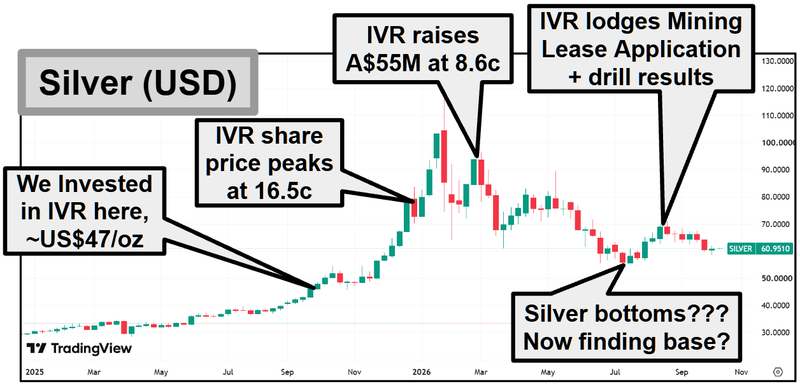
When silver made its first run to ~US$120 per ounce over the new year, IVR's share price ran hard into that rally.
IVR hit 16.5c at its peak in late December - up ~290% from our Initial Entry Price of 4.2c.
(the past performance of IVR is not an indication of the future performance of IVR)
IVR then used that window to raise A$55M at 8.6c (source).
Which meant that while the silver price came off from its ~US$121 peak, IVR with ~A$59M in the bank (at Jun 30) it doesn’t need to think about slowing things down and can go hard at developing its project. (source)
(instead of sitting on its hands restricted by its cash balance, needing to reduce spending to try and make the cash last until the next capital raising window opens up, or be forced to raise at unfavourable terms)
And right now, IVR is trading at just ~4.6c per share - slightly above our Initial Entry Price.
Despite getting that mega raise away at almost double its current share price.
With a bit of luck - IVR can now get all of the boring pre-development work completed (like permitting, civils and pre-construction tenders), so that IF/WHEN the silver price runs again it is in a position to raise whatever funding is needed and start building its project.
No guarantees of course - permitting and financing timelines can and do slip, and IVR is a small cap stock with no revenue from other assets.
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Since our previous IVR Deep Dive back in March, the company has:
- Appointed an engineering partner to take the project from DFS to "construction-ready" (the FEED stage - Front End Engineering Design). (source)
- Hired a build team - a CFO, a Chief Development Officer with 25 years in project financing, two Project Directors, a Principal Mining Engineer and a Senior Exploration Geologist. (source)
- Completed heritage surveys across the full project area, with the Native Title Mining Agreement now in progress. (source)
- Lodged its Mining Lease application with the SA Department for Energy and Mining on 19 August - IVR is targeting completion of the permitting and approvals process during 2027. (source)
- Started a big 30,000m drill program to improve its understanding of the project’s resource - more certainty of what is in the ground is very important for would be mine financiers. (source)(source)
So over the next few months we have drill results AND a lot of the final bits of permitting newsflow to look forward to.
The news the market will show the most interest in will no doubt be the drill results though.
Especially IF IVR can continue delivering hits like the one from a few weeks back.
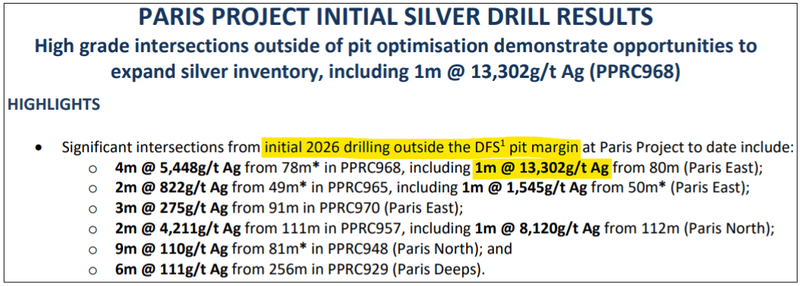
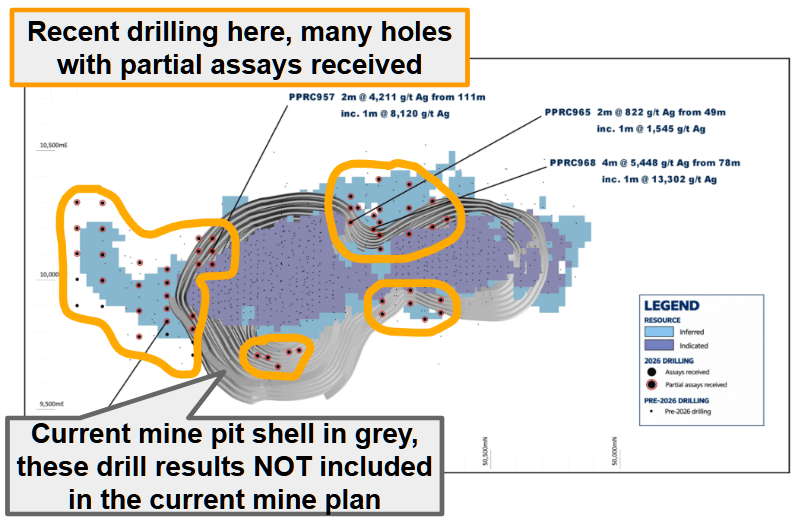
In early September, IVR hit some seriously high silver grades OUTSIDE the current pit design, headlined by 4m at 5,448g/t silver, including one metre at 13,302g/t silver:
(source)
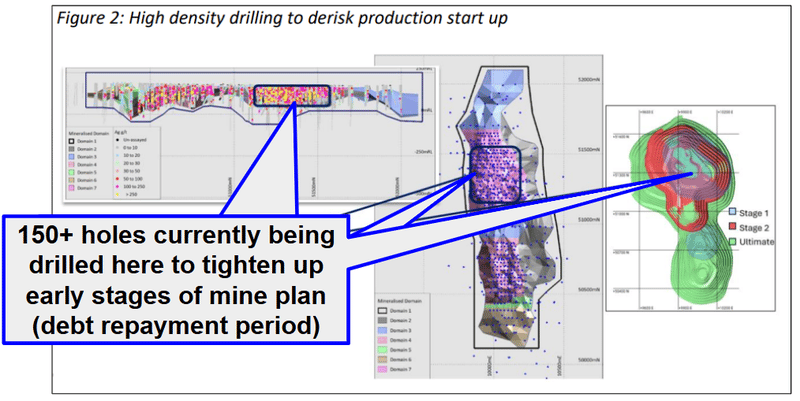
We thought this next batch of drilling would be more about converting IVR's current resource into higher confidence categories.
(from "Indicated" into "Measured" etc - which is what financiers want to see before they lend against a project, and are more willing to fund)
(source)
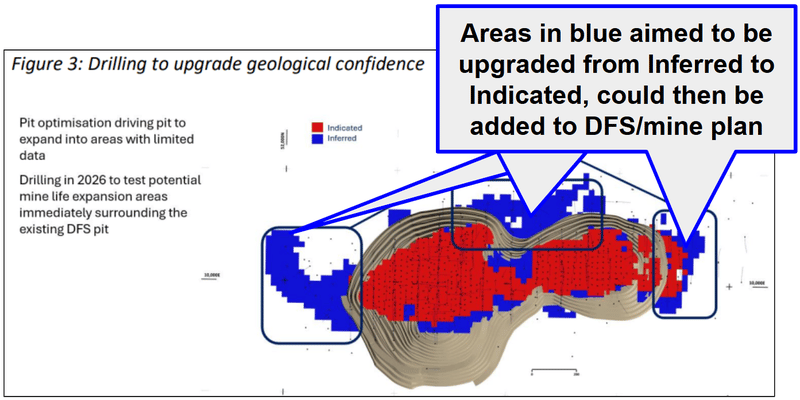
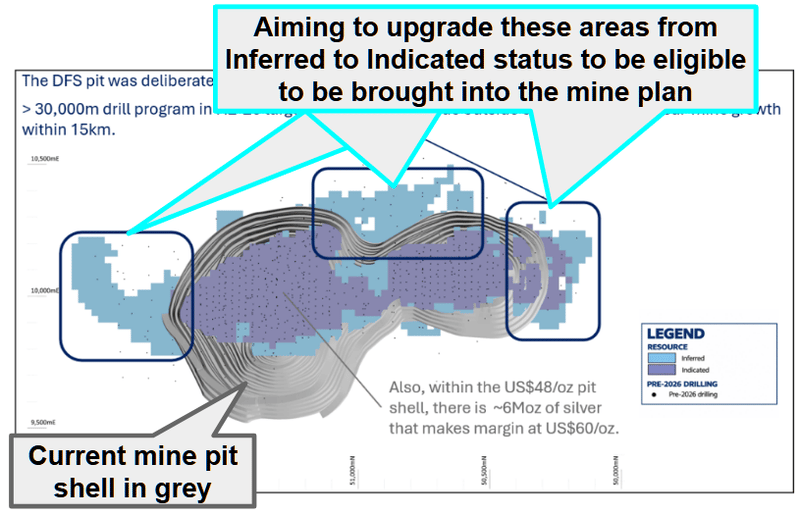
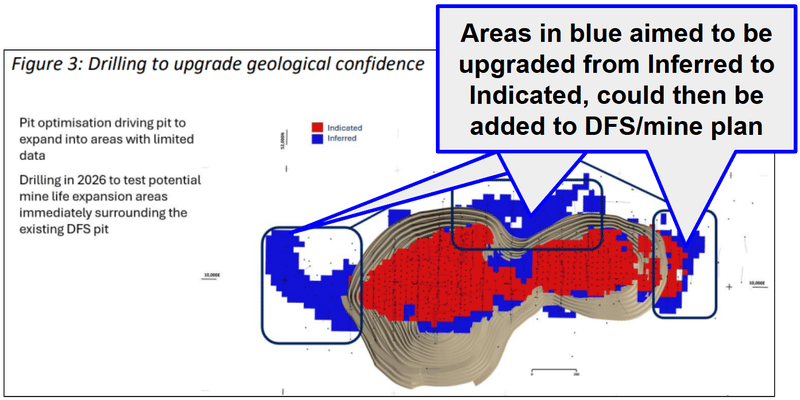
But it seems IVR is now highlighting three different areas around the existing pit that COULD end up coming into its ongoing studies and mine planning:
(source)
We also note there are still more assays to come from that earlier round of drilling outside the current planned pit outline:
(source)
So now, by the end of this current drill program, we could see an expanded pit design, where IVR has added a material amount of silver into its mine plan.
(source)
Remember back in December when IVR "found" an additional 13M ounces of silver to bring into its mine plan, simply by re-running its pit designs at a higher silver price? (source)
An extra 13M ounces added to IVR’s pit designs would bring in ~US$793M of silver into the mine plan...
Obviously that's without considering the cost to extract this in ground silver - so always approach ‘in ground’ numbers with caution.
That extra 13M ounces would also be equivalent to ~23% of IVR's current 57M ounce resource estimate.
None of that silver in the optimised pit shell is in today's DFS.
And NONE of the new drilling results are in the DFS either.
So we think there is still potential to upgrade the silver production profile being modelled in today's DFS, which would make the numbers even more robust.
No guarantees of course.
A quick recap of IVR’s project
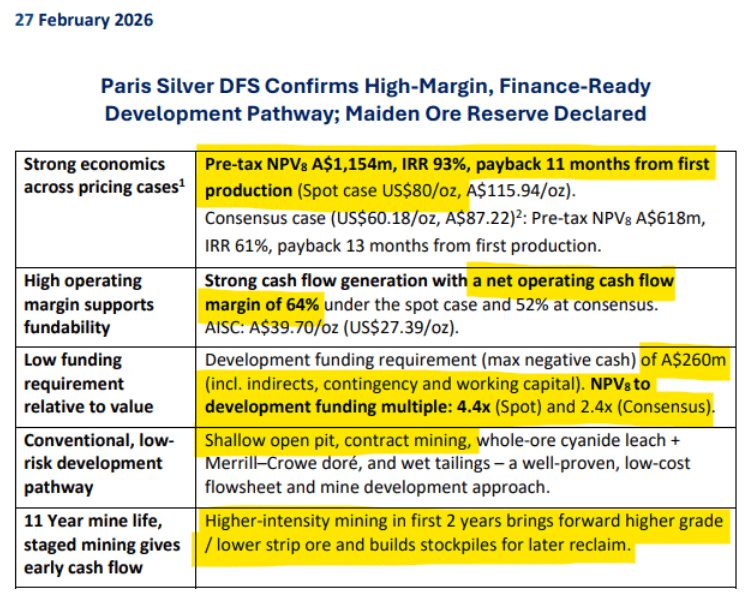
IVR’s project is advanced stage with a Definitive Feasibility Study delivered in Feb which demonstrated:
- A$1.154BN pre-tax Net Present Value (NPV),
- 93% Internal Rate of Return (IRR) and
- An 11 month payback at US$80/oz silver.
- From A$260M CAPEX.
(source)
The key change to that DFS so far has been the silver price assumption used to calculate the project economics.
IVR plugged in a silver price of US$80 per ounce (above today’s silver price).
But even if we plug in US$60 per ounce - the DFS had pre-tax NPV for the project of ~A$618M (and a payback of just ~13 months).
Check out our deep dive into the DFS here.
IVR’s project has a 57M ounce silver JORC resource estimate at an average grade of 73g/t - one of Australia's highest grade pure play silver projects.
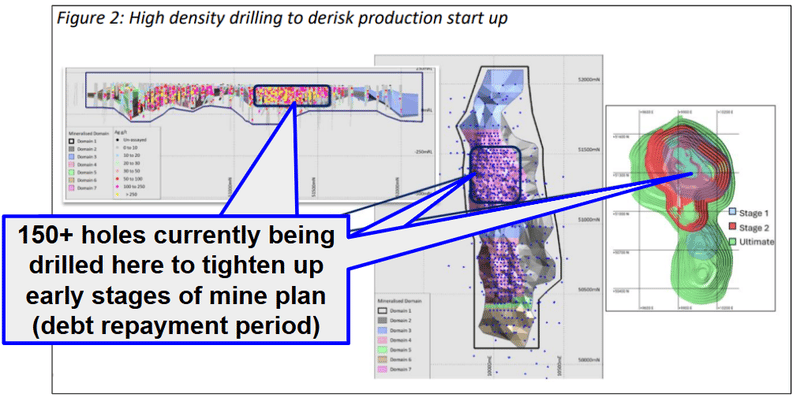
IVR is currently drilling its project to try and open up new areas of its resource that could improve economics early into the project's life.
That drilling at the main project area was focused on two main areas:
1. Grade control / infill drilling - drilling in and around the existing resource to increase confidence in the orebody model (reduces risks for financiers and reduces surprises when mining).
(source)
2. Resource conversion and pit expansion - looking to extend the boundaries of the current mine plan and bring more ounces into the mine plan.
(source)
A couple of months ago IVR started building out the team to construct the project, filling roles including
- CFO,
- Project Directors (x2),
- Principal Mining Engineer, and
- Senior Exploration Geologist.
You can see our coverage on this here.
In the quarterly it was mentioned IVR had also hired Byron Gordon as Chief Development officer, who has previously worked at Export Finance Australia and prior to that Wilsons Advisory (now part of Canaccord Genuity).
So given IVR has made it clear with its current cash reserves and expected financing still required, it would be targeting debt and/or non dilutive funding of which Byron has good experience here.
You can see our coverage on this here.
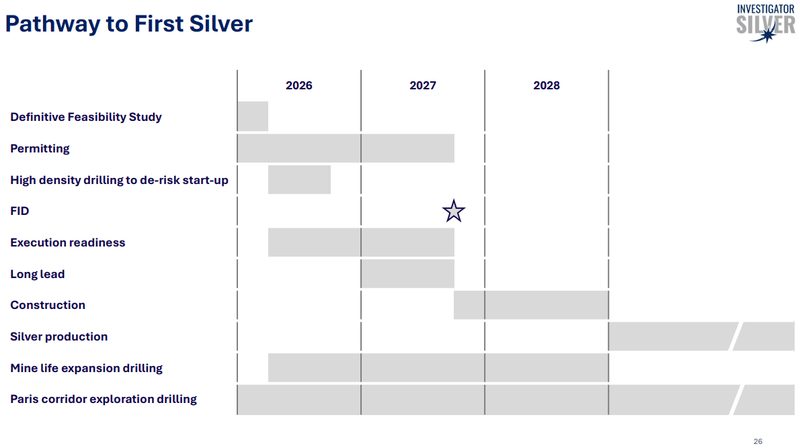
So now, over the next 18 months, while IVR works on permitting and project financing, we will get to see another round of drilling on the project.
Here is the Gantt chart IVR had in the March DFS presentation, with when to expect key milestones to arrive:
(source)
8 reasons why we Invested in IVR
We first Invested in IVR on the 3rd of October 2025.
Here are the 8 reasons why we Invested from that initiation note (we have included updates for anything that has changed since then).
1. IVR has one of the highest-grade silver projects in Australia
IVR’s project has an estimated 57M ounces of silver at an average grade of 73g/t.
That makes it one of the highest grade primary silver deposits in Australia.
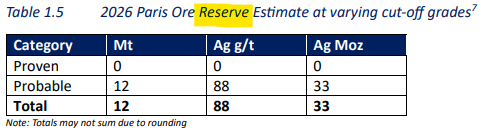
UPDATE: IVR also announced a maiden ore reserve to go with its DFS back in March.
An ore reserve is the highest confidence classification for a resource estimate - usually the “lowest risk” from an estimation point of view.
IVR’s reserves are 12mt at 88g/t silver for 33M ounces of silver.
(source)
2. IVR’s project is at the advanced DFS stage
It is hard enough to go and make a mineral discovery, it is even harder to get a mine into production.
For the DFS stage companies that are in the market during a hot commodity cycle, securing project financing can become a whole lot easier.
We like that IVR is at this DFS stage and it can potentially be one of those companies that ‘survives the cycle’ and becomes a mine during this current silver bull run.
We also think that with a running silver price, IVR’s DFS could surprise the market to the upside in terms of project economics.
UPDATE: In March IVR released the DFS with the following project economics:
- Pre-tax NPV8 of A$1.1BN, 93% IRR, and rapid 11-month payback from first production.
- A$260 million development funding requirement, A$39.70/oz AISC, and a 64% operating margin.
- 33 Moz Maiden Ore Reserve, 11-year mine life, and 30 Moz total silver production in doré.
3. We are investing alongside Jupiter Asset Management
Jupiter Asset Management owned 14% of IVR (before today’s capital raise - that they also went into) and we are following them into the story.
Jupiter is a huge resources fund out of the UK with over £47.1 billion in assets under management.
We have had success investing alongside Jupiter with another silver story Mithril Silver & Gold, which is up 515% from our Initial Entry Price.
Also, Jupiter came into one of our recent silver picks Rapid Critical Metals which is up 111% since our Initial Entry Price.
(past performance is not an indicator of future performance)
Jupiter have been major holders in IVR for years now and have followed their money into IVR’s capital raises - including the most recent one.
UPDATE: IVR confirmed Jupiter Asset Management (who currently manage ~£73.7 billion, source) once again invested in the March funding round.
4. We think silver could go on a ‘once in a generation’ run to new highs
Silver is now at 14 year highs, and we think it's about to go on a “once in a generation” run to new all time highs... taking all silver stocks with it.
(no guarantees, past performance is not a reliable indicator of future performance)
UPDATE: When we Invested in IVR, the silver price was trading at around US$50 per ounce.
Since then, it has run as high as roughly US$125 per ounce and is now trading at ~US$61 per ounce.
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
5. Very few silver stocks on ASX
There are very few silver stocks on the ASX.
Even less ‘pure play’ silver stocks.
If silver runs, there could be a lot of capital chasing silver exposure in only a handful of names.
This scarcity could mean valuations run from where they are now.
6. Exploration upside (three projects that haven’t been systematically drilled)
IVR just did a deal on the ground next door to its 57M ounce JORC resource estimate.
IVR now has a 15km corridor of exploration targets where it can look to make repeat discoveries (similar to its existing deposit).
Drilling so far has shown district scale potential.
7. IVR’s project being designed to work even in the event of a lower silver price
IVR updated its project's resource in 2023 and started working on its Definitive Feasibility Study (DFS) later that year.
The study started when silver prices were trading in the mid US$20 per ounce.
That means IVR has been designing the project to work in a low silver price environment.
The silver price is now more than double where it was when IVR started its DFS.
UPDATE: IVR’s DFS had an overall project All In Sustaining Cost (AISC) of US$27.39 per ounce.
AISC defines the long-run cost to produce from IVR’s project. So technically, IVR’s project should be economically feasible in any scenario where silver is above ~US$28 per ounce.
8. IVR’s new MD has brought an asset online in South Australia before
Lachlan was previously Managing Director of ASX-listed Hillgrove Resources where he led the design, permitting, financing and restart of the Kanmantoo copper mine...
That project is also in South Australia ~60km south east of Adelaide.
So he knows his way around permitting in South Australia.
We are backing Lachlan to do it all again with IVR’s project, also in South Australia.
Ultimately, we want to see IVR achieve our Big Bet which is as follows:
Our IVR Big Bet:
“IVR takes advantage of the high silver price environment and puts its project into production. At that point, we would expect IVR to be capped at multiples of our Initial Entry Price”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our IVR Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What do we want to see IVR do next?
Permitting 🔄
With the DFS published, we will be watching IVR go through all of the permitting workstreams on its project.
We especially want to see the project get a mining licence and an environmental permit granted for the project as soon as possible.
Recently IVR submitted the Mining Lease Application (MLA) (source)
Here are the milestones we are tracking:
- 🔄 Environmental permits
- 🔄 Project infrastructure permits
- 🔄 Mining licence granted
Project financing 🔄
The DFS outlaid a CAPEX of A$260M. We want to see IVR make progress on debt/equity financing while the silver price is supportive.
Now that the DFS has been published, the next major catalyst for IVR will be project financing.
While permitting is progressing, we want to see IVR make progress on debt/equity financing commitments for the project CAPEX of A$260M.
- 🔄 Lender engagement and technical due diligence
- 🔲 Financing commitments
Grade control drilling 🔄
We want to see IVR complete infill drilling at its resource and upgrade the resource in terms of classification.
Drilling on regional targets 🔄
We also want to see IVR drill out the 15km corridor of targets that sit around its 57M ounce JORC resource estimate.
The ultimate success from these drill programs would be a discovery similar to IVR’s existing resource.
Here are the milestones we are tracking:
- ✅ Geophysics/Geochemistry work
- ✅ Identify drill targets
- ✅ Drilling starts
- 🔄 Drilling results
- 🔲 Followup drilling
What are the risks?
In the short term, the key risk is “commodity price risk”.
IVR’s share price will likely fluctuate with movements in the silver price.
If silver’s breakout is only temporary and the price starts falling dramatically, then capital could flow out of silver stocks in general which would impact IVR’s share price negatively.
Commodity price risk
The performance of commodity stocks are often closely linked to the value of the underlying commodities they are seeking to extract. Should silver prices fall, this could hurt the IVR share price.
Source: “What could go wrong” - IVR Investment Memo 03-Oct-2025
Other risks
Like any pre-development mining company, IVR carries significant risk, here we aim to identify a few more risks.
Although IVR has lodged its Mining Lease Application with targeted completion in 2027, permitting delays or regulatory bottlenecks with government authorities could stall project advancement.
Developing the Paris Silver Project requires substantial capital, with an estimated A$260M development requirement. While IVR is currently well funded, securing favourable project debt or non-dilutive financing in the future is not guaranteed and could result in equity dilution or timeline delays.
Moving from front-end engineering design into full mine construction introduces key execution, metallurgical, and cost inflation risks. Unexpected capital expenditure overruns or construction delays could negatively impact the economic metrics outlined in the definitive feasibility study.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our IVR Investment Memo
You can read our IVR Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
Our IVR Investment Memo covers:
- What does IVR do?
- The macro theme for IVR
- Our IVR Big Bet
- What we want to see IVR achieve
- Why we are Invested in IVR
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.