AW1: The biggest indium resource in the USA + a PFS-stage copper project with US$233M NPV... capped at $34M.
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 16,834,000 AW1 Shares and 8,417,000 AW1 Options at the time of publishing this article. The Company has been engaged by AW1 to share our commentary on the progress of our Investment in AW1 over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
Yesterday we wrote that there are plenty of small stocks out there with beaten down share prices.
After two months of indiscriminate selling across almost every stock...
(even though most have made great progress over the last year or two)
In our opinion, the “Critical Minerals for the Global Buildout of AI, Robots and Advanced Weapons” investment thesis is still firmly in play.
One of our stocks leveraged to this investment theme is American West Metals (ASX:AW1).
AW1 has the biggest indium resource in the USA.
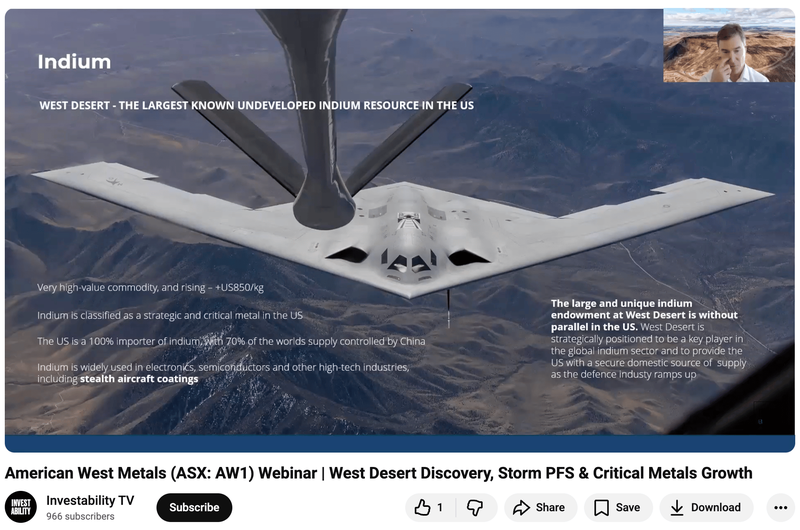
Indium is critical for building missile guidance systems, stealth coatings, fighter jets, radar systems and the lasers inside AI data centres.
And an advanced stage copper project in Canada - copper is critical in transporting electricity (i.e energy) - kinda important in AI and robots...
AW1 has not been immune to the broad and indiscriminate global sell off.
It’s currently capped at $34M and had $5.4M in the bank at September 30th - an Enterprise Value of less than $30M.
AW1 is trading at almost 1/10th of its copper project’s NPV and the market appears to be attributing very little value to its giant USA indium asset.
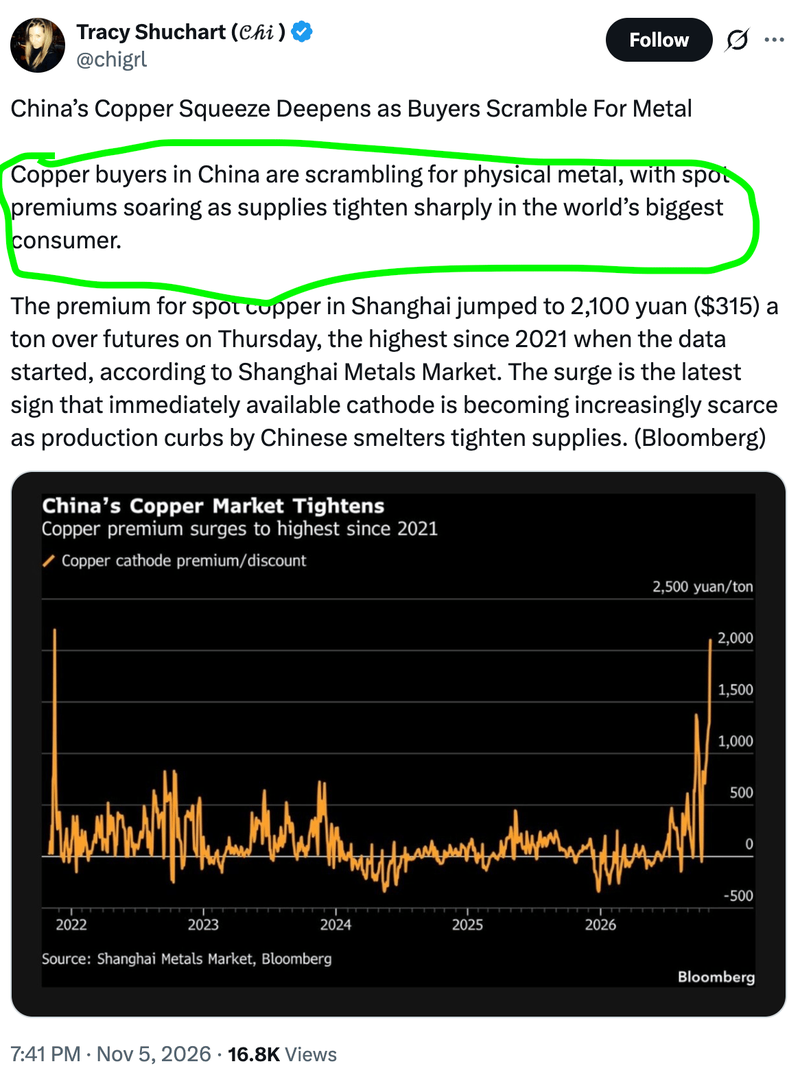
The copper setup right now:
AI, data centres, electrification are all causing a physical supply shortfall:
(source)
The setup for critical mineral indium:
Again, indium is critical for building missile guidance systems, stealth coatings, fighter jets, radar systems and the lasers inside AI data centres.
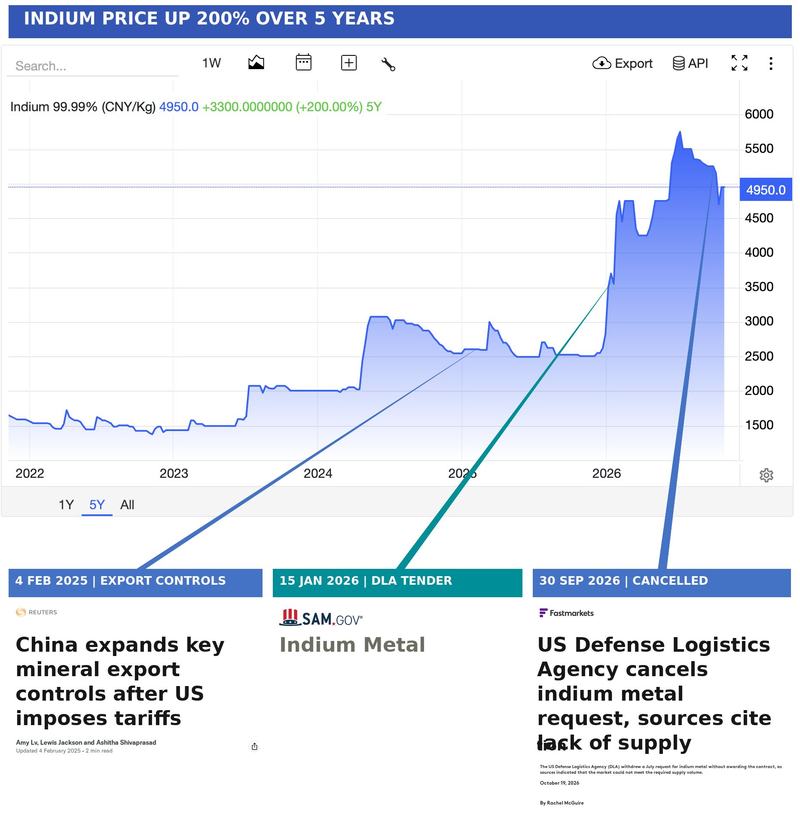
China refines ~70% of global supply and has had export controls in place since February 2025.
The US has zero domestic production of indium.
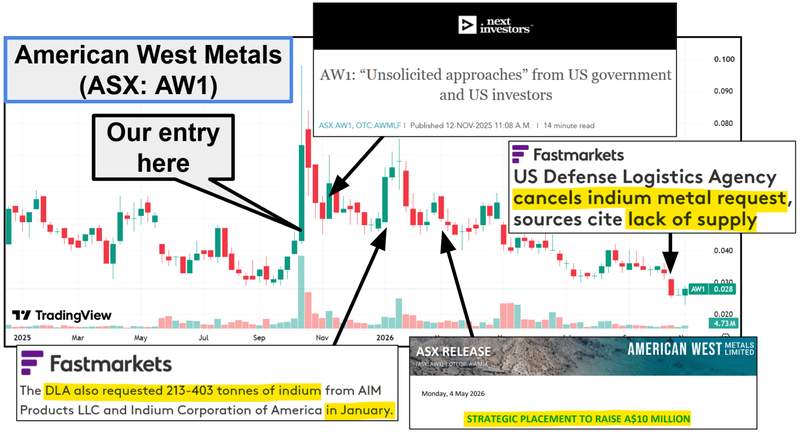
In January, the US Defense Logistics Agency launched a US$125M tender to buy American-made indium, doubled it to US$250M in July, then cancelled it in September - apparently because there was no supply.
Which has led to indium prices mooning:
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
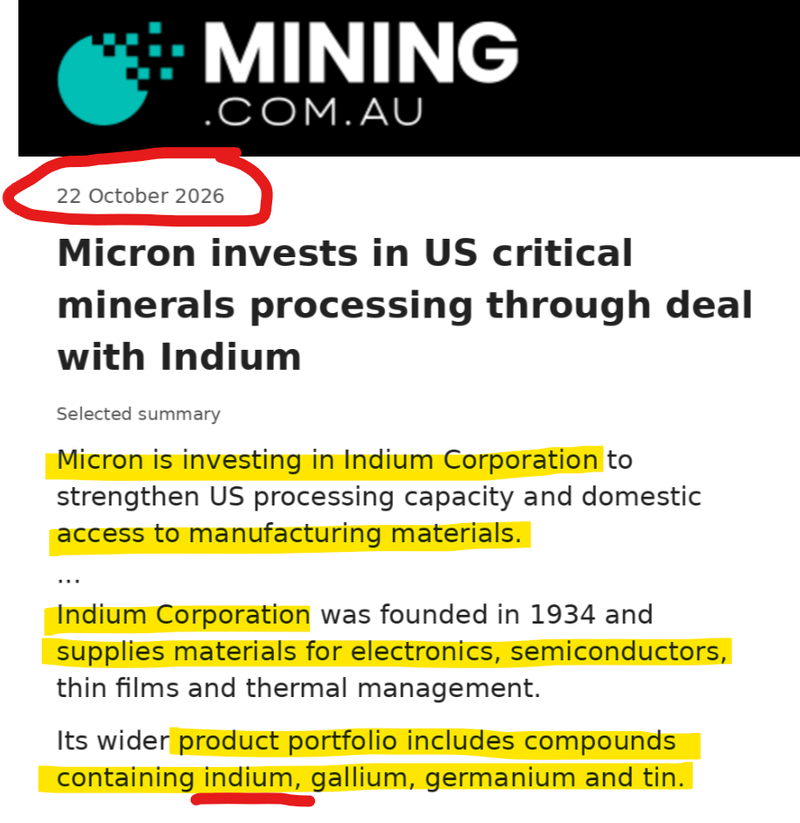
Two weeks ago: $1 Trillion market cap memory and storage chip maker Micron Technology (NASDAQ:MU) invested into Indium Corporation for critical mineral refining and processing:
(source)
Our Investment AW1 has both metals - copper and indium.
The copper is in an advanced stage project.
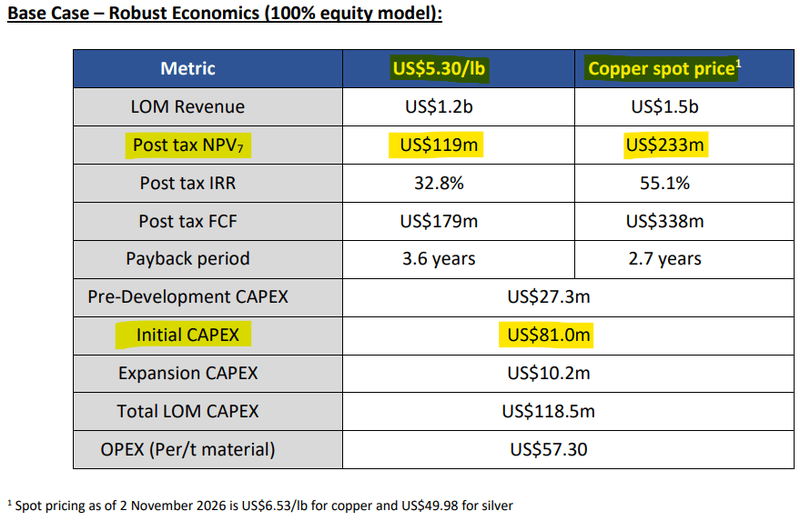
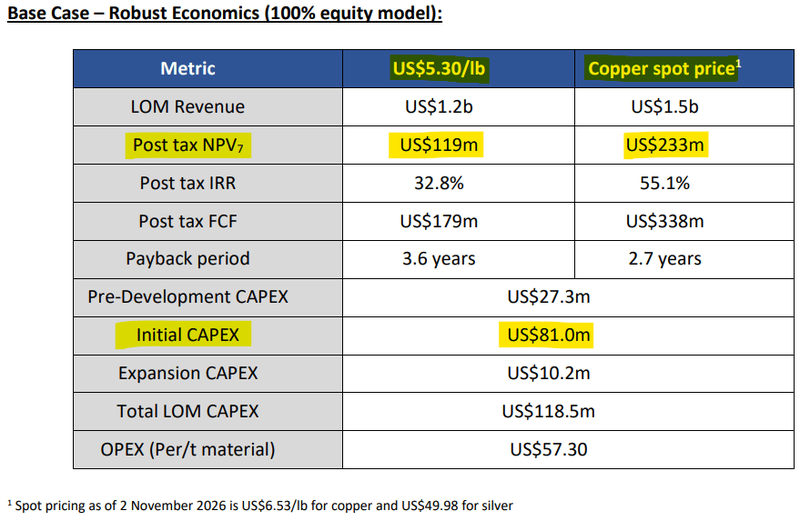
Yesterday AW1 released a Pre-Feasibility Study showing the following - on a 100% basis:
- Post-tax NPV of US$233M (at ~US$6.50 copper prices)
- Post-tax free cash flow US$338M
- Initial CAPEX of just US$81M
- And a 2.7 year payback
AW1 owns 80% of the project.
Keep scrolling for our key takeaways on that PFS later in today’s note
Anyways, pretty solid numbers for a $34M capped stock.
And...
AW1 also owns 100% of the single biggest indium resource inside the US.
An asset that has attracted "unsolicited approaches" from the US Department of War and Department of Energy. (source)(source)
In a webinar - skip to 18:43 back in May this year, AW1 founder, major shareholder, and Managing Director Dave O'Neill said he:
"can't talk to what is going on behind the scenes" ... because of confidentiality around the US discussions.
What we do know from the ASX releases since:
- In June, AW1 briefed US government officials at the White House Complex during the Aerospace & Defence 2026 Conference in Washington DC. (source)
- In September, AW1 engaged Washington advisors GreenMet to pursue US government funding, strategic partnerships and offtake for the indium project. (source)
- And then in October, "Strategic engagement has been accelerated with US Government agencies with support from GreenMet. Discussions on critical metals partnerships, supply and production are continuing with a focus on the indium." (source)
(source)
And it looks like the indium resource might get bigger too - AW1 has been drilling that project this year...
...and has hit extensions ~430m to the east, ~350m to the west and ~1km to the north of its resource.
(very big extensions)
We think AW1 has been one of the stocks in our Portfolio that’s been unfairly punished in the recent market downturn.
As we mentioned above, AW1 is trading at almost 1/10th of its copper project’s NPV and the market appears to be attributing very little value to its giant USA indium asset.
We think that as the copper asset is progressed it could gradually re-rate AW1’s share price to a more reasonable valuation relative to the project’s studies.
The wildcard for the stock though is the indium.
IF indium has its “rare earths” moment - things could turn very quickly for AW1.
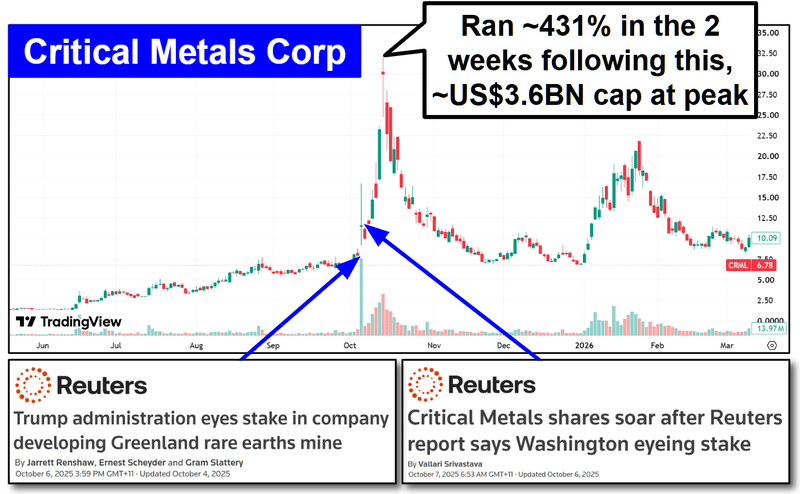
We wrote about NASDAQ listed Critical Metals Corp earlier this week which for years held a Greenland rare earths asset.
The market didn't really understand or care about it for a while.
Then one day everything changed (quickly) - US President Trump started talking about Greenland rare earths deposits, and there were rumours the US government was going to take a stake in Critical Metals Corp.
Critical Metals’ share price proceeded to go from ~US$6 per share to US$32.15 per share in two weeks - a market cap of over US$3BN at its peak.
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
As mentioned earlier, AW1 has said on the record that it has been approached by the US Department of War, the Department of Energy and local government. (source)
All it could take is some mainstream media coverage of US government interest OR actually having that interest materialise into an investment or offtake deal and suddenly AW1’s share price could start to move fast.
Looking at the AW1 share price chart - it does surprise us that the chart has gone backwards despite all time high copper prices and everything happening with indium:
(source)(source)(source)(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
While we wait for action on the indium asset...
We are pretty comfortable holding AW1 knowing AW1 is also progressing a copper asset that is (after yesterday) at the PFS stage AND that the $300BN miner BHP once farmed into.
Here are the PFS numbers again for the copper asset - the left column is the conservative US$5.30/lb case, right column is the copper spot price (US$6.53/lb):
(source)
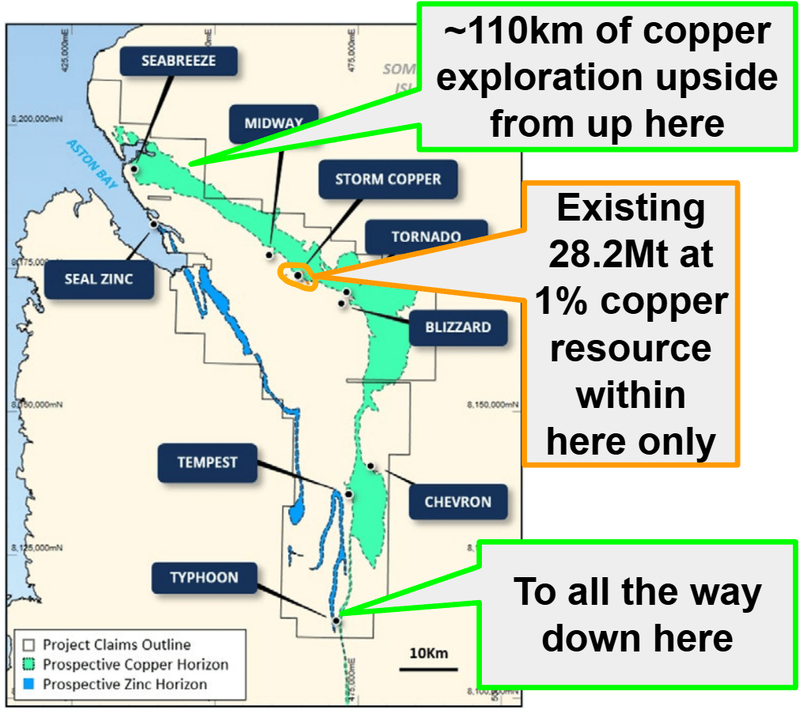
Below is an idea of how much exploration upside the project still has - the 28.2Mt at 1% copper resource is the small orange circle, the green is the ~110km of strike that hasn't been drill tested properly.
(source)
Probably speaks to why the big boys had their foot on this asset all those years ago...
More on AW1’s copper project AND our thoughts on the Pre-Feasibility Study
AW1’s PFS centres around four open pits feeding a ~1.3Mtpa processing plant - producing ~10,000 tonnes of copper (and some silver) for 11 years.
Here are the PFS headline numbers again:
(source)
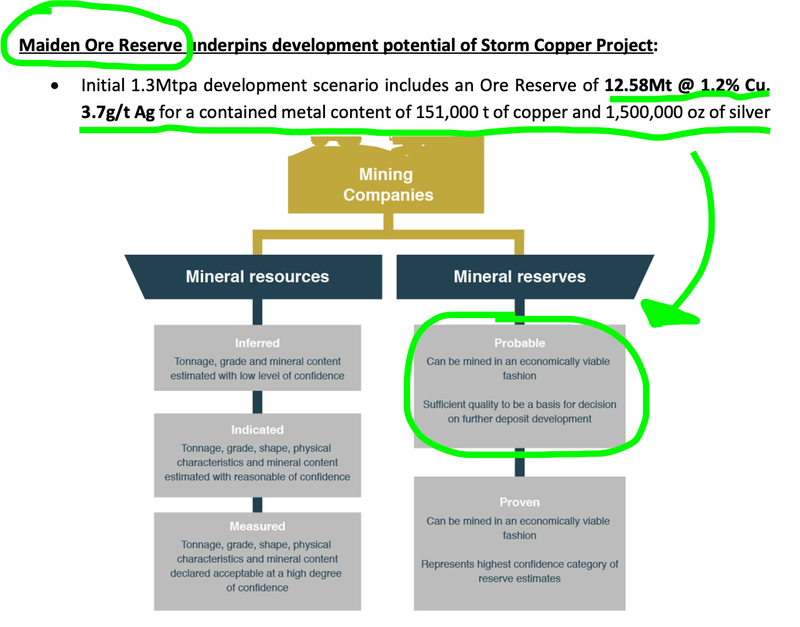
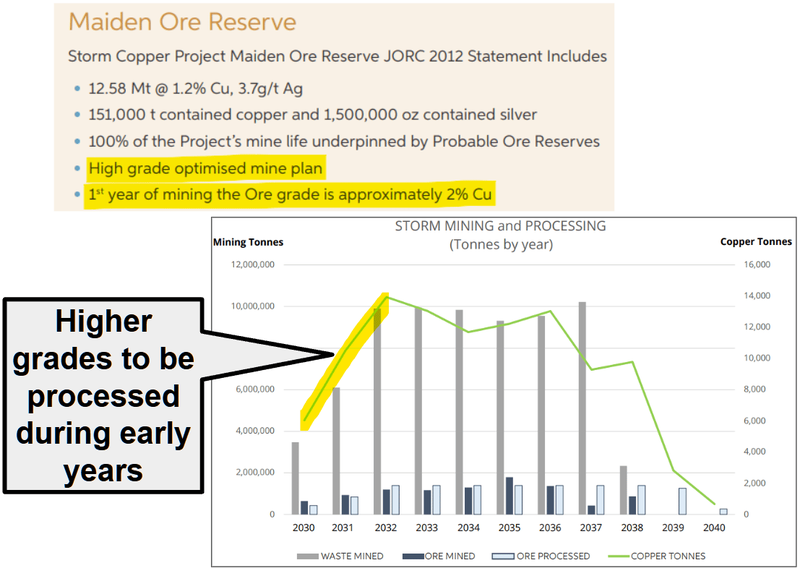
And here is the ore reserve AW1 announced together with the PFS:
(an ore reserve is the part of a resource that a mining engineer has signed off as economically mineable)
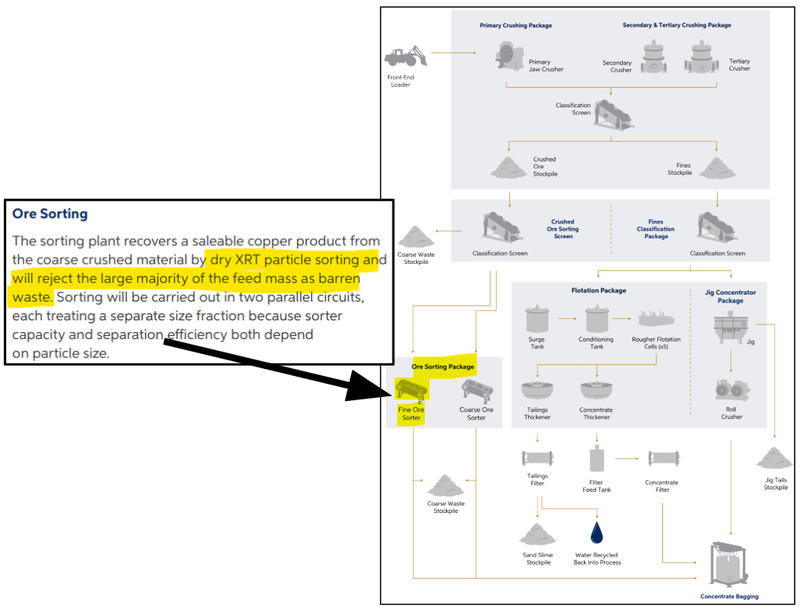
A part of the PFS we liked (that the market probably didn’t read through to) was the ore sorting tech AW1 is planning to use.
AW1’s flowsheet would use what is like a giant X-ray machine getting rid of waste rock being processed.
(source)
That's why the initial CAPEX for the project is only US$81M for an up to 14,000tpa copper mine - there's no big concentrator (just a small flotation circuit) and no tailings dam.
It’s also why AW1’s plan is to produce a ~15% copper product (with minimal impurities).
We also like that AW1 has scheduled the higher-grade product to come into the mine plan very early on - which should take some pressure off the finances during that risky ramp-up period IF/when the project is developed.
(source)
Overall, we think the PFS makes a solid case for getting the project developed on its own.
BUT we think the big upside for AW1’s project is IF/When AW1 can drill out the rest of the ~110km belt (where only ~5% of the area has been drilled).
AW1 has seven advanced targets ready to go, including a 4.1km x 0.7km copper-in-soil anomaly that's never been drilled.
Maybe the plan is to get into production and drill those out with cashflows?
Who knows.
What we do know is that the exploration upside is what bigger companies want to see when looking at projects that can be M&A targets - which they can unlock with their bigger balance sheets.
Maybe that’s also why at one point, AW1’s project had farm-in deals with:
- $300BN BHP in 2016 who signed an earn-in deal that would have seen them spend US$50M on the project, and
- $59BN Antofagasta also JV'd into the project around the same time.
Both had walked away by 2018 - when copper was trading at ~US$2.80/lb.
Probably more to do with the copper price tanking and both companies refocusing their efforts on the giant porphyry deposits they were developing in South America.
M&A isn’t why we are Invested in AW1 though - we want to see AW1 push forward with the developing the asset on its own.
Especially given the funding options already in place to finance the CAPEX for this asset.
Here is everything AW1 has signed in the past for the project:
- A binding offtake agreement with Ocean Partners - Ocean holds ~6.4% of AW1 and has a binding offtake over 100% of Storm's copper-silver product, AND has agreed to provide up to US$40M of senior secured debt - roughly half of the US$81M initial CAPEX. (conditional on a bankable feasibility study and FID) (source)
- A US$12.5M (~A$18.8M) royalty deal for non-dilutive funding - signed with Taurus Mining Royalty Fund in 2024. AW1 and Aston Bay have already banked the first US$5M. The next US$3.5M comes in when a PFS is completed and permitting is lodged for development. Then another US$4M if the resource grows to at least 400kt of copper averaging at least 1.00% (AW1's resource is currently 276kt copper at 1.0%). (source)
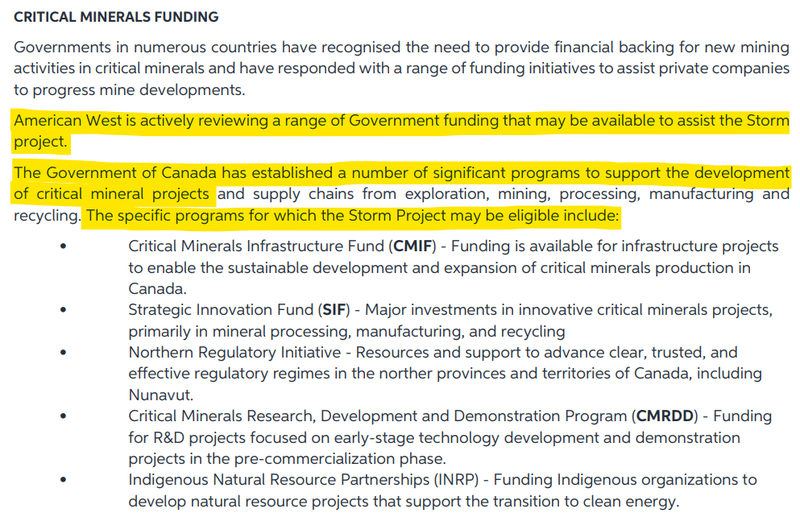
So another US$3.5M should be coming in soon once permits are lodged which is “targeted for submission during Q4 2026” (source), so by the end of the year. - Canadian government critical minerals money - AW1 has said it is actively reviewing "a range of Government funding that may be available" and names five programs the project may be eligible for. (source)
(source)
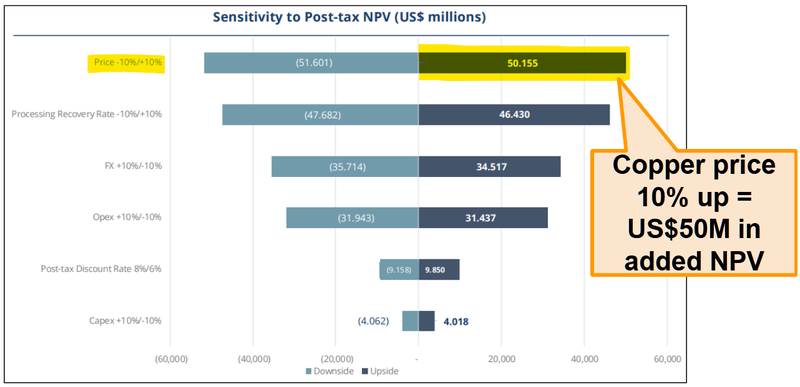
Oh and finally, there is the sensitivity table in the PFS which shows that for every 10% move in the copper price AW1’s NPV moves US$50M (from the base case figures).
(source)
So if the copper bull case plays out, the NPV could be a lot stronger too...
We are bullish copper
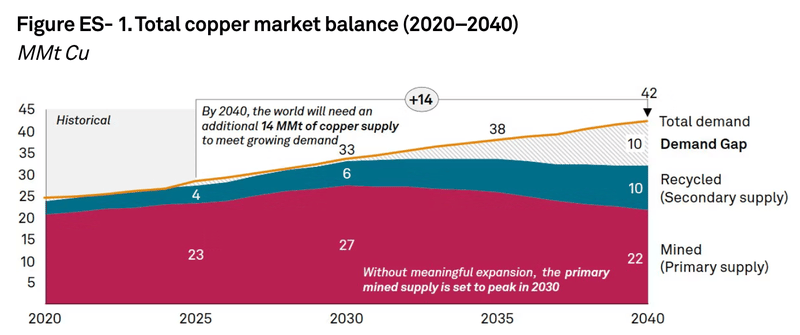
We think fundamentally, the setup for copper is as good as it gets - both in the short/medium and long term.
Some might remember the “copper is the new oil” stuff from back in 2021 when copper was the backbone of the electrification/energy transition.
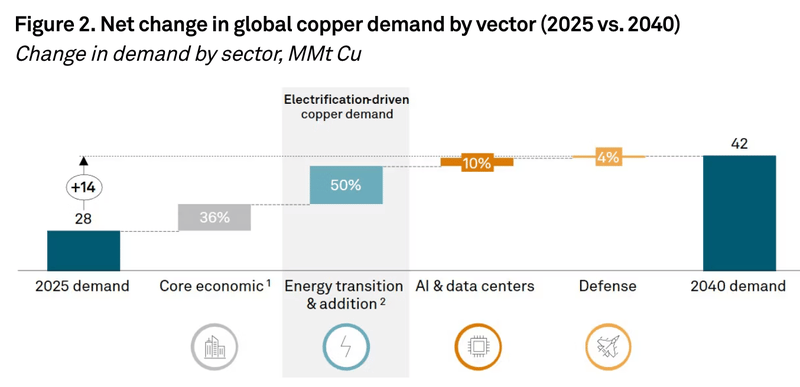
Since then, AI data centres and robots entered the chat - in a big way - and the copper demand story is seriously strong now on a 5, 10 and 20 year outlook.
It turns out hyperscale data centres use a massive amount of copper (sometimes ~50,000 tonnes of copper in a single data centre).
(source)
IF even half of the AI/robotics/energy transition build out happens that is a big increase in demand in a very mature market - where supply can't just be brought online overnight.
(source)
IF copper price really goes parabolic and all of the calls for a structural supply shortage plays out then this asset could be the big dark horse for AW1.
Here is another presentation - from billionaire mining financier Robert Friedland - titled "Dawn of the Copper Age" where he covers the AI - copper connection really well.
Our key takeaway:
Humans will need to mine more copper in the next 18 years than we have mined in all of recorded history combined - just to meet forecast demand from AI data centres, grid upgrades, chips, weapons systems and electrification.
PRESENTATION: The dawn of the copper age
(Friedland is the GOAT 🐐of mining presenters - really worth a watch)
More on AW1’s critical mineral (indium) project in the US
As we said above, AW1 holds 100% of the largest indium JORC resources in the USA.
AW1's project is already fully permitted for an open-pit mine and exploration shaft construction.
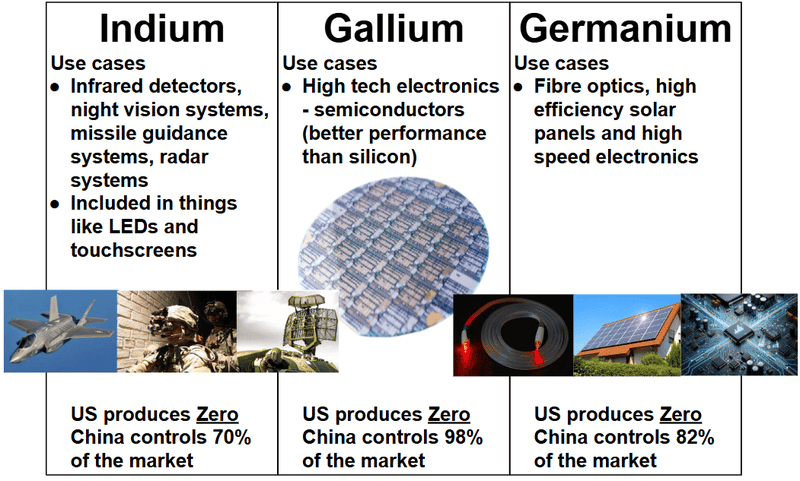
The project might also contain critical minerals gallium and germanium too.
(a historic core sample showed a combined total of 518m of gallium intersections with peak grade of 77.3g/t).
So AW1's project could actually have three critical minerals the USA mines none of.
(China refines 70% of the world's indium, 98% of the world's gallium, and 60% of the world's germanium.)
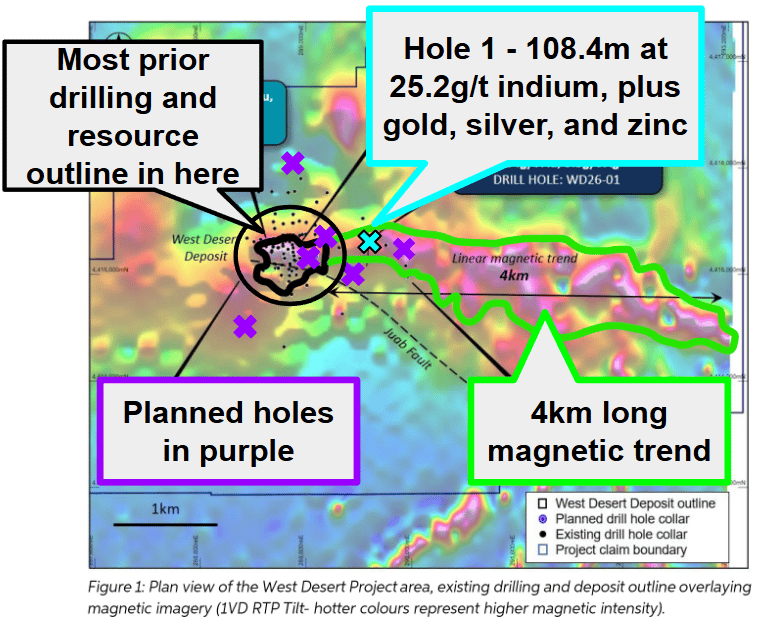
AW1 has been drilling this project over the course of this year and has already hit extensions way outside of its resource including a new discovery to the west of the resource.
The bigger kicker was that the extensions to the east validated AW1’s theory that its resource could actually extend all the way across a ~4km long magnetic anomaly:
(source)
So with one drill result, AW1 has opened up potential extensions ~4km to the east and shown that the resource average grade could be a lot higher too.
We think that as AW1 drills out its project and is able to define an even larger resource - its attractiveness as a potential source of a critical mineral where the US has no current domestic supply becomes a lot harder to ignore.
On this point, and as we noted above, in September AW1 engaged US based advisory firm GreenMet to accelerate engagement with the US government.
GreenMet is the company founded and led by Drew Horn, who worked in the Defence and Energy departments during Donald Trump’s first term and, after the 2020 election.
Horn was also a former senior US critical minerals and energy security official with time spent in the White House, the Office of the Director of National Intelligence, the Department of Energy and the Department of War.
According to the following Bloomberg article from August last year Horn’s GreenMet is a “company that arranges deals between the US government and the private sector around critical minerals”.
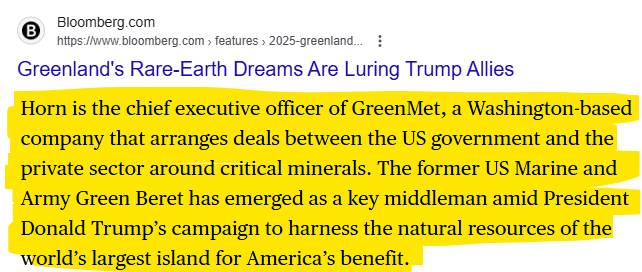
Read that full article here: Greenland’s Rare-Earth Dreams Are Luring Trump Allies.
GreenMet's mandate for AW1 will be to pursue government funding, strategic partnerships and potential offtake arrangements for AW1’s indium project in Utah.
Ultimately, success on the US asset is a big part of our AW1 Big Bet:
Our AW1 Big Bet:
“AW1 receives capital from either the US government, a strategic partner or the capital markets to progress its Indium project in the USA, re-rating AW1 to a valuation that is multiples of our Initial Entry Price”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our AW1 Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What’s next for AW1?
US indium project (West Desert, Utah)
Here we want to see AW1 run its upsized drill program, grow its resource and hopefully define a gallium & germanium resource to go with it.
Here are the milestones we are tracking:
- ✅ Drilling commenced
- 🔄 Assays from holes 6 & 7 ("1 to 2 weeks" from 30 October)
- 🔄 Assays from hole 8 (4-6 weeks from 30 October)
- 🔲 Updated West Desert JORC resource estimate
Strategic / Government Engagement
- 🔄 Defense Production Act Title III funding
- ✅ Briefed US government officials at the White House Complex (June)
- ✅ AW1 hired Washington based advisors to lead US government engagement
- 🔲 Formal US government funding deal / offtake / stockpile inclusion
- 🔲 Potential US listing
Canadian copper project
The next major catalyst for AW1’s copper project will be turning the PFS into a DFS (Definitive Feasibility Study) and progressing the project through mine permitting, plus putting together CAPEX funding:
- ✅ Pre-Feasibility Study + maiden Ore Reserve
- 🔲 Environmental studies and permitting milestones
- 🔲 Final mining application (targeted Q4 2026)
- 🔲 Definitive Feasibility Study (2027)
What could go wrong?
The biggest risk for AW1 right now is "Exploration risk".
AW1 is actively drilling its indium project in the US.
IF the market starts to build in higher expectations from future drill results and AW1 returns disappointing results it could negatively impact AW1’s share price.
Another risk is “Critical Minerals Macro risk”
Critical Minerals Macro risk
A big part of our Investment is related to critical minerals macro sentiment strengthening and resulting in a funding deal for AW1’s US indium project. IF macro sentiment was to turn, then the chances of that asset being funded/brought online would reduce significantly. This could mean a re-rate lower in AW1’s share price.
Source: “What could go wrong” - AW1 Investment Memo 16 October 2025.
Other risks
Like any early-stage exploration and development company, AW1 carries significant risk, here we aim to identify a few more risks.
While the PFS shows a US$233M NPV at today's copper price, the base case at US$5.30/lb is US$119M. A fall in copper back towards the base case price could cut the project's value roughly in half, and the PFS shows every 10% move in copper shifts the NPV by around US$50M.
Although Ocean Partners has agreed to provide up to US$40M of senior secured debt, that facility is conditional on a bankable feasibility study, formal documentation and a final investment decision. If any of those conditions are not met, AW1 may need to find a larger share of the US$81M initial capex elsewhere.
AW1 had ~$5.5M cash at the end of September, with the quarterly showing around 1.6 quarters of funding at the current spend. With a DFS, drilling in Utah and permitting all planned for 2027, AW1 may need to raise capital, which could dilute existing shareholders.
While ore sorting keeps the CAPEX low, the PFS is based on test work rather than a full-scale plant, and the study is only accurate to +/-25%. If the sorters or recoveries underperform at scale, operating costs could rise and the project's economics could weaken.
Given Storm sits on Somerset Island in Nunavut, supplies arrive by sealift and regulatory approval is targeted for ~2028. Any delay to the NIRB review, the permitting process or the short Arctic shipping windows could push back the targeted 2028 investment decision and 2030 first production.
The Critical Metals Corp share price run we reference is another company's story, driven by US government interest in its own asset. There is no guarantee US agencies take a similar interest.
While AW1 has hit visual mineralisation to the east, west and north of its indium resource, assays from holes 6, 7 and 8 are still pending. Results below market expectations could weigh on the share price and slow the case for a larger resource.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our AW1 Investment Memo
You can read our AW1 Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
Our AW1 Investment Memo covers:
- What does AW1 do?
- The macro theme for AW1
- Our AW1 Big Bet
- What we want to see AW1 achieve
- Why we are Invested in AW1
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.