$15.5M CND formally qualified to negotiate full licence over Tumbes Basin asset - 3.3BN barrel oil prospects AND an existing 1Tcf gas discovery.
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 48,634,867 CND Shares and 13,675,000 CND Options at the time of publishing this article. The Company has been engaged by CND to share our commentary on the progress of our Investment in CND over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
For the first time in over 50 years, ~30% of global oil and gas supply is at risk - from disruptions in the Middle East market.
So why haven’t oil prices run to over US$200 a barrel?
We think it's because the world has gone on a binge drawdown of oil reserves and inventories - that’s keeping markets relatively calm... for now.
JPMorgan put out a note back in May which estimated that IF there was no resolution inventories could be at “stress levels” by June.
AND by September at “operational floor levels” - “the minimum level to keep refineries operating”.
Here we are in mid-October and there is still no resolution.
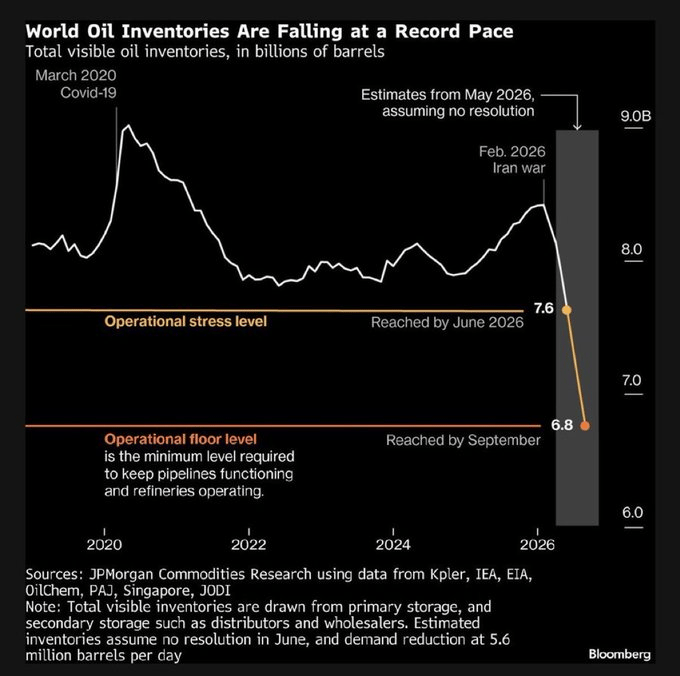
JP Morgan is now saying "We simply don't know how to model the endgame." (source)
We think that IF the Middle East disruption isn’t resolved (and it looks like it won't be) by January, we could see a big rally in oil prices...
...like it did the last time the Middle East went offline.
Well above oils inflation adjusted highs - to go past those, oil would need to go through US$220 per barrel:
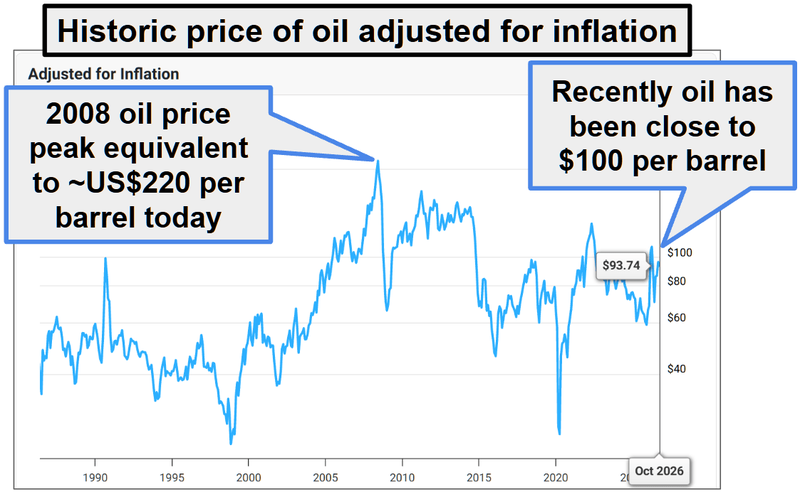
(source)
Past performance is not an indicator of future performance. Commodity prices are volatile and can fall as well as rise.
We think that IF oil prices run, small cap oil and gas stocks like our Investment Condor Energy (ASX:CND) could run with it.
(no guarantees of course)
We have been Invested in CND for many years now, and are substantial holders.
We’ve been waiting for CND get closer and closer to the point where it is in a position to finally drill test its asset - today we got one big step closer to that.
CND holds the exclusive right to apply for a conventional exploration contract on 100% of a block offshore northern Peru with:
- 3.3 billion barrels of oil in prospective resources across (unrisked) six prospects. (source)
- AND an existing 1 Tcf gas DISCOVERY - Piedra Redonda, which has already flowed gas to surface. (source)
CND is capped at just $15.5M.
CND could re-rate irrespective of oil prices in the coming weeks or months -
We are watching for when CND’s block gets converted into a full blown exploration licence contract by the Peruvian regulators.
That licence is what would give CND the right to explore and develop the block - to farm it out, to drill the oil prospects, to commercialise the gas.
THAT is when we think the market re-rates CND on the merits of its existing gas discovery and its oil prospects.
Today was a big step forward for CND - the company got formally qualified by the Peruvian regulators.
(meaning they are satisfied with CND’s capacity to become an exploration licence holder)
Now, CND moves into the negotiation stage which is where CND lays out what it will do when/IF the license is granted:
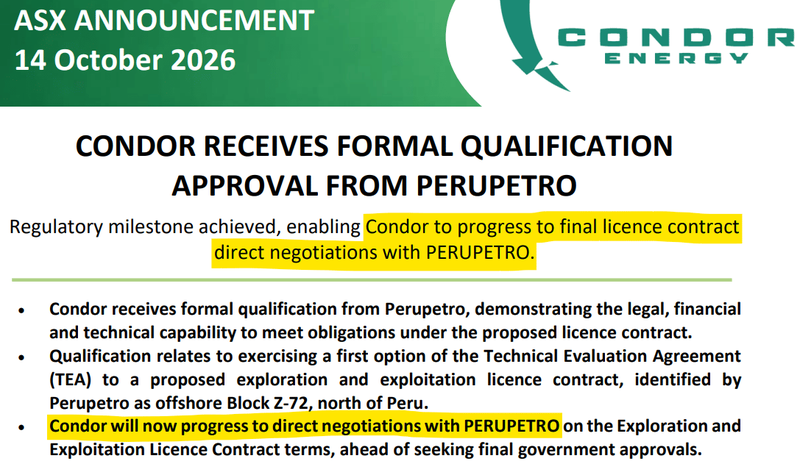
(source)
So there is a chance that within the next few months, CND holds a full exploration licence - JUST as oil prices start taking off...
AND as offshore South American oil & gas is starting to attract some of the big supermajors
We think South America (including fingers crossed Peru) is going to be one of the regions those buyers look to allocate capital to, and diversify supply chains out of the Middle East from.
Especially now with things looking like they are escalating even more, this is a headline from just ~40 minutes ago:
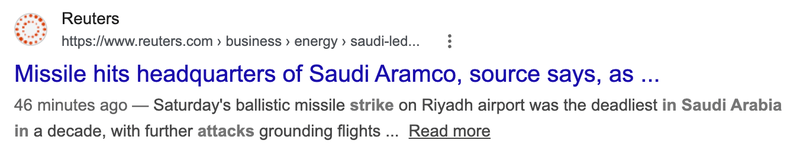
(source)
We are already seeing a diversification of supply in Asia, where most of the current supply from the Middle East ends up - Korea's National Security Adviser said a few months ago:
"This is expected to provide an opportunity to diversify our crude oil supply sources, which are currently concentrated in the Middle East, by expanding them into South America." (source)
In July, South Korea took delivery of oil from Argentina for the first time ever - with plans to make it more of a regular thing from next year. (source)
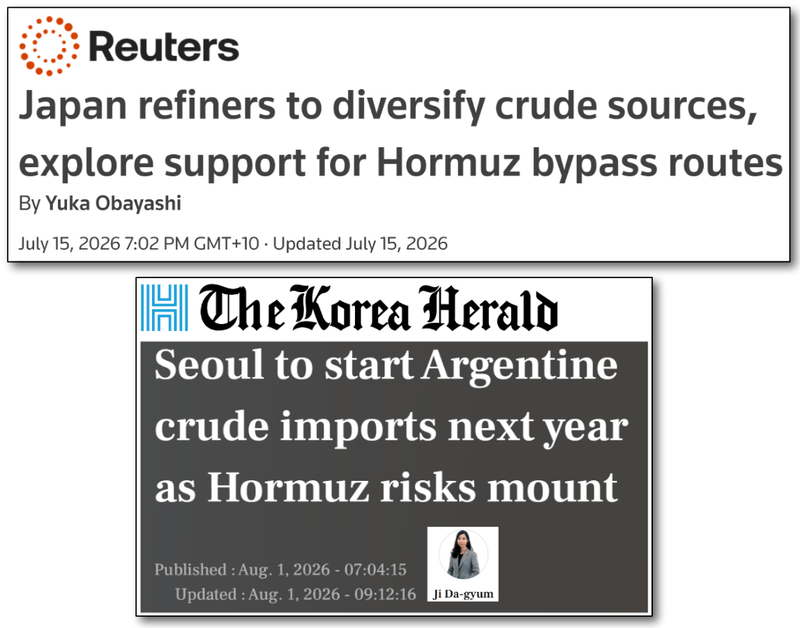
Confirmation to us that one of the up and coming oil & gas regions in the world right now is South America.
And the supermajors’ movements into the area back that up.
CND’s block is:
- Surrounded by ~$283BN TotalEnergies who spent two years studying its ground, then exercised its option to negotiate a full licence.(source)
- To the north of Warren Buffett-backed Anadarko who shot 6,018km2 of 3D seismic over its blocks in 2024 at a cost of ~US$40M and has now committed to drilling its first well in 2027. (source)
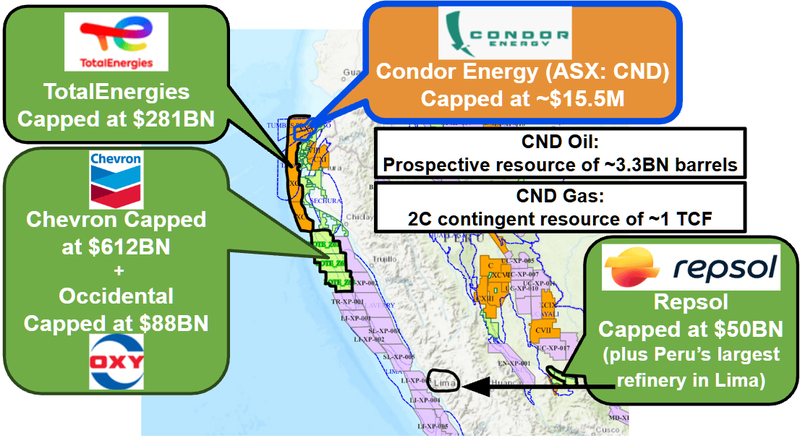
(source)
So tiny CND, with 3.3 billion barrels of oil in prospective resources and an existing 1 Tcf gas DISCOVERY...
... capped at just ~$15.5M could soon be in play (IF/when its block is converted into an exploration licence).
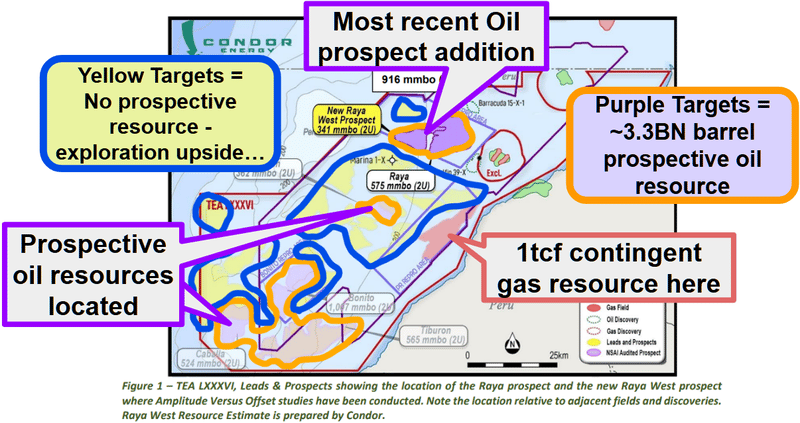
(source)
A big part of why we like CND is because of where its asset sits AND because CND was a first mover into Peru - way before the majors started coming into the region.
CND's block sits in Peru's Tumbes Basin, right alongside the Talara Basin - which have combined historic oil production of more than 1.68 billion barrels. (source)
CND’s block actually holds a few existing discoveries in it already - so we know there is a working hydrocarbon system.
CND came into Peru back in August 2023. (source)
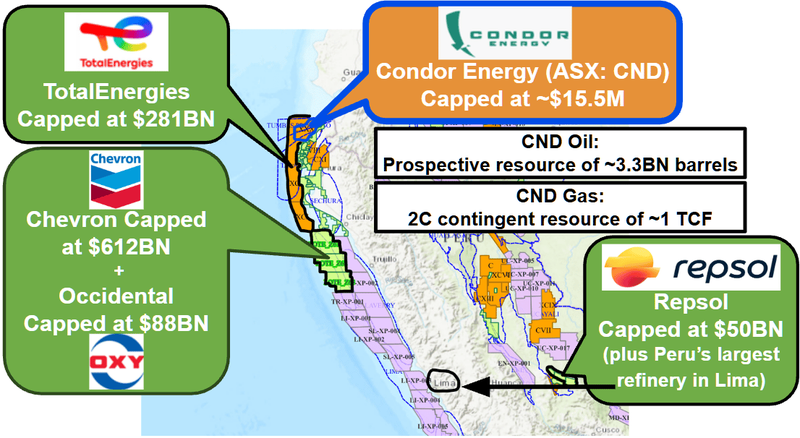
Here is when all the majors came into the region:
- ~US$283BN TotalEnergies in May 2024 - picking up all of the blocks surrounding CND.
- ~US$585BN Chevron in August 2025 - through a farm-in on Anadarko’s blocks to the south. (source)
- Then Westlawn, a Houston-based offshore group - took 30% of the Chevron/Anadarko blocks in September 2025. (source)
(Perupetro also said in late 2025 that Petrobras had come knocking about the Tumbes–Piura shelf) (source)
(source)
We think that IF CND has its permit converted from a TEA into a full exploration licence.
And then next year Anadarko drills in Peru and finds anything, CND’s market cap could re-rate well above where it trades today.
Especially with 100% ownership of 3.3 billion barrels in oil prospects and an existing 1 Tcf gas discovery.
Ultimately, the licence contract is what gives CND the right to drill and develop the block.
And we think IF successful - that grant alone could be a major catalyst for a re-rate in CND’s share price.
No guarantees of course - Perupetro approval is not guaranteed, and timing can slip. CND is a tiny company with no revenue. More on the risks below.
We think the licence contract opens the door to deals being done on CND’s block
Understandably, anyone committing to a farm-in would have wanted to see CND have tenure over the block.
In April 2025 CND said it had “multiple parties in the dataroom” and that a farm out process had commenced. (source)
So hopefully a lot of the warming up of interested parties has already been done, AND IF/when the licence is granted things can start to happen quickly.
IF CND secures the licence contract we think CND could:
1. Do a deal on its 1 TCF existing gas discovery - Maybe CND gets a free-carried interest in an asset that could generate revenues in a reasonable timeframe? We note Promigas - the gas distributor for 94% of Peru's market - is already studying the asset under an MoU. (source)
OR
2. Do a deal on its 3.3BN barrel oil exploration assets - Maybe CND lands a free-carried interest in a well that's fully funded by a farm-in partner.
OR maybe it's a combination, a partner that wants BOTH the oil and the gas.
Ultimately we think that IF CND lands that licence contract it will have big enough targets and an existing discovery large enough, to farm-down to bigger parties.
AND we hope retains something company making... especially from the current $15.5M market cap.
We look at CND in two ways right now
Scenario A:
- We have exposure to an EXISTING 1 Tcf gas discovery - one that's flowed gas before and got close to development in the past.
In that scenario we get the 3.3 BN barrels of oil exploration upside as a “free option”.
Scenario B:
- Exposure to 3.3 billion barrels of oil exploration targets offshore Peru
In that scenario we get the 1 TCF existing gas discovery as a “free option”.
Either way we think the current $15.5M market cap is highly leveraged to a re-rate (IF that licence contract lands).
Our CND Big Bet
“CND defines a multi-billion barrel prospective resource and sees its market cap re-rate by 20x prior to drilling”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). There is a lot of work to be done, many risks involved - just some of which we list in our CND Investment Memo.There is no guarantee that our Big Bet will ever come true.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
Deep dive into CND’s existing 1 TCF gas discovery
This is the "advanced-stage" part of CND’s block.
CND's Piedra Redonda gas field is a 1 Tcf discovery and CND has an MoU signed with Peru’s biggest gas distributor - Promigas Peru on the asset. (source)
Promigas manages, maintains and builds gas infrastructure across northern Peru - supplying gas to homes, businesses and industrial facilities.
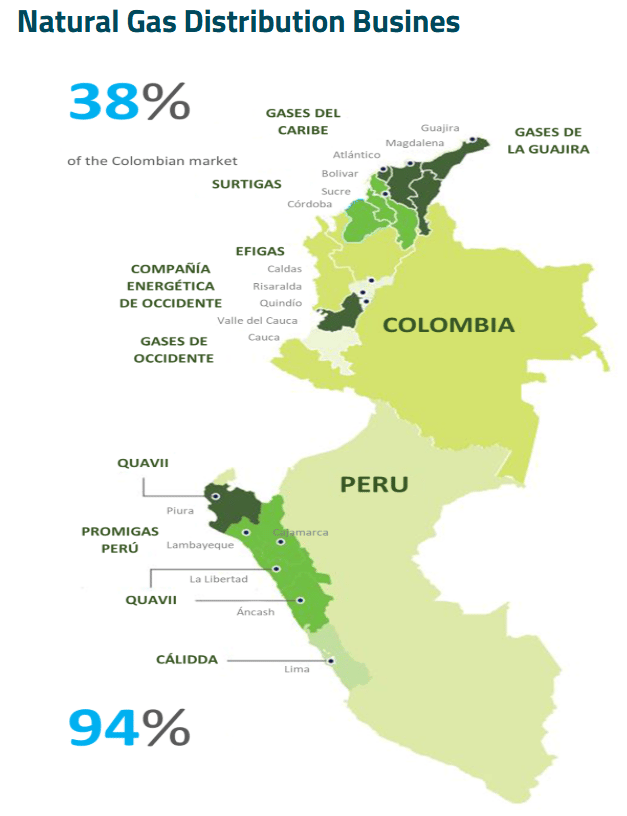
They supply natural gas to 94% of the Peruvian market and 38% of the Colombian market. (source)
(source)
The deal with CND is around a potential offtake from CND’s existing gas discovery at Piedra Redonda.
CND’s project has a 1 Trillion Cubic Feet (Tcf) discovered gas field and together with Promigas will do studies on:
- Evaluating gas production potential
- Assessing infrastructure and delivery options
- Defining integration and commercial pathways
Basically, CND’s MoU with Promigas is to work out how best to take gas from its existing gas field and bring it to market.
One thing that stood out to us was CND’s comment on “Promigas’ efforts to expand access to natural gas in Peru’s northern regions”. (source)
This region is key, because not only are the northern regions expanding rapidly, it opens up access to Colombia where Promigas already supplies gas and it borders Ecuador, which has had significant energy supply issues of late (source).
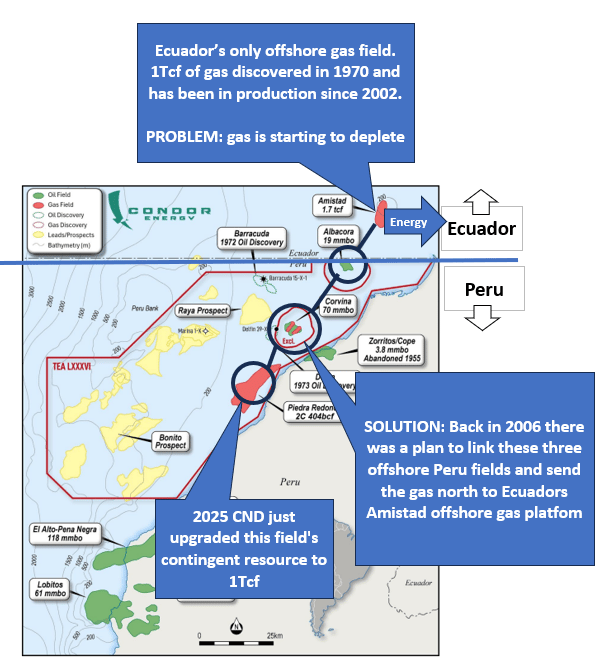
Ecuador only has one offshore gas field (Amistad) which has 1Tcf of gas and has been in production since 2002 - it’s right near the maritime border with Peru (and CND’s Peruvian acreage).
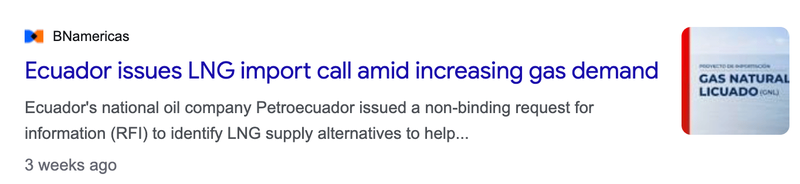
But the gas from Ecuador's field is starting to deplete and the Ecuadorian industrial sector is in need of more:
(source)
We think energy from Peru could be a part of the solution here.
Back in November 2024 the Ecuadorian Minister for Energy & Mines approved the import of 7.3 billion cubic feet of Liquefied Natural Gas (LNG) from Peru.
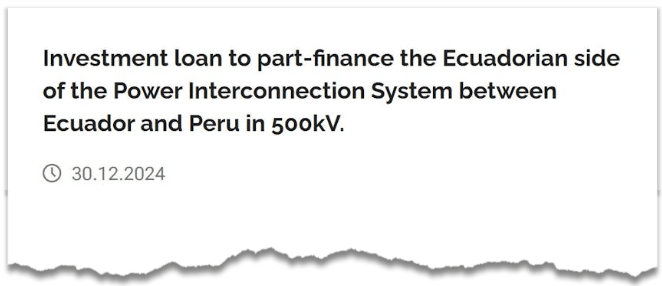
And the European Investment Bank said it would contribute US$125M to the construction of a power interconnector between Peru and Ecuador:
(source)
All of that activity is happening in and around CND’s block.
The really interesting takeaway for us from the MoU is that supplying gas from CND’s block, north into Ecuador has been explored in the past.
Back in 2006 CND’s project was almost developed as part of a plan to help solve Ecuador’s energy shortages.
The plan was to tie in CND’s gas discovery to the Amistad project to the north just over the border in Ecuador:
(source)
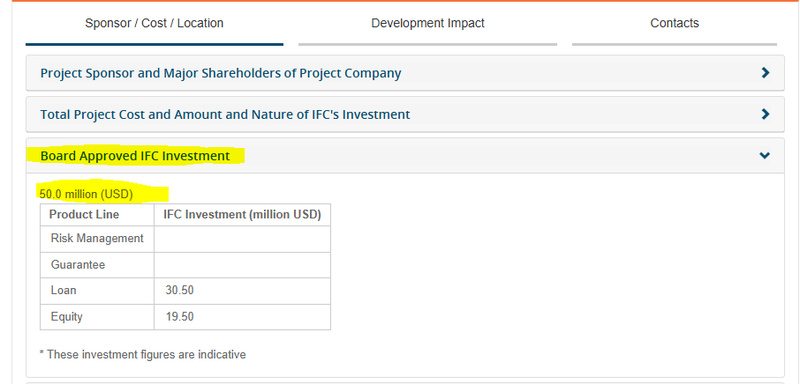
The project even had backing from the World Bank’s International Finance Corporation who was going to partially fund it.
(source)
THEN...
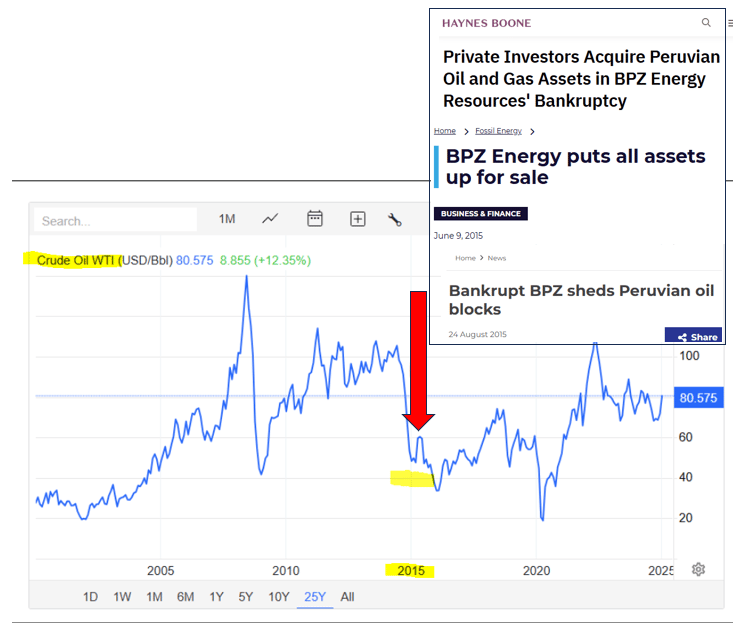
The previous owners at the time (a US company called BPZ) decided to also focus on oil and took on a huge amount of debt to develop their oil projects.
However a 2015 oil price crash eventually caused BPZ to declare bankruptcy - which led to a fire sale of their offshore Peru assets.
(source)
And now the block sits 100% controlled through a TEA by $15.5M capped CND.
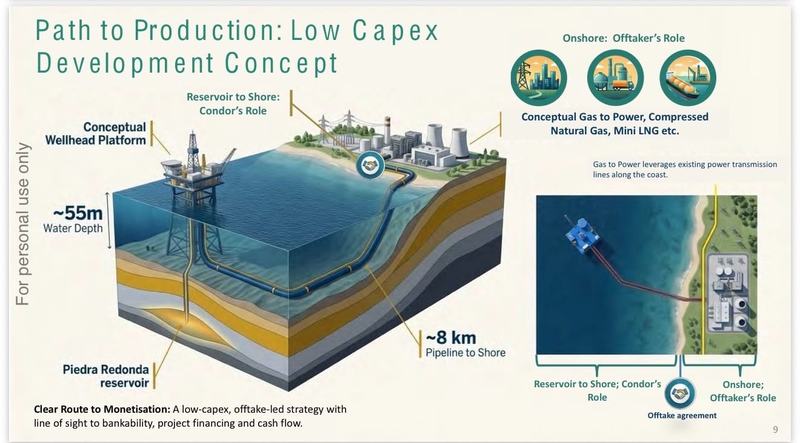
Here is a nice summary image from CND’s recent presentation showing how its gas project could be developed:
(source)
We also note there is a commercialisation study that CND has completed recently which could be something Promigas take and run with too.
We covered the work from that in a recent Quick Take here: CND completes commercialisation study for 1 trillion cubic feet gas discovery
Deep dive into CND’s 3.3BN barrel oil exploration prospects
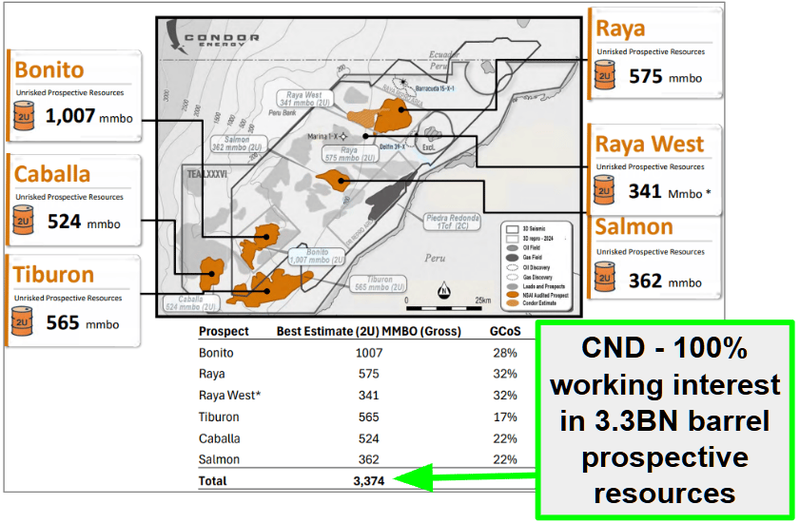
At the moment CND’s asset has a 3.3BN barrel prospective resource split across six main prospects:
(source)
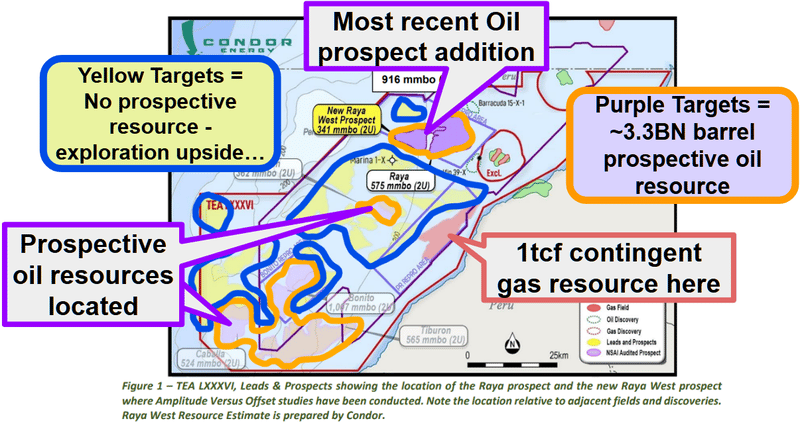
And there are a bunch of other leads that DO NOT have a resource estimate defined on them yet... so the exact upside could be a lot bigger than 3.3BN barrels:
(source)
A big part of why we like these prospects is because CND’s single biggest target is the ~1BN barrel Bonito prospect - more than big enough to be an interesting single well exploration roll of the dice.
And more than big enough to get a few interested parties into a data room and signed up to a farm-in deal.
Another reason we like these prospects is because they sit in the middle of a PROVEN hydrocarbon system.
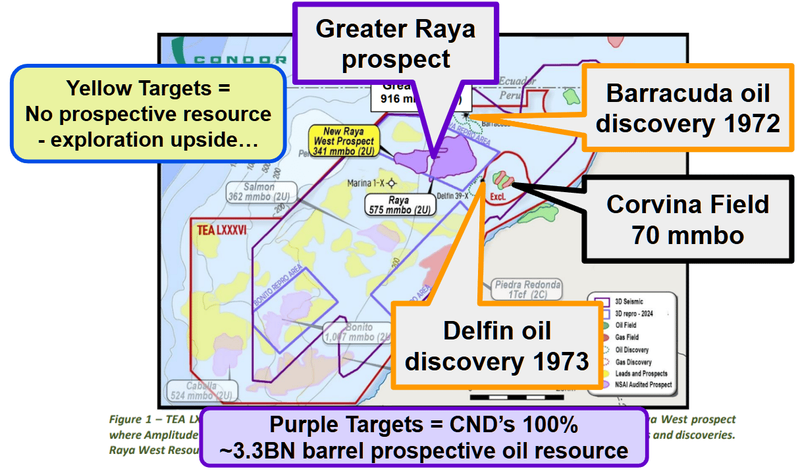
There is the Barracuda oil discovery that was made in 1972 and the Delfin oil discovery made in 1973 - both of which sit inside CND’s acreage).
AND there is the Corvina Field (excluded from CND’s block) which is currently producing oil.
As mentioned earlier, the two wider basins that CND’s block sits within have produced ~1.7BN Barrels of oil historically.
So CND’s 3.3BN barrels of prospects are in a part of the world where discoveries have been made and projects have been brought into production...
(source)
We think the oil exploration part of CND’s block is exactly what you want to see in an offshore up and coming basin.
BIG targets - with plenty of running room (follow up targets) IF discoveries get made which can help build scale to justify developing a new oil field...
(the big kicker is that it's a proven hydrocarbon system with all of that historical production - so it's technically de-risked to some extent).
What’s next for CND?
🔄 Licence application outcome
The single biggest catalyst for CND right now is the outcome of the licence contract application.
Up until now, CND operated the project under a Technical Evaluation Agreement (TEA).
Right now, CND has:
- Submitted its licence application.
- Been qualified by the regulator (meaning the regulator is satisfied that it’s shown the legal, financial and technical capability to progress),
- And is now in negotiations on the terms for an exploration and exploitation licence with the state operator.
Ultimately, the licence contract is what gives CND the right to drill and develop the block.
And we think IF successful - that grant alone could be a major catalyst for a re-rate in CND’s share price...
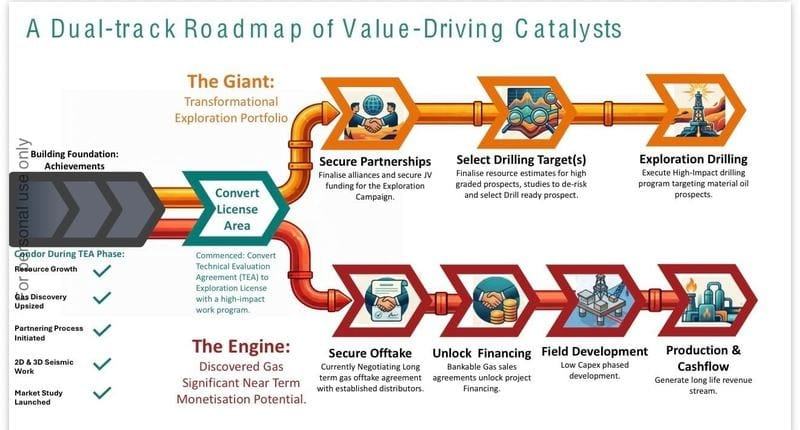
We think it will also put CND’s block in play and allow for deals to be done over the asset:
(source)
What are the risks?
The single biggest risk right now is, without a doubt, licensing / regulatory risk.
CND has APPLIED to convert its TEA into a Licence Contract - but there is no guarantee the licence is granted.
Today’s qualification doesn’t change the fact that CND could still have its application rejected.
If the market starts to price in a "no" or a long delay, CND's share price could drift lower.
Permitting risk
CND’s project is currently permitted under a Technical Evaluation Agreement (TEA) for a period of two years. Eventually before any drilling work can happen CND will have to convert it into an exploration licence. There is always a risk that the licence doesn't get granted and CND is left with no claim over the asset.
Source: “What could go wrong” - CND Investment Memo 05 December 2023
Other risks for CND
Like any early-stage oil and gas exploration company, CND carries significant risk, here we aim to identify a few more risks.
Prospective resources are unrisked estimates, and offshore drilling carries a high statistical probability of exploration failure. Even within a proven hydrocarbon system, future exploration wells could return dry holes or encounter technical reservoir issues that prevent commercial flow rates.
Offshore energy exploration is capital-intensive and far beyond the current balance sheet of a company capped at ~$15.5M. If CND fails to secure a partner to fully carry drilling costs, it will face significant cash burn and may need to execute large, dilutive capital raises.
Commercialisation and farm-out transactions are never guaranteed to reach the finish line. The discussions with dataroom parties or the MoU with Promigas may fail to convert into binding and value-accretive agreements, leaving CND to shoulder project momentum alone.
Operating offshore Peru brings jurisdictional and regulatory exposure, including potential permitting bottlenecks or shifting administrative priorities. Even after terms are negotiated, final government approvals, environmental clearances, and operational permits could face protracted delays.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our CND Investment Memo
Our Investment Memo provides a short, high-level summary of our reasons for Investing.
We use this memo to track the progress of all our Investments over time.
Our CND Investment Memo covers:
- What does CND do?
- The macro theme for CND
- Our CND Big Bet
- What we want to see CND achieve
- Why we are Invested in CND
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.