VKA - Tungsten drilling complete, visible scheelite, assays due in the coming weeks. Possible hits 500m away from current known mineralisation?
Disclosure: S3 Consortium Pty Ltd (the Company) and Associated Entities own 67,506,668 VKA Shares at the time of publishing this article. The Company has been engaged by VKA to share our commentary on the progress of our Investment in VKA over time. This information is general in nature about a speculative investment and does not constitute personal advice. It does not consider your objectives, financial situation, or needs. Any forward-looking statements are uncertain and not a guaranteed outcome.
Today Viking Mines (ASX:VKA) announced significant visible scheelite (the primary ore for tungsten) in 11 drill holes from its project in Nevada, USA.
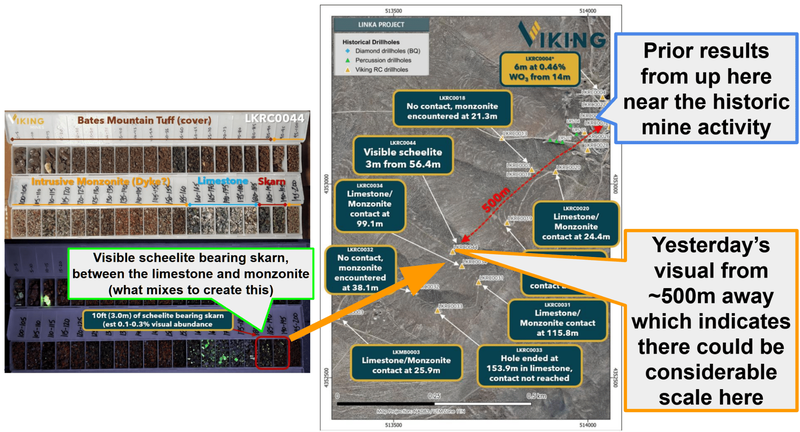
In addition to yesterday’s announcement of visible scheelite ~500m away from today’s results...
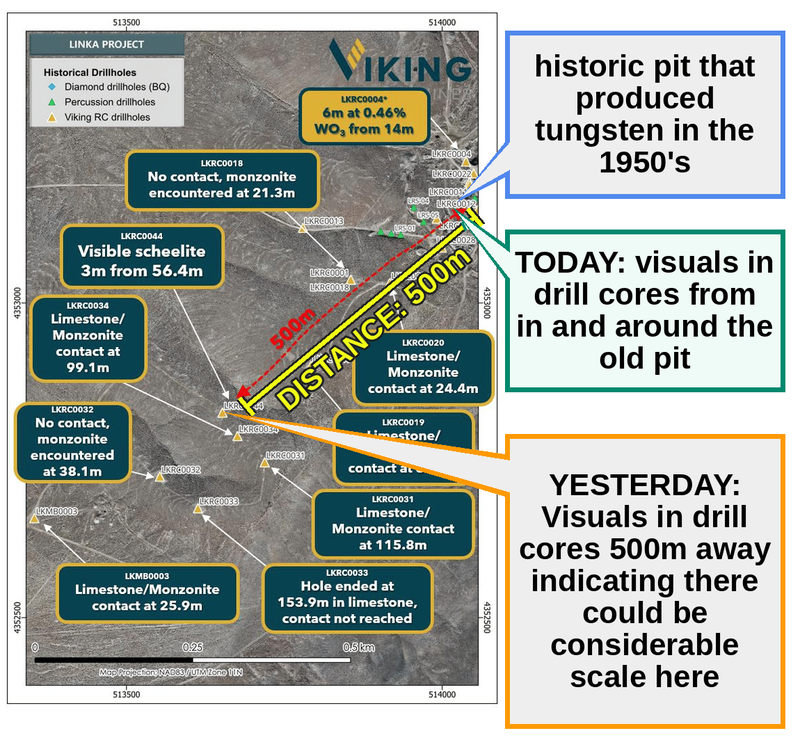
Which could mean whatever VKA is hitting in drilling in and around the old pit that produced tungsten in the 1950s could also be present ~500m away.
Now we just wait for assays to confirm tungsten grades and widths - due late November, early December - so really just a few weeks away now.
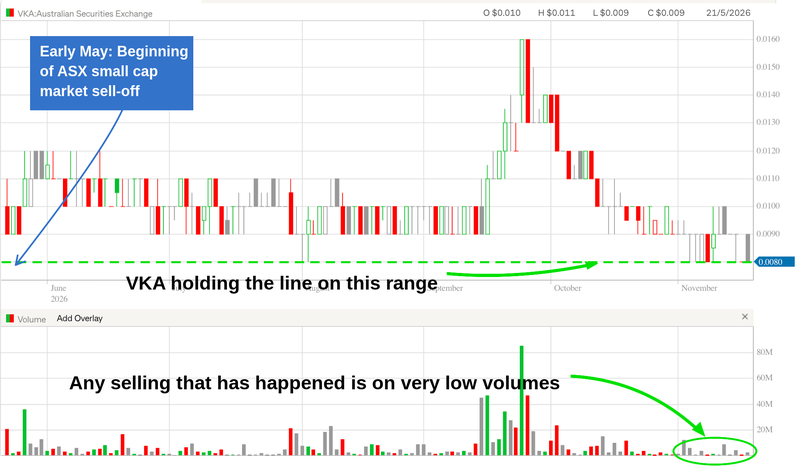
While VKA has been drilling - the tungsten macro has stepped up a gear too - probably a reason why VKA’s share price is holding up so well.
Despite everything else in ASX small cap land down 40-50-60% from the start of May to now
VKA is holding up relatively well:
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
Tungsten is a critical military mineral used in defence - fighter jets, ammunition, including Tomahawk, Patriot and Precision Strike missiles.
China controls ~85% of global supply and the USA has zero domestically mined tungsten production.
VKA’s entire strategy from the get go has been to execute a rapid production restart strategy on its project - i.e. try to get its previously producing tungsten mine back into production.
But right now it doesn’t matter how close or far away from production an ASX small cap company is.
Most are trading near their all time lows.
So why is VKA’s share price holding up despite the broad based small cap belting?
We think it's got a lot to do with how strong the tungsten macro setup is.
- There is still the 1st of January 2027 “US Defense Federal Acquisition Regulation” kicking in - banning the Pentagon (and its contractors) from buying:
“tungsten metal powders, tungsten heavy alloys, or any finished component containing tungsten heavy alloy if any step of the supply chain (mining, refining, separation, melting, fabrication) happened in China, Russia, Iran or North Korea”. (source)
(Combined, those four countries mentioned produce around 90% of the world's tungsten)
So in just over six weeks, 90% of the Pentagon's tungsten supply chain effectively becomes “illegal”.
- There is still a lot of activity in the tungsten space domestically in the US
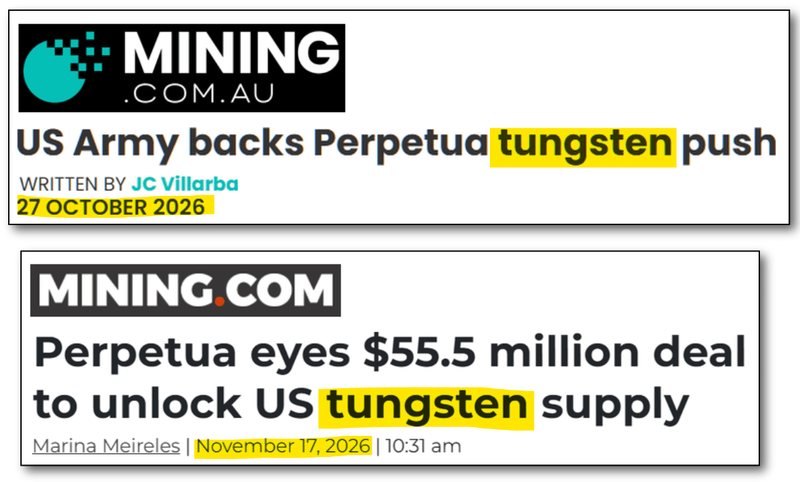
The US Army just committed up to US$40M to $3.1BN Perpetua Resources to “assess the technical and economic feasibility of producing tungsten concentrate” at its project.
And then yesterday Perpetua signed a non-binding MoU with an unnamed “Major American Aerospace & Defense Company” to “evaluate domestic tungsten opportunities”. (source)
Remember that Trump Executive Order pushing the US military industrial complex to source critical minerals from inside the US or risk losing their defence contracts?
It looks like that is working - and the defence contractors are starting to act.
While all of that has happened, VKA has been drilling at its project.
And today hit some pretty epic drillcore pics:
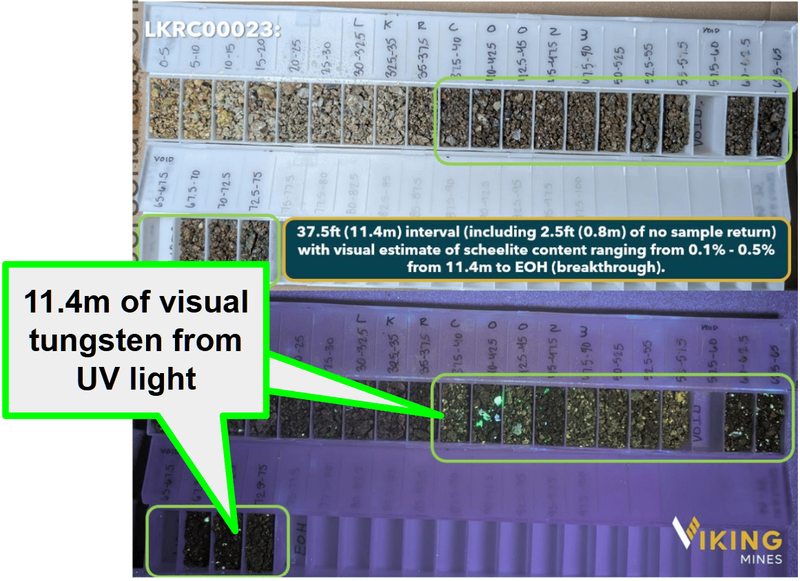
(source - Scheelite, the main tungsten mineral, glows under UV light)
Today’s set of visuals all came from in and around that old pit that was responsible for ~65,000t at ~0.5% tungsten production using a 360 tonne per day mill in the 1950’s.
The more interesting set of visuals were in VKA’s announcement yesterday - ~500m away from anything that is “known”.
(source)
The key thing from yesterday was that VKA actually hit the “limestone and monzonite contact” - validating VKA’s whole exploration model which is to find that contact zone, where it thinks the tungsten mineralisation will be.
And that is not just an internal exploration theory - the US Geological Survey has also talked about it relative to VKA’s project saying “the Linka deposit is near vertical, paralleling the intrusive contact” and “there is a good possibility that similar ore shoots are present along the contact zone north and south of the mine”. (source)
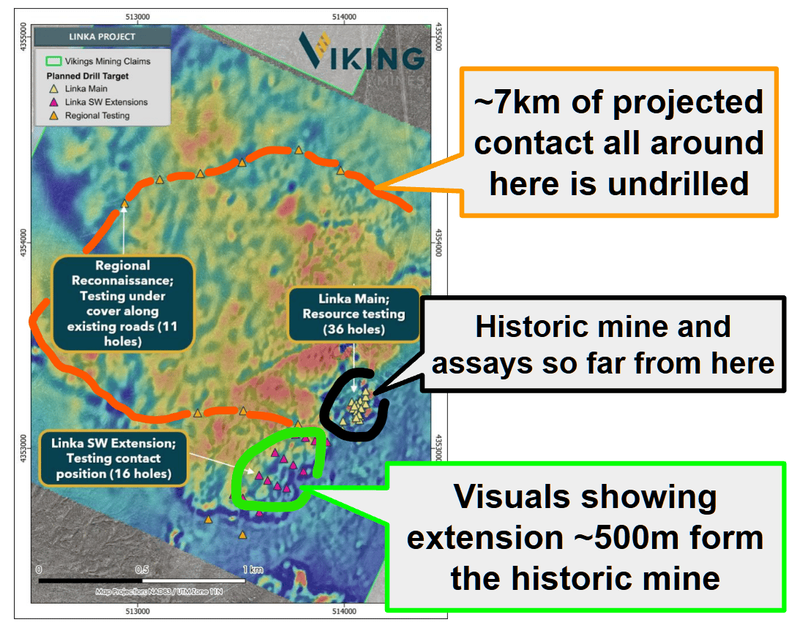
VKA now has one possible hit ~500m away AND ~7km of that contact untested:
(source)
IF assays confirm yesterday’s visuals as mineralisation AND VKA can follow it up and grow what it’s found we think it could feed into VKA’s “rapid restart” strategy.
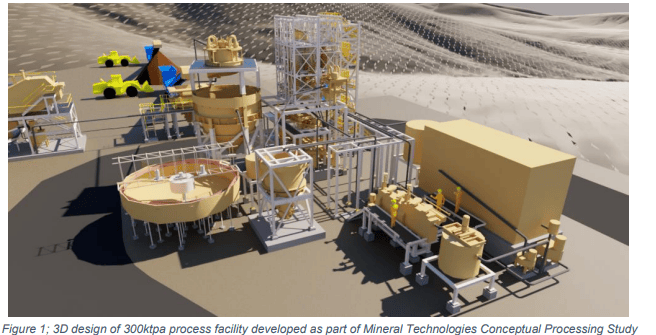
VKA has done so much already that it even has concept renders of what a processing plant might look like:
(Source)
VKA’s plan is to build that modular plant and process its own material.
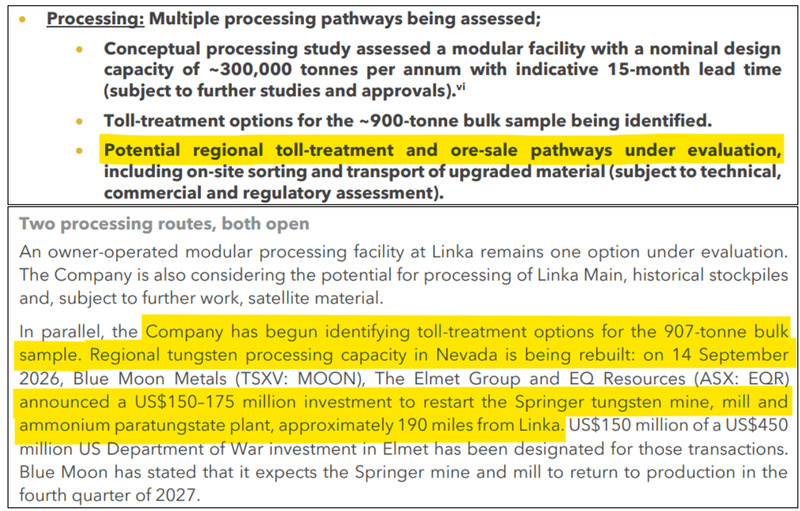
BUT we also know VKA is very receptive to toll treatment of its ore - here is what VKA said in an announcement on the 3rd of November:
(VKA also has approvals in place for a ~900t bulk sample to be processed by a US toll treater - a nice way to produce some samples for any partners?)
(source)
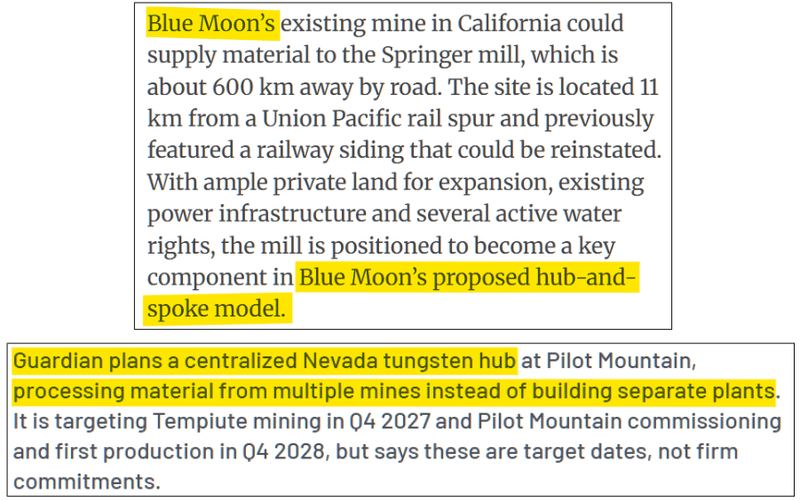
Right now there are two companies looking to build tungsten processing hubs in Nevada and both have received some sort of US government funding support.
One is Blue Moon who only a few months ago received part of the US$450M Department of War package, with US$150M designated to restart its Springer mine and mill (source).
The other is Guardian Metals - which owns the largest tungsten resource inside the USA.
(more on how VKA compares to Guardian in a second).
Blue Moon and Guardian are pretty public about wanting to buy smaller high grade mines in the US and then process it through their central plants:
And of course there is also VKA’s cornerstone shareholder ~$65M American Tungsten (who own ~6% of the stock).
And American Tungsten’s CEO Ali Haji has gone public talking about potential for consolidation + M&A:
"So the Viking investment was one that was made given, when we looked at our ability to mill as opposed to the DSO model, we started to look at additional assets to make sure that Patterson, Idaho, which is where our asset is, starts to become a processing hub for Tungsten.”
"So there is a cash investment there that ultimately has now more than doubled since we made that investment or have committed to the investment. And the intent here is, you know, it could end up being part of a roll-up strategy for us in the future, but it's nice to get in at the early, at this early entry point."
"I think we will start to see larger organisations that are perhaps not entirely tungsten-focused start to take aim at tungsten assets. So I think the space is only just starting to heat up."
(source - check out the full interview here)
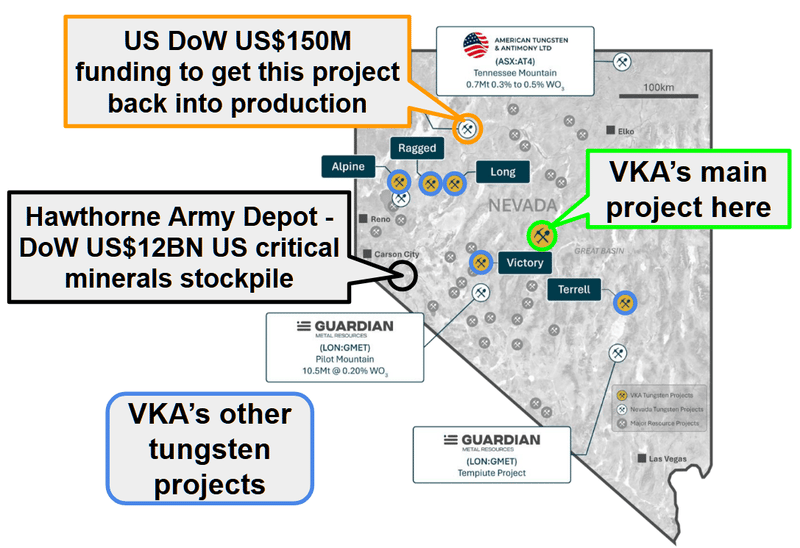
Just taking a look at the Nevada map of tungsten projects, none of those are MASSIVE in their own right - so there could be some regional consolidation opportunity here too...
(source)
Oh and FUN FACT:
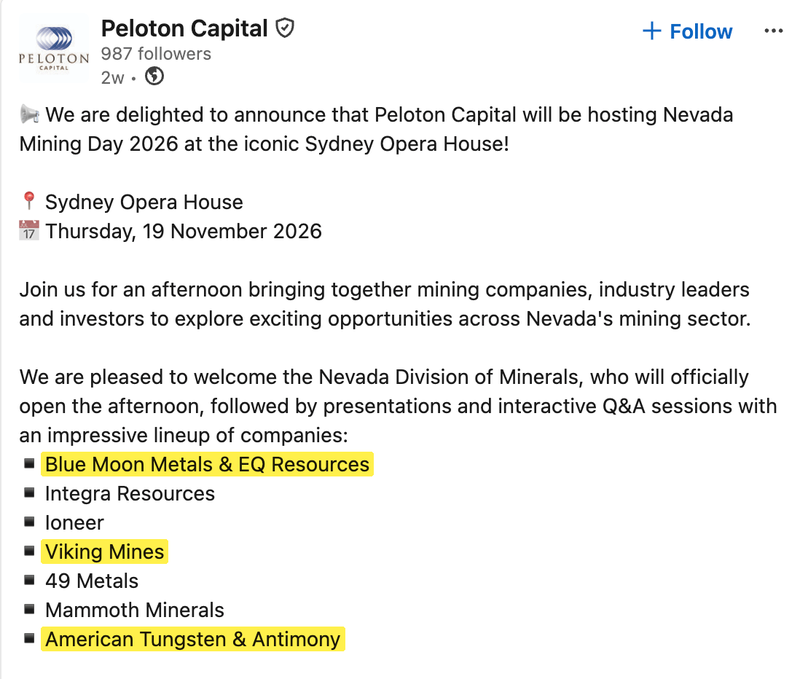
VKA is presenting today at an event with Blue Moon as well as American Tungsten and Antimony TODAY (we are attending):
(source)
Who knows what happens in the long run - in the short term though, we think the projects with a realistic pathway to production will attract the most funding.
How does VKA’s project compare to some of the other projects in the USA?
As we saw with the DoW deal in September - VKA’s project doesn’t need to be massive.
In fact, you don't even need a resource - Perpetua Resources which received a US$40M commitment from the US Army and the non-binding MoU with the defence contractor has NO tungsten resource.
The project the DoW backed with the US$450M in funding only had a resource of 2.1Mt at 0.5% tungsten (source).
The only “Small” cap to receive funding was A$220M capped Guardian Metal Resources which owns one of the biggest known tungsten deposits in the USA.
Back in July 2025 Guardian Metal received a US$6.2M grant from the US Department of Defense. (source)
Guardian’s deposit averages a ~0.178% grade, and recently put out a Pre-Feasibility Study showing a post tax NPV of up to ~US$1.4BN. (source)
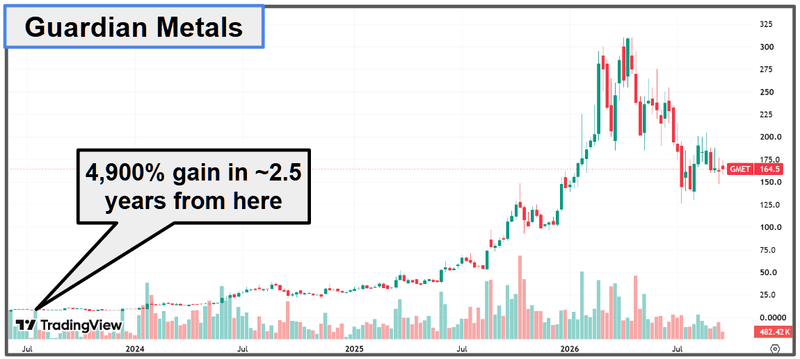
Guardian Metal’s resource also took it to a ~A$1.1BN market cap - up almost 5,000% from its June 2023 low to the high in April this year:
The most interesting part is that almost all of Guardian’s share price appreciation was driven largely by three key drivers.
- Guardian received US$6.2M from the US Department of Defense in July 2025.
- Then it completed a technical study in December (incorporating drilling data from 68 old holes).
- Then Guardian completed a US listing raising ~US$60M.
(source)
The past performance is not and should not be taken as an indication of future performance. Caution should be exercised in assessing past performance. This product, like all other financial products, is subject to market forces and unpredictable events that may adversely affect future performance.
We think VKA is executing a similar playbook - arguably into a much hotter tungsten macro setting.
Remember Guardian back in December 2023 was only capped at ~$12M.
After the current round of drilling, we think VKA could be in a position to present a more comprehensive re-start plan.
And if any of the funding deals we mentioned above are anything to go by - it could open the door for something similar for VKA.
All we need to see now is a few million tonnes at that ~0.2-0.5% grade and it could be game on for VKA...
VKA is executing our US critical minerals playbook
A big part of our US critical minerals Investment thesis is:
- Public and private capital will mobilise and look for critical minerals projects to back, and
- The companies who have the right assets, with the right combination of US exposure will be the ones to attract that capital.
We put out Our “playbook for small ASX stocks advancing US critical minerals projects” - which is what we think ASX small caps need to do to put themselves in the best possible position to attract that capital.
The more of the boxes in our list a US critical minerals stock can tick (and quickly), the better (we think) they can position themselves to capture US capital and attention.
Here is everything VKA has done on that list:
- ✅ Own or acquire a US based critical minerals project
- ⬜ Appoint Washington lobbyist
- ✅ Spend time in USA or appoint US based operations person
- ⬜ Appoint experienced, big name advisors or board members.
- ✅ List on the US OTC market (Trading as VKALF from 14 Apr 2026)
- ⬜ Commence NASDAQ or NYSE listing process
- ✅ Acquire, license or partner with downstream processing technology.
- ✅ Deliver early metwork and processing of bulk samples ahead of drilling
- 🔄 Prove samples can be processed, deliver downstream product. (lab scale only, approval received for ~900t bulk sample to be processed by a US toll treater)
- 🔄 Secure US government funding. (DIBC application lodged, and VKA has started talks with US federal agencies on FAST-41 status)
- ✅ Attract interest from US investors (American Tungsten Corp put in $750k)
- ✅ Outline plan for small, cheap and fast mine (Conceptual plant design released 30 Jul 2026, 300ktpa modular "Rapid Start" gravity circuit)
- 🔄 Deliver drilling success on project (First assay 14m at 0.56% tungsten, 48 holes completed, assays through to December)
- ⬜ Use larger market cap to bolt on later stage or advanced US projects.
- ⬜ List on major US exchange
- ⬜ US investor roadshows
- ⬜ Deliver domestic US critical minerals supply
Luckily VKA’s been going pretty hard and fast on its project for nearly 12 months now since it got hands on the project.
And now, with a drill program under its belt, VKA could end up being one of the few names that has developed a story big enough to be eligible for funding deals.
Which brings us to VKA’s current drill program...
VKA’s project is still relatively underexplored
When we first Invested in VKA back in December 2025, the project had a history of tungsten mining and just a few modern sample results.
Since then, VKA has 8x'ed the exploration upside, by growing the known strike from ~800m to ~7km by:
- Acquiring a historical exploration database.
- Digitising the old drilling data
- Digitising the project's geological model.
- Doing more sampling and mapping.
- Completing geophysical surveys.
- Pulling all of that data into a 3D geological model to identify the highest-priority drill targets.
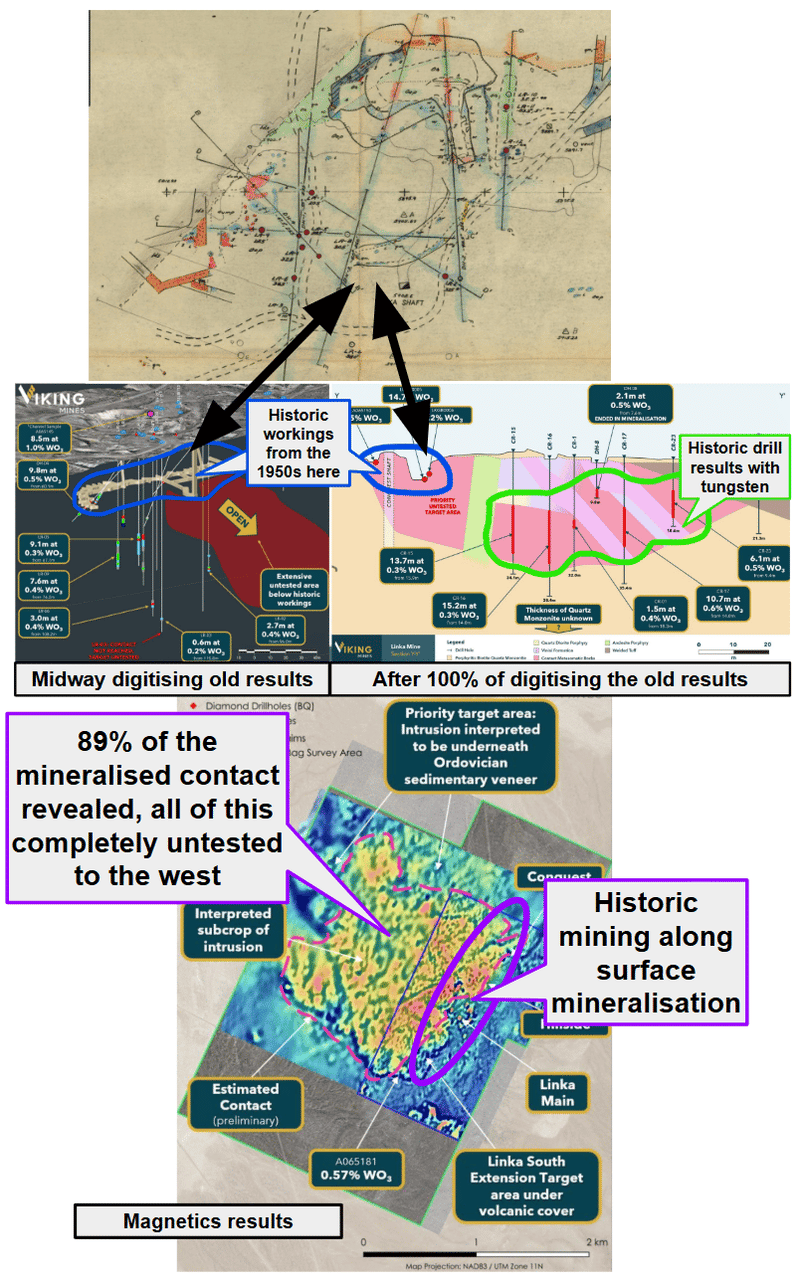
VKA turned old pieces of paper like this into a modern, drill-ready 3D model and target set:
(source)(source)(source)(source)
VKA’s theory is that the entire edge of that magnetic anomaly could host tungsten mineralisation (~7km total perimeter).
That’s why we think yesterday’s visuals are material - because they sort of validate VKA’s exploration model (of there potentially being mineralisation across the edge of that anomaly).
Of course, we will need assay results before we can say anything for sure here.
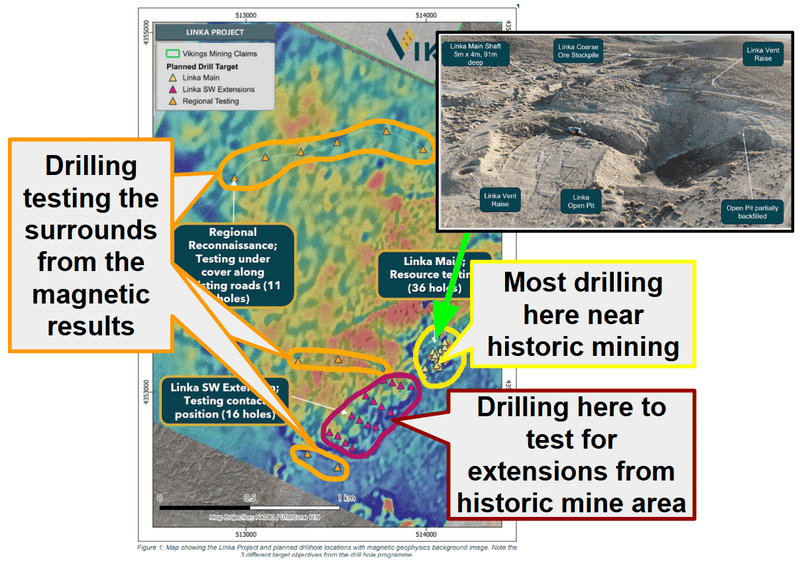
The absolute blue sky outcome for VKA would be if we start to see mineralisation all across this perimeter:
Ultimately, we are in VKA to see it take all the drilling data and incorporate it into its rapid restart strategy which is a big part of our VKA Big Bet as follows:
Our VKA Big Bet:
“VKA re-rates to $100M+ market cap with a fast to market tungsten production and downstream strategy, as well as continued interest and capital flows into the USA critical metals thematic”
NOTE: our “Big Bet” is what we HOPE the ultimate success scenario looks like for this particular Investment over the long term (3+ years). The scenario is speculative and does not represent a valuation or forecast. There is no guarantee that our Big Bet will ever come true. There is a lot of work to be done, many risks involved, including development risk, country risk and commodity price risk - just some of which we list in our VKA Investment Memo.
Success will require a significant amount of luck. Past performance is not an indicator of future performance.
What's next for VKA?
🔄 VKA’s first drill program at US tungsten project
Here are the milestones we are tracking for the drill program:
- ✅ Drilling starts
- ✅ Visuals
- ✅ Drilling completed
- 🔄 Assay results (expected throughout December)
🔄 VKA’s rapid restart plan
We also want to see VKA progress its rapid mine restart strategy, VKA announced a 5 pillar strategy on this recently. (source)
Here are the milestones we are tracking on that front:
- ✅ Assay results from stockpiles + tailings dam
- ✅ Processing study results
- ✅ Processing plant concept renders
- 🔄 Metwork optimisation (Ore sorting + flotation testwork).
🔄 US engagement
This is more of a corporate milestone we want to see VKA hit.
It’s hard to predict when any of these might happen, but we are hoping VKA can attract some sort of US government funding to help finance its project AND/OR attract strategic interest from inside the US.
Recently VKA again mentioned FAST-41 talks and also mentioned the investments that the US government is making to recreate a domestic tungsten supply chain:
(source)
What could go wrong?
In the short term, the key risks will be “exploration risk”.
VKA has assays in the lab from its drill program and having visuals out in the market could mean
Exploration risk
There is no guarantee that VKA's upcoming drill programmes will be successful. VKA may fail to find economic deposits of tungsten in which case we would expect the share price to re-rate lower.
Source: “What could go wrong” - VKA Investment Memo 16 December 2025
Other risks
Like any early-stage exploration company, VKA carries significant risk, here we aim to identify a few more risks.
While the SW Extension hit shows the right geology ~500m from Linka Main, it is one hole with 3m of visible scheelite estimated at 0.1 to 0.3%, and the December assays could come back below what the visuals suggest.
Although VKA plans to apply to the BLM for new drill sites at the SW Extension, the timing of those approvals is outside its control, and any delay could push back follow up drilling.
With the US military ban on Chinese tungsten starting at the end of December, much of the current interest in US tungsten is policy driven, and any delay, waiver or softening of that rule could cool investor appetite for the sector.
While regional toll treatment is a live option with Springer being restarted ~190 miles away, VKA has said no toll treatment or ore sale arrangement has been secured, and Springer is not expected back in production until the fourth quarter of 2027.
Although American Tungsten's CEO has spoken publicly about a potential roll up, these are comments only, there is no proposal, and any future consolidation may not come on terms that suit VKA shareholders.
Investors should consider these risks carefully and seek professional advice tailored to their personal circumstances before investing.
Our VKA Investment Memo
You can read our VKA Investment Memo in the link below.
We use this memo to track the progress of all our Investments over time.
Our VKA Investment Memo covers:
- What does VKA do?
- The macro theme for VKA
- Our VKA Big Bet
- What we want to see VKA achieve
- Why we are Invested in VKA
- The key risks to our Investment Thesis
- Our Investment Plan
General Information Only
This material has been prepared by StocksDigital. StocksDigital is an authorised representative (CAR 000433913) of 62 Consulting Pty Limited (ABN 88 664 809 303) (AFSL 548573).
This material is general advice only and is not an offer for the purchase or sale of any financial product or service. The material is not intended to provide you with personal financial or tax advice and does not take into account your personal objectives, financial situation or needs. Although we believe that the material is correct, no warranty of accuracy, reliability or completeness is given, except for liability under statute which cannot be excluded. Please note that past performance may not be indicative of future performance and that no guarantee of performance, the return of capital or a particular rate of return is given by 62C, StocksDigital, any of their related body corporates or any other person. To the maximum extent possible, 62C, StocksDigital, their related body corporates or any other person do not accept any liability for any statement in this material.
Conflicts of Interest Notice
S3 and its associated entities may hold investments in companies featured in its articles, including through being paid in the securities of the companies we provide commentary on. We disclose the securities held in relation to a particular company that we provide commentary on. Refer to our Disclosure Policy for information on our self-imposed trading blackouts, hold conditions and de-risking (sell conditions) which seek to mitigate against any potential conflicts of interest.
Publication Notice and Disclaimer
The information contained in this article is current as at the publication date. At the time of publishing, the information contained in this article is based on sources which are available in the public domain that we consider to be reliable, and our own analysis of those sources. The views of the author may not reflect the views of the AFSL holder. Any decision by you to purchase securities in the companies featured in this article should be done so after you have sought your own independent professional advice regarding this information and made your own inquiries as to the validity of any information in this article.
Any forward-looking statements contained in this article are not guarantees or predictions of future performance, and involve known and unknown risks, uncertainties and other factors, many of which are beyond our control, and which may cause actual results or performance of companies featured to differ materially from those expressed in the statements contained in this article. S3 cannot and does not give any assurance that the results or performance expressed or implied by any forward-looking statements contained in this article will actually occur and readers are cautioned not to put undue reliance on forward-looking statements.
This article may include references to our past investing performance. Past performance is not a reliable indicator of our future investing performance.